NAN: Is it squeaky clean?

For this discussion I am going to discuss a company that has caught the interest of many a small cap investor over time, I will cover Nanosonics (ASX:NAN) following their latest report.
Background
NAN is a company focused on manufacturing sterilising medical equipment, more specifically ultrasound machines. Their flagship Trophon 2 product is a market leader and has been for some time.

Trophon, sterilises ultrasound probes without chemicals. It is about as big as a small microwave. And on top of selling the actual units, it also makes money selling the consumable part of the device, which contains a hydrogen peroxide solution which was developed by them.
In the latest annual report the company said it has 32.450 units installed globally, the majority of those in North America (87%). In the past 12 months this was an increase of 9%.

This latest result was a strong one for the company. Particularly in light of the developments in recent years - I will discuss those below in the “Investment Backstory” section.
The company grew global revenue by 38% to $166 million, with the all important North America division seeing a 41% jump. This is very important for a reason I will discuss in a moment. Reasons attributed to the result included increases in total units installed, increased consumables associated with the new installed base, increase in service revenue and favourable pricing and foreign exchange. All around a strong result.
The foreign exchange movements also aided margins which improved on last year significantly achieving its highest rate since FY19. Favourable consumable pricing also helped.
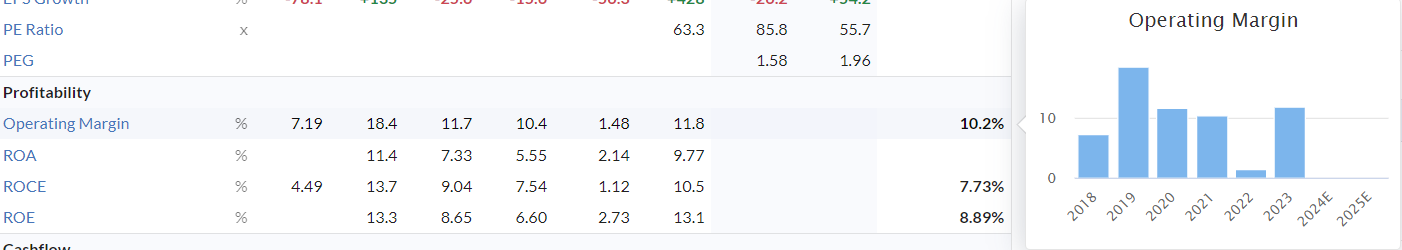
So whilst expenses rose they managed to achieve a rarity this reporting season by improving margins. Again, another reason for this exists and I will explain that in a moment.
The improvement in margins translated to an almighty profit lift over the past twelve months with the company achieving a record net profit after tax figure of $19.9M. Resulting in EPS growth of over +400%. Further, cash improved significantly over the period and the company has very low levels of debt.
With the company smashing it out of the ballpark in terms of result, the market’s response has been somewhat mooted. To understand why, we need to have a bit of a history lesson.
Investment Backstory
I remember covering NAN, and investing in NAN many years ago. Its sterilisation technology was a real game changer for ultrasound users, though while revenue has consistently grown, profit on the other hand has been quite lumpy.
There have been quite a few sceptics of NAN in recent times. The stock had fallen from a peak of $8.25 in Jan 2021 to $2.97 in Jun 2022.
At one point, in early to mid 2022 there was some 12% of the company’s stock shorted (stock that has been sold before it is bought - a heavy indicator of bearish sentiment) which made it the most shorted stock on the ASX .
The skepticism hit fever pitch when NAN decided to bring its North American sales model in house rather than rely on its long standing GE Healthcare distribution partner. Obviously this is a big deal as the risk of killing the goose that lays the golden egg was a big risk.
This negative view was somewhat vindicated at the time as in 2022 we saw a big fall in profitability as the cost of establishing a new sales team and process far outweighed revenue growth.
However CEO Mark Kavanagh stood up to an angry mob of investors claiming that his was a long term story and that this was 'short term pain for long term gain.' Since that 2022 result, the market has eased off on the pressure. When looking at short interest, the stock is now only 2.4% shorted, which is it's lowest level since 2021. Further vindication has come following the release of these set of numbers. Record revenue, controlled costs and record profitability all point to a business now in control of its own destiny (as opposed to being one item of a longer GE Healthcare shopping list) and improves operating leverage significantly with more money reaching the bottom line for every sale.
But despite the strong result, the price still hasn’t risen. Why so? That is because of the other part of this story which is the impending release of its Coris product, a sterilisation machine for flexible endoscopes.
At the moment, NAN is a one product business in Trophon. But there are obvious other possible beneficial uses for it sterilisation technology, it has always been the company's intention to release more products. Coris was the product flagged for next release from the company and was introduced to the market at the time of its 2019 AGM.
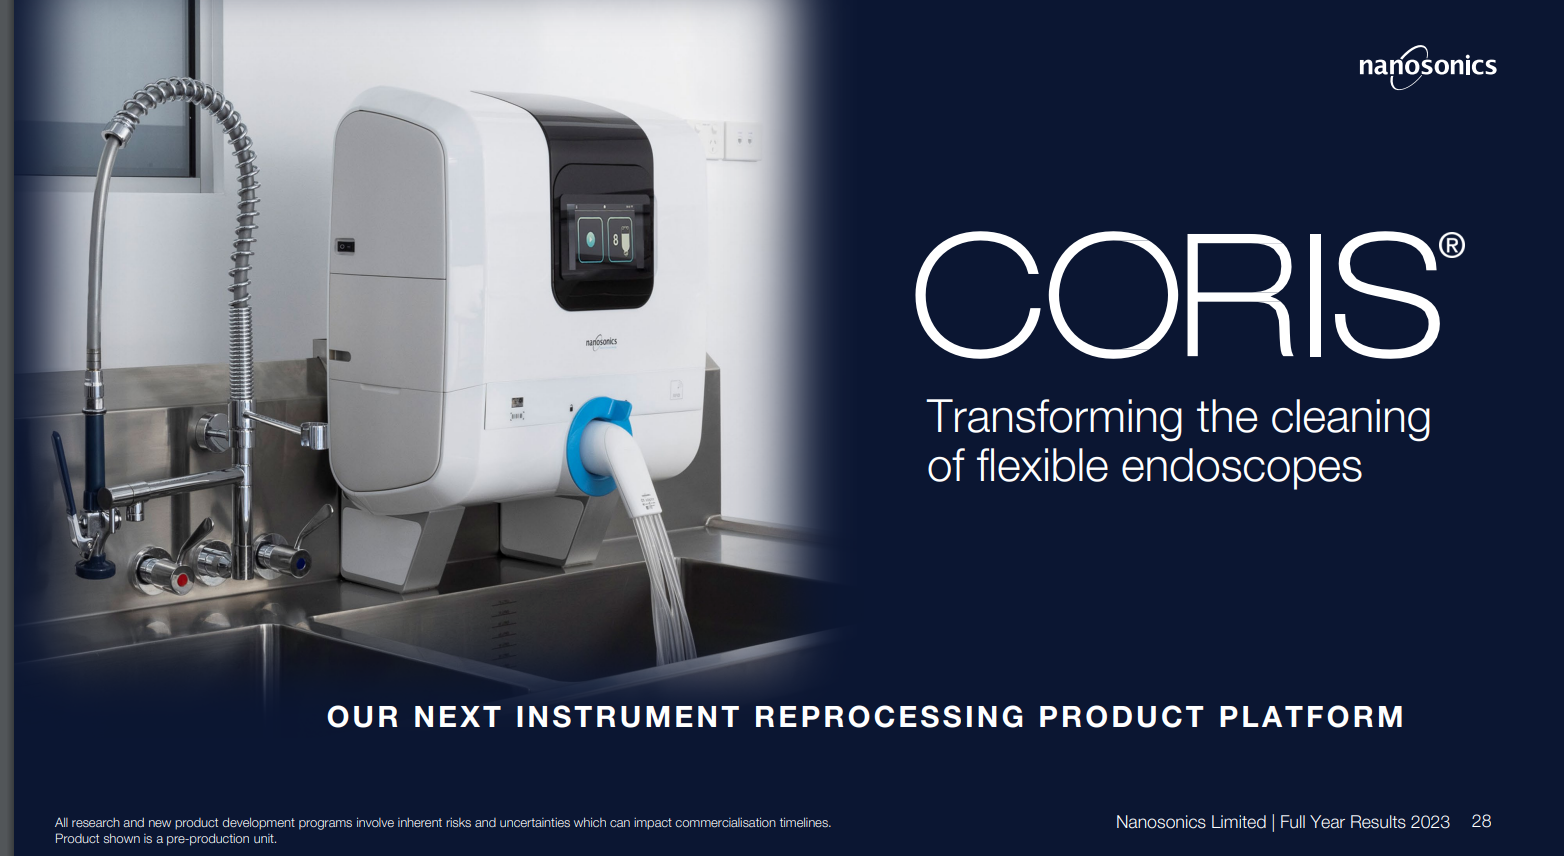
The potential for this product is huge with over 60 Million procedures each year globally (over half of which are completed in the US). Reusable flexible endoscopes are highly sophisticated medical devices designed to enable advanced diagnostic and interventions to diagnose and treat cancers and other life-threatening conditions. The company often quotes reports which state that more healthcare-associated outbreaks have been linked to contaminated endoscopes than any other medical device (prior to COVID of course.)
There are many different types of flexible endoscopes, but the vast majority performed on a yearly basis are for gastrointestinal endoscopies and colonoscopies and Coris is designed to clean those. Then at the time of its annual result in2021, it flagged a commercial release date of 2023 calendar year.
However at the time of its full year report this year the company flagged that following discussion with the FDA, they provided notice that they want to see certain testing conducted in the US (previously flagged to be performed at the NAN HQ in Sydney.) This will necessitate the set-up of a clinical simulation laboratory in the USA like they have in Australia. This means a blowout in timeframes and costs.
In terms of timeframe, the submission date submission date will likely move into Q324 delaying the release of the product globally given the geographical significance of the US. In terms of costs it now means the company has flagged that expenses will likely rise quicker than revenues in the coming year. This was definitely NOT what the true believers in the stock had hoped.
Unfortunately the company has a bad reputation flagging product releases and extending timelines, while many may point to external factors being the major contributor, the market has got the sense of the boy who cried wolf, irrespective of how good the results are.
The company has been investing significantly in R&D for some time, the last full year seeing a 32% increase on the prior year to all time records. Investors had hoped there would be an easing given the lofty valuations the stock sits one, but instead it looks like they will have to ramp up even higher.
The company even highlighted that the Trophon business without the COris spend would actually be more than twice as profitable than what it currently is, twisting the knife further for long term supporters.
The good news for those disappointed by this outcome is that Coris has “de novo” classification from the FDA meaning there is no similar solution in the medical field and therefore it will get priority focus when the submission is officially made.
Understanding these points above is essential if considering a position in NAN
StockRanks

Based on the current numbers, operationally the company looks quite good.
The stand out was Quality. The company is profitable, generating strong cash and has very low debt.

The company also has full marks under the Piotroski F-score. There is very little to add here and the company is deserved of its 99 Q-ranking
But it's obvious to see that the major failing for NAN is that it currently trades at lofty valuations relative to the broader market. This is a common affliction for profitable healthcare equipment businesses (such as PME, COH). Investors would have hoped an easing in R&D expenditure would have helped widen margins enough to justify such a multiple. However at a PE +75, EV/EBITDA of +45 even after price has fallen some 30% since its 52 week high means that you are still paying for a lot of potential - which to be fair is huge as discussed earlier.
Momentum as expected has eased, not just because price has collapsed recently, but also because analysts have downgraded EPS expectations on the back of increased R&D spend.

Analysts are split on the business between those that see the possible opportunity, those that feel it is expensive, and others that question the company’s ability to execute given so many false starts.
I would hope for some stabilisation in price first before considering a position at this point.To me though, the fact it is holding $4 is important. At least it is not at 52 week lows, and really only finds itself back where it started 12 months. Yes, frustrating for investors as it pays no dividend, but not the worst case scenario… not yet anyway.

ASX:NAN Daily chart 1 year
In terms of ownership of the business, brothers Maurie and Bernard Stang, one of the earlier executives of the business still retain significant holdings amongst themselves though this has been declining. The remainder are your usual mix up of institutional and private investors but there is enough liquidity for all retail investors.
Unfortunately Director buying and selling doesn’t instil the greatest confidence here. Even CEO Mr Kavanagh sold shares (only a small amount) in June. While it is dangerous to speculate about such things, one wonders what was known prior to the FDA announcement. Seems strange that a company could prepare an entire annual result presentation and then immediately change it, based on this new significant information. Perhaps the company should have released news of this FDA delay as a price sensitive announcement before the result when it was first known?

Conclusion
Now that much of the steam has come out of the price, it could be an opportunity to NAN. There is no sugar coating it though, there have been disappointments, particularly in regards to the constant R&D blowouts, but the bottom line is much of its future direction will be captured in the release of Coris, irrespective of what Trophon or the new sales team does from here.
I wouldn't necessarily say NAN is a bargain, but for those looking for a “story stock” with huge “potential” that actually generates its own cash to pay its expenses and is high Quality, then NAN is someone to consider once price settles, I’ll be watching (the stock that is…. Not readers.)
Important Information: Stockopedia Ltd ABN 39 757 874 670 UK business registration number 0637267 (“Stockopedia”) is an Authorised Representative of Daylight Financial Group Pty Ltd ABN 77 633 984 773 (“DFGPL”) which is the holder of an Australian Financial Services Licence (AFS Licence No. 521404).
Information in this commentary is current as at date prepared unless otherwise stated. However, please bear in mind that investments can go up or down in value, and that past performance is not a reliable indicator of future performance. For more Important Information please refer to the Disclaimer section of this website.
This communication may contain general financial product advice. It has been prepared without taking into account your personal circumstances, and you should therefore consider its appropriateness in light of your objectives, financial circumstances and needs before acting on it.
If our advice relates to the acquisition or possible acquisition of a particular financial product, you should obtain a copy of and consider the Product Disclosure Statement (PDS) before making any decision.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
2 comments
Thanks Elio. Interesting that the company indicates their market penetration is about 23% (globally), so you would think there is plenty more growth to come. However they will need it to grow into that market cap. Interesting company and one I'd like to own if it gets cheap enough.
Excellent appraisal Elio, thank you. One I've been following for quite a while, waiting, waiting waiting...