Nationwide Accident Repair Services - ticking the big three

That somewhat cryptic subtitle comes from a renewed focus on simple, logical principles; the big three for any investor, and the three statements in an annual report. They are, of course, accounting earnings, cash flow and assets. I put together a screener on Sharelockholmes focusing on those and found myself mildly surprised, mostly because it had a lot of companies I had looked at, and a few I owned. Reassuring, at least, that my portfolio still matches my evolving standards! Breaking down the parts, anyway, I wanted companies on a low price to tangible book (beneath 2) whose cash flows were reasonably similar to their accounting earnings over the last 5 years and whose prices didn't exceed a multiple of 10x their last year's earnings, or 14x their last 5 years. I reckon that broadly covers the bases of 'not too expensive' and 'not too dodgy'.
One of the shares that met all those criteria was Nationwide Accident Repair Services. Their business model makes them mostly business-facing; they interact with the insurance companies who pay them for the privelege of repairing covered cars, though as part of their 'three year growth plan' Chairman Michael Marx sets out a renewed attempt to target both fleet operators and the retail market where they are 'relatively under represented'. The announcement plunging them firmly into potential value territory came last November, when Nationwide issued a profit warning due both to the economic climate and unseasonably mild weather. Since both of these can be expected to be mean reverting, a 33% drop in the share price catches my eye as a potential over-reaction.
The graph confirms the screener's criteria of consistency, and the metrics below certainly make it look cheap - though I'd take both the dividend yield and forward P/E with a big dose of caution. The forecast for next year's earnings look very optimistic given what management have already said, and dividends always look shaky on a background of declining earnings. The strong book is mostly comprised of trade and other receivables, which should be reasonably safe given the customer makeup - mostly insurance companies. Debt is nonexistent, though the company does have a not-insignificant amount of obligatory lease payments to make over the next 5 years and beyond, totalling £51.8m. The company also has my pet hate - pension obligations - sitting on balance sheet, though they're in the asset section at the moment.
The graph left below shows an unsurprising but still risk-increasing feature of the business; the heavy customer concentration in the top 3. Perhaps this is why Nationwide is seeking to diversify revenue streams with retail and business clients. Either way, with over 50% of revenue in the hands of these top 3 (unnamed) customers, the loss of any one of them would seriously dent the overall business performance. While the risk of that is impossible to quantify, the more obvious implication is that it leeches a degree of pricing power away from Nationwide and into the hands of the customer. Such is the price of working with giants of business - just think of how the suppliers of milk to the supermarkets feel, for instance!
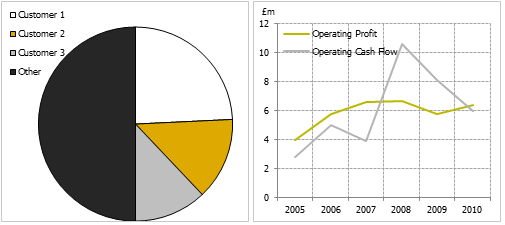 On a more positive note, the graph to the right plots the operating profit and operating cash flow over the last 5 years, and confirms the indications of the screener. Unfortunately, operating cash flow isn't a particularly good statistic to use for the cash the company is actually 'generating'; by taking out the impact of depreciation but not including the impact of maintenance capex, you're essentially just milking your assets for profit until they run dry. Still, depreciation isn't a huge adjustment on the statement, and taking it out still leaves pretty decent cash flow figures. Suffice to say it passes the broad test of 'do the figures look completely out of whack'. A ringing endorsement, I'm sure you'll agree!
Anyway, while my wording probably sounds a bit cautious, on the whole I like the business. It looks cheap, I can see why it's needed, I can't see any sort of structural decline (people still want to drive) and the factors impacting its performance seem pretty transient. The company has said it would maintain the final dividend of 3.5p, the same as last year, which would maintain the dividend yield at a whopping 9%, and it seems pretty reasonable given their cash on the balance sheet and the good cash flow position.
If it sounds like I'm holding back, then, there is just one thing which irks me slightly. In the November trading update which saw a third chopped off its price, while acknowledging the apparent transience of some of the factors, the directors also included the following statement:
Anticipating that the current economic climate is unlikely to improve significantly in the short term, management has commenced a decisive programme to reduce the cost base, including the potential closure of non-core centres, with volumes transferring to other branches.
This - at a cost of £7.7m for £1.9m of yearly savings - must surely tell us something about management feelings for the next few years. Significant savings, indeed, but I always can't help but ask - if it were so simple, why not do it before? Why are big cost saving plans always announced with bad trading updates? The obvious answer is that it's to appease the markets, but I don't want the markets to be appeased; I want the company to, if it believes the demand will be there, plough ahead with a counter-cyclical policy of investment and maintenance. Perhaps the management don't see the recovery quite as quickly as the revenue forecasts do, then.
Then again, they said they plan to maintain the dividend, and they've also noted that they believe results will be in line with the current market forecasts - those in the table above - which have already been brought down in view of the November trading update. Bullish? Bearish? Both?!
All of it leaves me a little perplexed, but maybe I'm being overly sceptical. Maybe management just saw some slack and moved to eliminate it, as all good businesses should do, in view of the fact that things are tough at the moment. Whichever narrative prevails, I think the company ends up looking pretty cheap.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
No comments yet
No one has commented here yet! Why not be the first one?