Next (NXT) - Q1 (Feb-Apr 2021) trading update - discussion

Next (LON:NXT)
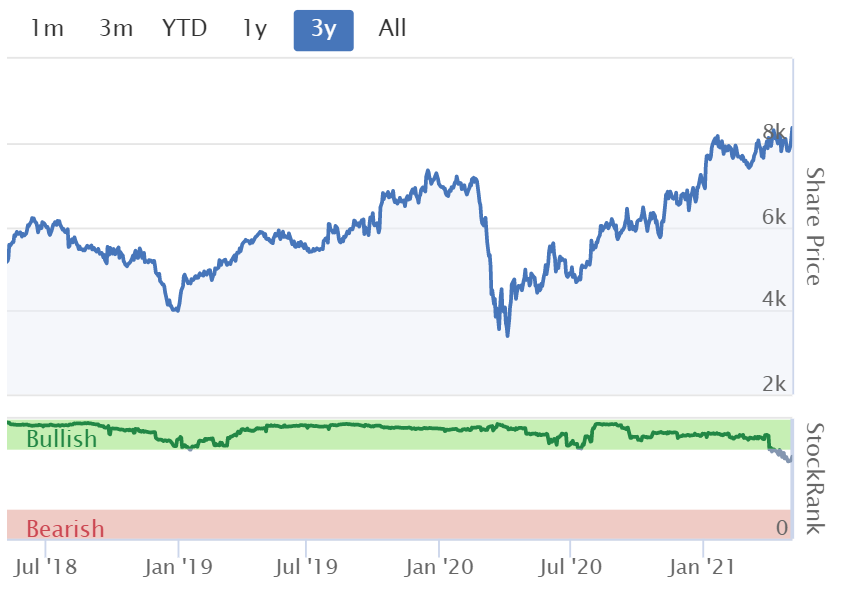
8.354p (up 3% today at 09:40) - mkt cap £11.1bn
Trading Statement for Q1 (13 weeks to 1 May 2021)
I like to check all updates from Next, as they’re the best in the business for clarity & detail, which has interesting read-across for other retailers, and the economy generally.
The headlines show that Next had a remarkably good Q1 (Feb-April 2021) -
· Full price sales in the thirteen weeks to 1 May were down -1.5% on two1 years ago. Our previous central guidance assumed that Q1 would be down -10% and we have beaten this Q1 forecast by £75m.
· We have increased our central guidance for full year profit before tax by +£20m to £720m2.
· This profit upgrade accounts for the £75m sales over-achievement in Q1. We have not raised our sales guidance for the rest of the year, which remains at +3% against two years ago.
Bear in mind that its shops were shut for most of this period! (but did have a 3 week surge on re-opening in April).
As shown in the table below, Next has once again been able to replace almost all its lost physical store sales, with increased sales online. That is a fantastic business model, and has made it so resilient during the pandemic.
Although the explanation given does paint a somewhat different picture, of a change in product mix occurring -
Overall full price product sales (excluding interest income) were only down -0.6% despite the tenweek closure of our Retail stores. The number makes it appear as if almost all the sales we lost in stores were simply transferred Online. This was not the case. In fact, very few of the Retail sales lost on adult clothing were recovered Online.
In reality, it was the growth in Online sales of NEXT Homeware, third-party brands (through LABEL) and NEXT Childrenswear, along with increasing sales Overseas, that served to make up for the sales we lost in our stores.
.

.
Why are the shares on a PER of about 18 then (cheap, arguably)? Probably because the online growth is just replacing lost sales from the stores. So over the last 6 years or so, profit has been flat overall, with a sharp V relating to the pandemic.
.

.
Re-opening - this is interesting, and reminds us not to get carried away with the pent-up demand on re-opening, which probably won’t be sustained.
Maybe we should be more cautious about the pent-up demand, re-opening trade, if Next think it’s only going to be short-lived?
Almost all of our Retail stores were closed for the first ten weeks of the quarter with the majority reopening on 12 April. The strong sales growth we have experienced in the last three weeks is due to pent-up demand built up over the last three months and is very unlikely to be indicative of demand for the rest of the year…. Evidence from last year suggests that this post lockdown surge will be short lived, and we expect sales to settle back down to our guidance levels within the next few weeks.
It’s almost as if physical stores & online are now 2 separate businesses, because the stores re-opening does not seem to have taken demand away from the online business -
In the last three weeks sales have been exceptionally strong and, versus two years ago, total full price sales were up +19%. In that period, full price sales in like-for-like Retail stores were up +2% and Online sales were up +52%.
My opinion - lots of interesting things to digest here. Thinking more generally about retailers, I think it’s becoming clear that a lot of business has probably shifted online permanently.
Whilst High Streets may have a decent bounce at the moment, Next thinks that will be short-lived. Therefore I am keeping my investments focused on retailers that have a very strong online operation, so Boohoo (LON:BOO) (I hold) obviously being online only issued stunning results yesterday, Asos (LON:ASC) (I hold) which looks more reasonably-priced than in previous times, and Joules (LON:JOUL) (I hold) which was selling over half online before covid, hence has breezed through the pandemic.
All 3 of those companies, plus Next, also have “marketplace” websites, where they sell products from other brands, for a commission. I see this as another key to future success, as we’ll probably see smaller brands disappear from High Streets and online, unless they move to selling through marketplace websites. In future then, we’ll probably have a much smaller choice of fashion websites to visit, but they will be marketplace behemoths, selling hundreds of brands.
I really should have kept my Next shares, which I held at around half the current price, it was a stupid mistake selling them, as I’ve long been aware of the quality of its business.
The takeaway from this update, is for us to not get too carried away with the short term re-opening trade. It might only defer the death of many physical retailers that have failed to crack online. Especially when business rates kick back in, and the moratorium on evictions end.
Please add your thoughts below in the comments, all views are welcome.
Regards, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
7 comments
A couple of observations about the possible views of those in the know, i.e. management about Next (LON:NXT) .
Historically the company has been a big buyer of its own shares as a means of shrinking the share base/improving eps. At the start of 2020 they had a £280m repurchase program in place of which £20m was spent before it was shelved as a means of conserving cash in the early days of COVID. So far as I’m aware there are no imminent plans to reinstate this suggesting they have better things to do (invest in the company) with any surplus capital and/or that they don’t think that the share price is especially undervalued at the moment.
Secondly, if you look at the Insider dealing record, there have only been sales (including £10 million by Lord Wolfson himself) in the past year (other than option exercises), again an indication perhaps that for those in the know the shares are maybe close to being fully valued. It’s a quality retailer no doubt, but not really a bargain at the moment. (I am a long term holder).
Gus.
I like next and my household seems to fall within their target demo for pretty much everything they sell. The house is coming down with their homewear, I'm generally clad in their shoes/chinos/ workwear many of my 1yo sons fancier outfits came from there too. My wife is possibly the only one neglected personally by their offerings as I don't believe much (if any) of her extensive inventory of clothes came from there. I suppose the draw is that it's tried and tested and their homewear stands the test of time e.g if you buy right it holds its value should want to flog it on a Facebook buy&sell group a few years down the line. The other benefit is that it has been an easy online port of call for us throughout the various lockdowns. So a great offering all around.
These combined with its profitability and strong financials are reasons why it was one of the few companies I purchased in late March last year. Knowing with a reasonable degree of certainty that it should out perform the market over time. My aim - as ever- was to buy and hold but it rebounded (quite rapidly) to a range where I couldn't see where the growth required to sustain the average PE of the 3-5 years pre Covid. E.g. I thought it was getting a bit pricey.
Looking at the metrics above I'm starting to see some justification through its low base but stellar international growth. I had previously dismissed such talk as empty given it's failure to gain much traction in the overseas in the 90s. I think it could be worth another look but ultimately it's around 50% more expensive on a PE basis than it has been and it's hard to gauge if revenue is going to break out of range posted for the last half decade. More research required.
I am not surprised by the store v online spilts. I’ve always viewed their store fair as office clothes but with online they have as much ‘space’ as they like to offer broader fair. People have been buying for home over the last year so a different type of product that Next have been able to cater for. Well done them. I’ve never had Next shares but clearly they are extremely well run with flexible management- I think their years of catalogue business experience is at the foundation of this. I just can’t get past that I hate their clothes, horrid material mostly- and frumpy but that’s my loss.
Do you think could Associated British Foods (Primark) could be an exception to the rule that bricks and mortar retailers are doomed to fail? (I realise that ABF has other businesses besides Primark).
Paul
I really should have kept my Next shares, which I held at around half the current price, it was a stupid mistake selling them, as I’ve long been aware of the quality of its business.
I know the feeling I made same mistake back during the 1st lockdown when they announced problems with their warehouse operation and threats from the workforce to 'down tools' due to potential Covid 19 exposure. However, as always with Next (LON:NXT) they had everything under control and the share price has doubled since my sale. Given the quality of their reporting which makes all other retailers look complete amateurs I really should have stayed invested as it is clearly a quality company. I have been waiting and hoping for a pull back so I can get back into the shares but they just keep on powering ahead and now look fully priced. As I have said in today's SCVR comments with regard to Somero Enterprises Inc (LON:SOM) a 'buy and hold' strategy would have served me much better than reacting (albeit only occasionally) to short term news flow. On the plus side it is good to know that someone with your expertise in the retail sector can make the same mistake as a an amateur like myself!!
Just to muddy the waters a bit I note that Superdry (LON:SDRY) has reported encouraging trading and 'light at the end of the tunnel'. Maybe the trade is about people spending again rather than purely a black and white story about ecommerce being good, and High St bad. Obviously Super has been trying to increase it's online presence and has a big new shiny management team in situ. Probably more upside to come?
Hi hayashi22,
I'm just starting to review Superdry (LON:SDRY) now, for today's SCVR.
Regards, Paul.