Norcros - construction recovery provides positive backdrop

Small companies are often not lacking in ambition and this is certainly the case for building products company Norcros. The group is looking to lift sales to £420m by 2018 from the £222m seen in the year to March 2015. Recent trading has been mixed and so the key will be to successfully complete and integrate acquisitions.
Norcros listed on the London Stock Exchange at 78p in July 2007 and had a market value of £116m. Less than two years later the shares had fallen to 4p as the economic slowdown hit demand.
Norcros boasted when it made its IPO that Triton showers had the leading position in the UK domestic shower market and Johnston Tiles is the UK’s top tile maker. The group’s South African business also offered exposure to a long-term growth market.
Triton Showers & Johnston Tiles
Source: Norcros website
Clearly the IPO story was overhyped with the downturn hitting demand for construction related products. In July 2009 the group announced an open offer at 7p a share, in order to reduce debt, with the shares issued 74.2% of the enlarged share capital.
This is hardly the most impressive backdrop for a listed company but Norcros now appears to be on the mend. Revenue in the year to March 2015 rose by 1.5% on a reported basis and 5% on a constant currency basis.
Norcros also bought Vado - a maker of taps, showers and accessories – in April 2013 for an initial payment of £11.9m and further payments of up to £4.1m. In June 2015 the group announced the purchase of Croydex for £21.9m.
Croydex appears to have a similar business to Vado in that it makes “high quality bathroom furnishing and accessories.” Both takeovers have been funded using existing resources and debt and as such will lift earnings.
Against this mixed backdrop the shares trade on a forecast of 9.5X earnings for the year to March 2016 which falls to 8.5X in the following year. The focus on revenue growth and acquisitions offers potential upside but also increases the company’s risk profile.
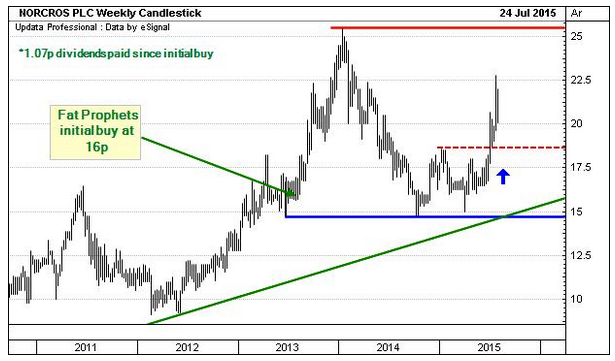
Norcros today
Norcros is a £125m market value company which generates two-thirds of its revenue from the UK and a third from South Africa. The largest division is Johnson Tiles UK and the second largest revenue generator is Triton showers.
The other UK divisions are Vado bathroom products and then the Adhesives division which sells Norcros Adhesives. In South Africa the largest revenue generator is the tile retailer Tile Africa followed by adhesives business TAL and then Johnson Tiles.
Norcros revenue breakdown in year to March 2015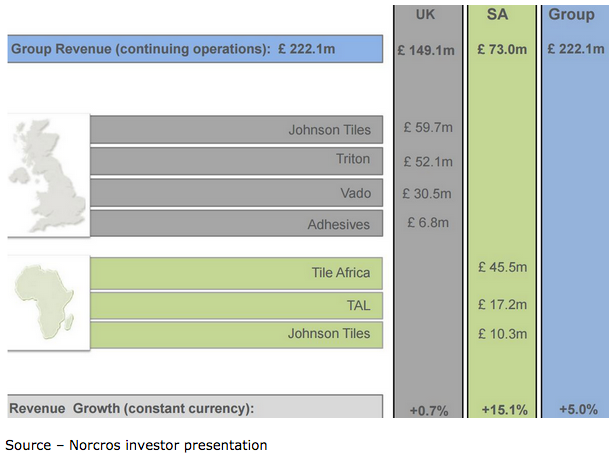
Despite the strong backdrop for UK construction the group saw only 0.7% revenue growth in the UK in the year to March 2015. The South African business, by contrast, saw 15.1% constant currency revenue growth.
The weak top-line performance in the UK is one reason that the share price has remained subdued. The contribution from the growth in South Africa has also been limited by weakness in the South African rand.
The net result is that while constant currency revenue was up 5% in the year to March 2015 the reported change was up only 1.5%. The UK’s weak performance is blamed on “limited improvements in the retail sector impacted by sluggish consumer confidence.”
This is surprising given the economic recovery in the UK and return to real wage growth in 2015. Another explanation may be that the group’s divisions may be in mature markets or struggling against the competition.
Norcros’ strategic focus
In terms of the strategic plan that Norcros unveiled in Mach 2013 and the revenue growth target is ambitious. Revenue of £222m in the year to March 2015 is targeted to increase to £420m by 2018.
The acquisition of Croydex adds around £20m of revenue and the plan is for acquisitions to add £90m-£145m of revenue in the period. This still leaves at least £53m of revenue to come from organic growth by 2018 which, in our view, looks like a tall order.
Norcros targets set in March 2013
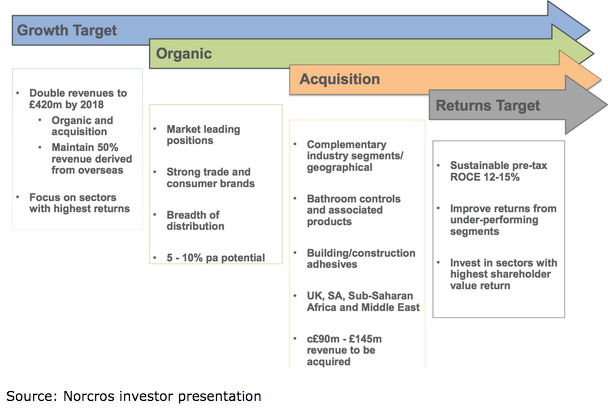
The target for the return on capital is 12-15% and in the year to March 2015 the group achieved an underlying return on capital of 16.3%. Acquisitions may decrease or increase this return with the price paid being paid the key factor.
Norcros also has a pension deficit and is contributing £2.1m into the scheme as part of the recovery plan. At March 2014 the gross deficit came in at £44.3m versus £21.8m last year due to a lower discount rate at 3.3% versus 4.3% last year.
At March 2015 net debt was £14.2m which compares to £26.9m at the start of the year and reflects a number of asset sales. The acquisition of Croydex for an initial £21.9m will serve to increase debt in the current year.
Summary and valuation
Norcros has clearly been a frustrating story for investors both in terms of the initial IPO and recent trading. The shares appear inexpensive on 9.5X forecast earnings for the current year but the acquisition-led strategy increases the risk profile.
Vado has performed well since Norcros bought it in 2013 and the building products industry has a host of small suppliers. This should put Norcros in a strong position to consolidate the sector.
The construction recovery in the UK also provides a positive backdrop even if the retail trade remains subdued. In our view, Norcros does merit investor consideration given that further earnings enhancing acquisitions should be in the works.
The group has all the risks associated with small companies and is also exposed to a meaningful pension liability. As such the ambitious revenue growth target means that the shares merit a medium to high-risk rating.
This report was produced by Fat Prophets Senior Analyst, Andrew Latto.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
2 comments
rhombold1 - Interesting points. Agree the signal of the CEO exercising the options and selling them all is negative. As I recall options are meant to allow management to build a long-term stake. In the case of the CEO he appears to be using them to supplement his annual income.
We can say that the reasons for large director buys is usually clear in that they think the shares offer value. In the case of director sales the reasons are less clear as it could be for personal financial needs or diversification.
However, the eagerness of the CEO and the Finance Director to cash in options here is disappointing. Especially the case with the CEO. If the CEO doesn't believe in the company's long-term future the board should appoint someone else!!!!
http://www.investegate.co.uk/norcros-plc--nxr-/rns/directors--dealings/201507291746134939U/
The CEO has just exercised 2.5 m nil options and sold the lot, the FD retained c. 30 per cent.
I'd be interested to know why as the signal it sends is at best neutral