NTD: The wheels keep turning

National Tyre & Wheel (ASX:NTD) are a distributor of tyres and wheels. They are the largest independent importer and wholesale distributor of tyres and wheels in Australia and NZ. They also have a presence in South Africa.
They are primarily a wholesaler but also have a chain of retail stores under the Tyreright brand. Primarily the business services commercial vehicles such as trucks and buses as well as agricultural vehicles and four wheel drives.
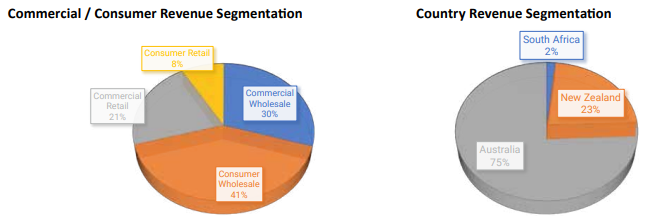
Source: National Tyre and Wheel, Annual Report 2023, 18/9/23
NTD have experienced strong revenue growth over the last five years. In addition to organic growth, a lot of the revenue growth has come via acquisitions. The acquisition of Tyres4U in August 2020 was a transformative transaction resulting in revenue increasing from $160 million to $460 million. They made a couple of smaller acquisitions in 2021, including Black Rubber, a truck tyre business and Access Alloys. In late September this 2023, they announced a deal to distribute Dunlop tyres in Australia and New Zealand. The deal is expected to be exclusive and they have the right to exit it if another distributor is appointed. The expected impact on revenue is an additional $118 million per year which is a significant jump from the current level of $583 million.
Whilst revenue has been growing strongly, and with this latest distribution agreement, should continue to do so, the path of profits has been a bumpy ride. EPS was $0.17 in 2021 but declined to $0.024 in 2023. Profits were impacted by substantial increases in cost of goods and freight and a disorderly supply chain. In the second half, supplier prices declined, as did international freight prices and the supply chain was more stable. Consequently, the second half of 2023 was much more profitable than the first half. Gross margin increased by 2% from the first half to the second.
The balance sheet remains strong. Net debt to equity is 112%, but this is inclusive of capital leases. The tangible assets to equity ratio, a measure of leverage which forms a component of the Health Trend, declined over the last year. Cash flow also improved over the last year and operating cash flow per share is well above EPS and has been consistently. That is a good sign of the health of a business.
Given the reduced profitability of FY23, NTD did not pay out a dividend. This will help conserve cash to manage the debt profile. In the past they have paid healthy dividends and anticipate doing so again in the future once profitability returns to a satisfactory level.
They are now starting to build up a stronger competitive position. Whilst tyres are a fairly generic product, competitive advantages can be built through relationships with suppliers, relationships with customers, greater efficiency through scale and the ability to focus more intently on specific segments, again as a function of scale.
Despite the challenges of the last couple of years, the business appears to be well positioned to grow profits over the coming years. In their outlook, management acknowledges that the consumer business is likely to face continued pressure due to the macroeconomic environment, however they are more optimistic about commercial demand. They have made a shift towards lower volume but higher margin business. Overall they are expecting a better result in FY24 than what was achieved in FY23.
This turn around in the second half along with the Dunlop deal has led to a rerating of the share price. It has risen about 60% since June as investors believe they have turned the corner on profitability. This underlies the strong Momentum score of 96.

Despite this very strong momentum, the Value score is also high at 87 having increased by 10 in the last month. As shown in the table below, when compared with the industry and market averages, the value metrics are strong. Analysts are forecasting a strong rebound in earnings and against this the forward PE ratio is quite low. Likewise with dividends, EBITDA and cash flow. The balance sheet value measures are also low.

National Tyre and Wheel is only a small company with a market capitalisation of $105 million. The founders maintain significant shareholdings and are active in the business. Over half the shares outstanding are held by strategic investors. These factors contribute to the stock trading at a discounted valuation. In addition, operating margins are low. Whilst they should improve, even in 2021 they only reached 6.9%. The nature of the business is high volume and low margin.
This is a mundane business that has carved out a niche and is executing very well. With the potential for further margin improvement, strong demand from the commercial vehicle market and ongoing strength in the new and used vehicle markets, combined with a modest valuation, the wheels of good fortune may continue to turn for investors in NTD.
Important Information: Stockopedia Ltd ABN 39 757 874 670 UK business registration number 0637267 (“Stockopedia”) is an Authorised Representative of Daylight Financial Group Pty Ltd ABN 77 633 984 773 (“DFGPL”) which is the holder of an Australian Financial Services Licence (AFS Licence No. 521404).
Information in this commentary is current as at date prepared unless otherwise stated. However, please bear in mind that investments can go up or down in value, and that past performance is not a reliable indicator of future performance. For more Important Information please refer to the Disclaimer section of this website.
This communication may contain general financial product advice. It has been prepared without taking into account your personal circumstances, and you should therefore consider its appropriateness in light of your objectives, financial circumstances and needs before acting on it.
If our advice relates to the acquisition or possible acquisition of a particular financial product, you should obtain a copy of and consider the Product Disclosure Statement (PDS) before making any decision.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
1 comment
But it’s a grubby, dog eat dog industry, Chris, with little competitive moat. Price is the major decision maker in the minds of customers or in tougher times, travel less and trade down to cheaper tyre selections. NTD is somewhat fortunate of its position in a fragmented market where mum and dad businesses will/are failing first. Yes, the commercial thrust v retail is definitely an advantage, but one wonders whether NTD is taking full advantage of its market positioning. Afterall, it isn’t a uniform brand, merely a roll up or collection of businesses trading under their own names, it’s a silo business and I very much doubt whether they are cross selling as they could. Take Bob Jane…everyone knows them and what they do, not the same for NTAW with 12 individual brands. Plus, their disaster with an ERP roll out costing $4m wasn’t a ringing endorsement for management. Whilst I hold, and I do believe there is room to improve from FY23, I think one needs to watch managements performance to see if they can take it forward whilst juggling import pricing, AUD, wages explosions and a competition hell bent on lowering prices to get business. I just don’t think they are quality as represented by the Stockopedia rating of 87. That said, I certainly appreciate your article and point of view. They make me review my reason for holding.