OCL: Another AI hot stock?

Technology stocks on the ASX have been on a tear, with the S&P/ASX All Technology Index having produced a total return over the last 12 months of 62.6%. A technology stock that tends to fly beneath the headlines is Objective (ASX:OCL). Maybe that is because it has underperformed the index with a total 12 month return of a mere 56.7%.
Or maybe it is due to the nature of the business. They provide solutions for public sector organisations and regulated industries. How boring is that? Surely that can’t be a growth industry?
It is also a very tightly held stock.
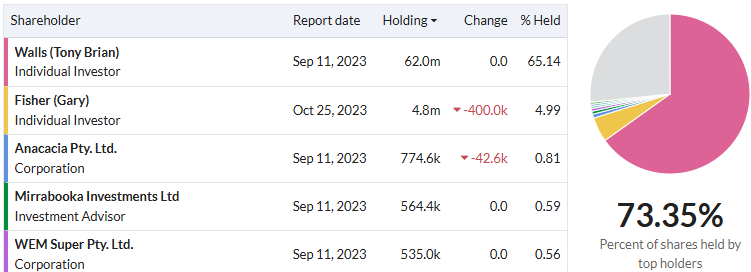
Tony Wells is the founder, Chairman and CEO and holds 65% of the stock. Gary Fisher, who was a director from 1991 to 2023 holds a further 5%. The total market capitalization is $1.65 billion, so this leaves a free float of approximately $500 million. Still a substantial amount when compared to other small cap stocks. There has been an average daily traded value of $860k over the last year.
Objective is not a new start up with a hot idea surrounded by a lot of marketing hype and buzz words. They were founded 37 years ago and have been listed on the ASX for over 25 years. Their key target markets include governments, councils, regulators and local planning authorities. They break out their revenue according to three main product lines:
Financial year 2024
Content solutions | $80.3m | 68% |
Regulatory solutions | $22.2m | 19% |
Planning and building | $12.3m | 10% |
Public sector organisations are subject to increasing public expectation that they will offer efficient digital solutions. Objective are helping these businesses to go completely digital.
In terms of their own business model, they have now transitioned themselves to a subscription only software business. 81% of their revenue is recurring and they have low churn rates. Software as a service (SaaS) businesses like to measure their annual recurring revenue (ARR). Objective have now passed ARR of $100 million. Their total ARR grew by 11% in FY24 and their SaaS ARR grew by 15%. They were targeting total ARR growth of 15% but fell short due to the late deferral of several material opportunities. Also, soft economic conditions in NZ led to soft building consents in NZ where they have a pure transaction based revenue model. They remain committed to the 15% total ARR growth goal.
Despite their long history, and arguably staid customer base, Objective is still a growth business. Revenue has grown at a CAGR of 14% over the last 5 years and SaaS growth has been especially strong at 31%.

Source: Objective, Investor Presentation FY24 Financial Results, 22/8/24
In addition to organic growth, they also seek growth through acquisitions, however the frothy state of the market meant they didn't close a single M&A deal in FY24. They investigated a significant number across US, UK and Australia and conducted detailed due diligence on several but did not get a deal over the line. In the end, competition from competing parties pushed prices to the point where it did not make economic sense, so they maintained their disciplined investment approach and walked away. They have $96 million in cash and no financial debt so they are in a strong position should the right opportunity arise.
This leads us into the Stockopedia rankings underpinned by the very high Quality Score of 99. In addition to the solid balance sheet, they have a Piotroski score of 8 out of 9 and their ROE is 38%. Their operating margins are 33% having grown from 17% five years ago.

This is another case of a high quality compounding business that has not just hopped on the AI bandwagon last week, but rather has been steadily building a growing business for decades. (They are also deploying AI quite heavily in their software solutions as well as R&D.) I have written previously about stocks that meet the criteria for the Quality Compounder screen as presented by Stockopedia contributor Roland Head in his article Building a screen to find Compounding Quality stocks. There are currently 19 ASX stocks that meet this screen and Objective is one of them as shown in the table below.
Criteria | Threshold | OCL |
QualityRank | 80 | 99 |
Long-term ROCE | 18% | 31.2% |
TTM ROCE | 15% | 36.6% |
Operating margin 5 yr avg | 10% | 23.1% |
Operating margin TTM | 10% | 32.7% |
Net margin 5 yr avg | 8% | 19.4% |
Net margin TTM | 8% | 26.7% |
OCF / EPS | 0.8 | 1.8 |
Avg FCF (long term) / Assets | 8% | 21.7% |
Sales CAGR 5 yr | 0% | 13.6% |
Sales TTM / Sales Prior TTM | 5% | 6.4% |
Debt to assets | <50% | 7.8% |
Interest cover | 10x | Net interest is positive |
The Momentum Score is also high at 75 on the back of the share price performance, but as is often the case with these stocks, the Value Score is very low at 8. Price to Sales is 14 times and the PE ratio is 48.
Objective is clearly a well run, founder led business. The question will be can it continue to grow at a sufficient rate to justify the high valuation. They are currently aiming to expand the addressable market that each of their core solutions targets. They are a global business but 88% of revenue comes from Australia and New Zealand with most of the remainder coming from the UK. That leaves a lot of scope to target public sector and regulated entities in other jurisdictions, leveraging off their expertise in this segment.
They may even find an M&A target they can acquire…
Important Information: Stockopedia Ltd ABN 39 757 874 670 UK business registration number 0637267 (“Stockopedia”) is an Authorised Representative of Daylight Financial Group Pty Ltd ABN 77 633 984 773 (“DFGPL”) which is the holder of an Australian Financial Services Licence (AFS Licence No. 521404).
Information in this commentary is current as at date prepared unless otherwise stated. However, please bear in mind that investments can go up or down in value, and that past performance is not a reliable indicator of future performance. For more Important Information please refer to the Disclaimer section of this website.
This communication may contain general financial product advice. It has been prepared without taking into account your personal circumstances, and you should therefore consider its appropriateness in light of your objectives, financial circumstances and needs before acting on it.
If our advice relates to the acquisition or possible acquisition of a particular financial product, you should obtain a copy of and consider the Product Disclosure Statement (PDS) before making any decision.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
No comments yet
No one has commented here yet! Why not be the first one?