On the multi-bagger hunt: 3 portfolio ideas

This week at Stockopedia we have focused our attention on the growth style of investing - a strategy which benefits from the combined market forces of quality and momentum. I have written an introduction to the strategy, describing how it works and which successful investors you can learn from when trying to replicate the style. Mark has crunched the data to assess the optimum holding periods and portfolio sizes when pursuing this strategy. And I have taken a look back at recent multi-baggers in an attempt to uncover any shared qualities in the companies which multiply for their investors.
And now, we have come to the final article in the series - the one which Ed insists is the one you’ve all been waiting for - five potential future multi-baggers, growth stocks which return more than 100% for their shareholders.
It goes without saying that ‘potential’ is a key word here. I don’t have a crystal ball or a time machine and don’t know what will happen to these companies in the coming years. The shares presented in the article below are, for now, simply ideas. I have not committed to buying any of them myself as I want to spend a bit more time researching them, I would suggest that any readers who are interested by the selection do the same.
First Principles: Building a long list of multi-baggers
Before we dig into the good stuff, I thought it was worth running you through my process so far in my quest for a potential multi-bagger.
First, I made a screen based on the previous research I had done into identifying multi-baggers and the insights from guru investors and experts. I was attempting to narrow the field of stocks to only those which exhibit the characteristics which previous successful stocks showed at the start of their journey to multi-bagger status. The rules I used were:
- Market Cap: £20m to £1bn
- Geography: Western Europe, UK, Australia, US and Canada
- Sector: Not energy or financials
- Growth: Sales and EPS growth in the last 12 months greater than 10%
- Quality: Operating margins and ROCE greater than 15%
- Room for multiple expansion: PE less than 20
You can see all the results from the screen here. I have kept the criteria deliberately loose in an attempt to try and scoop up as many exciting stocks as possible (with the view to doing further research).
Secondly, I scanned Stockopedia’s guru screens for ideas. Bill O’Neil’s CANSLIM screen (which has generated excellent results in the US) provided me with a number of ideas for stateside stocks. While Jim Slater’s Zulu Principle screen (which has had less success across the pond but has thrived in Europe) provided a number of ideas.
The third screen I put together looked specifically at AIM. London’s junior market has come in for its fair share of flack in recent months, but I continue to believe that there are some exciting businesses here, just waiting to be discovered. I screened for:
- Sales Growth: A 3yr CAGR of 10% and trailing 12 months growth of 15%
- Quality: Operating margins of at least 10%
- Market Cap: Greater than £10m
Again, my screen was deliberately loose - intended to provide me with a selection of stocks for further research. You can see all the results here.
The fourth part of my stock selection process was slightly more time consuming. Based on my own research (and that of growth investing experts), it appears that stocks which go onto become multi-baggers have two key characteristics: first, they operate in a growing market; and second, the have a business moat which protects them from competition. I examined the outcomes of my screens in an attempt to identify stocks which fulfil these characteristics and then compiled a shortlist of companies from which to do further research. You can access that full shortlist here.
Next steps: Multi-Bagger opportunities
Armed with my shortlist, Stockopedia’s StockReports and Google I then set about delving into the companies which could be primed for massive growth. The result: three interesting stocks, operating in three different sectors in three different countries which look promising and I am keen to explore further.
- Healthcare opportunities in the UK and Europe
Companies which are aiming to solve the world’s health problems by producing exciting new medicines sound like they could be multi-bagger opportunities. The truth is that commercialising new medicines is extremely difficult and is often a job better left to the pharmaceutical giants. Where small companies thrive is in their ability to produce technologies which improve medical outcomes.
There are four of these companies on my multi-bagger watchlist. Eurofins-Cerep is a French pharmaceutical services company which aims to help its customers screen for promising new drug candidates. In Germany, MeVis Medical Solutions is helping to speed up cancer diagnostics with a suite of specialised software designed to detect disease from medical imaging. And Ergomed provides specialist services to the pharma industry, helping large customers optimise their clinical trials and small customers meet regulatory obligations.
But the stock that has piqued my interest the most is Proteome Sciences. This micro-cap has been listed since 2003 and has spent most of its time on AIM as a perpetual under performer - reliant on loans and equity top-ups. Indeed, Vulpes Investment Management (a hedge fund known for profiting from volatility) is the largest investor, accounting for 23% of the shareholder register. It should be noted that with such a large single investor, the stock is highly illiquid and its wide spread might make it quite difficult to buy.
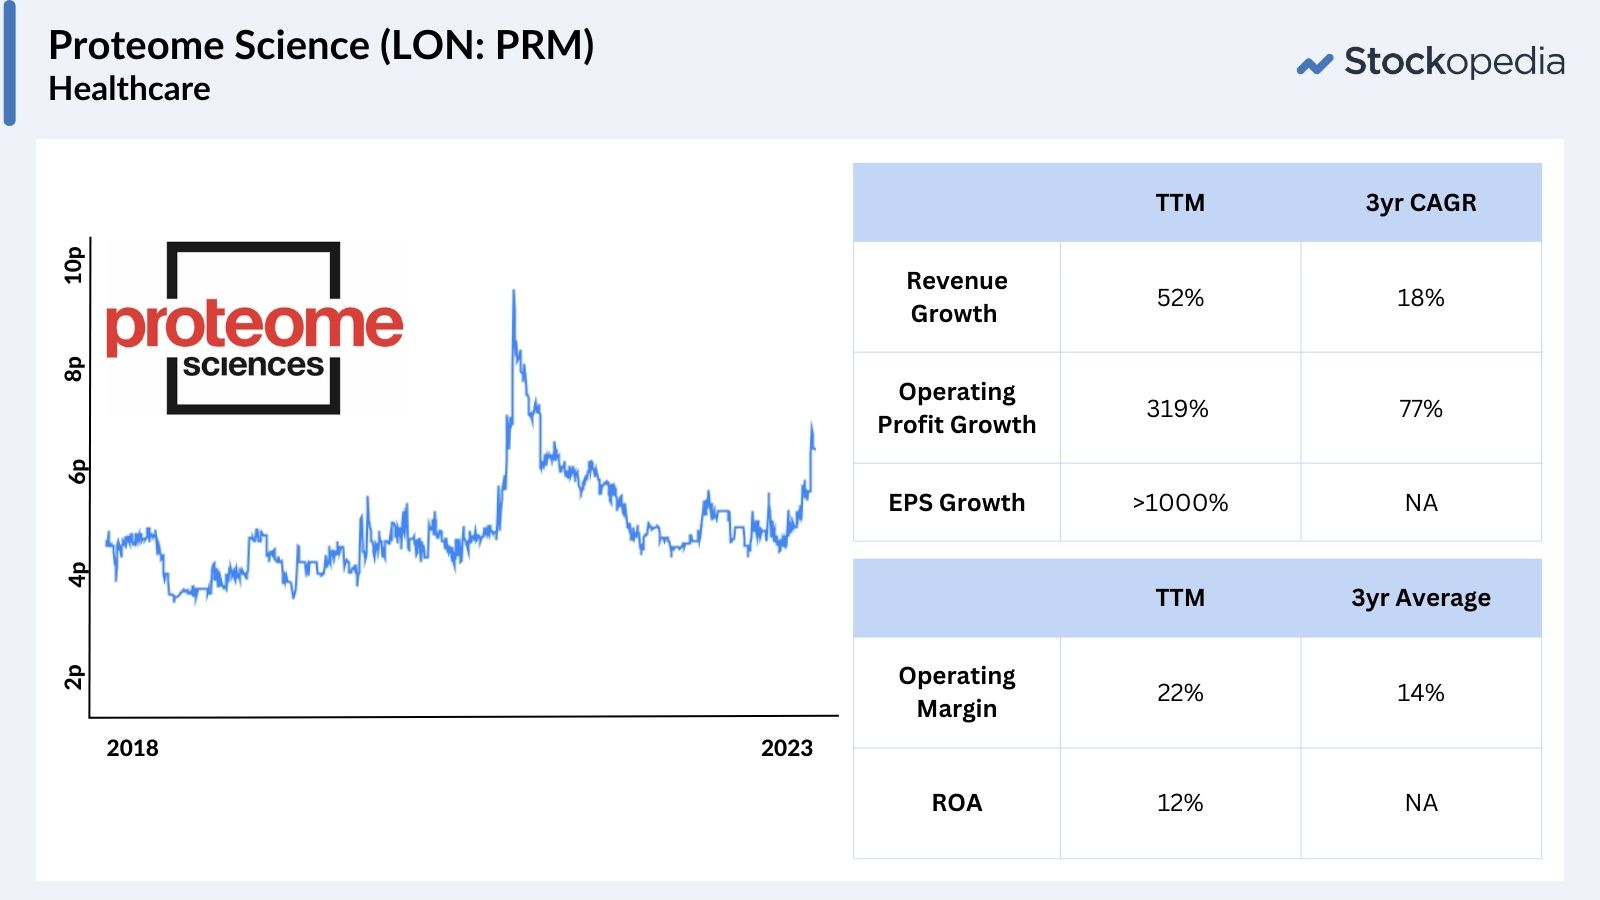
But Proteome seems to have put its loss-making, cash guzzling days behind it. In the last five years, revenue generated through its supply agreement with Thermo Fisher Scientific has risen at a compound annual rate of 18%. Operating margins are widening and, as of 2019, the company has generated positive earnings.
And the market dynamics appear to be in the company’s favour. Proteome produces biomarkers which can be used to detect proteins in biological samples. These are important in drug discovery and diagnostics as medicines are becoming increasingly personalised - more specific biological analysis (the type which Proteome’s products can achieve) is increasingly important. Indeed, the market for proteomics is forecast to grow at a compound annual rate of 13.5% between 2022 and 2030. Proteome Sciences seems to be priming itself for that expansion with the recent opening of a laboratory in the US.
With a relatively new chief executive and chief commercial officer at the helm, Proteome looks like an interesting stock for multi-bagger hunters. There is more I need to understand about the company’s position in the rapidly expanding Proteome market before I am ready to invest, but have reached out to management for more information and will keep you posted.
- US businesses ready to advance in new growth markets
Bill O’Neil’s CANSLIM screen for identifying stocks doesn’t place an upper limit on company size. Some of the US stocks which have emerged from the screen and therefore already well established businesses.
The screen has also produced some interesting stocks which have already multi-bagged and could be part the way through their upward march. Napco Securities is one of them, whose locks and alarm systems have been in high enough demand to send the company’s sales up at a compound annual rate of 10% in the last fives years. Then there is UFP Technologies, a custom manufacturer of plastics and packaging, specialising in the medical market. And finally Deere & Co, the agriculture business best known for its tractors and combine harvesters.
It is the last of those three which I have decided to take a closer look at because of the pace of change in the wider agriculture market and the company’s dominant position in it. Demand for sustainable farming has risen dramatically in recent years and will continue to do so, with an expanding population who are increasingly environmentally aware. John Deere has kept ahead of the competition with its ability to innovate. It sells equipment which is powered by renewable energy and has built AI models which can help automate some farming processes. The company’s technology and machinery are also used in construction and forestry which are undergoing similar upward shifts in demand.
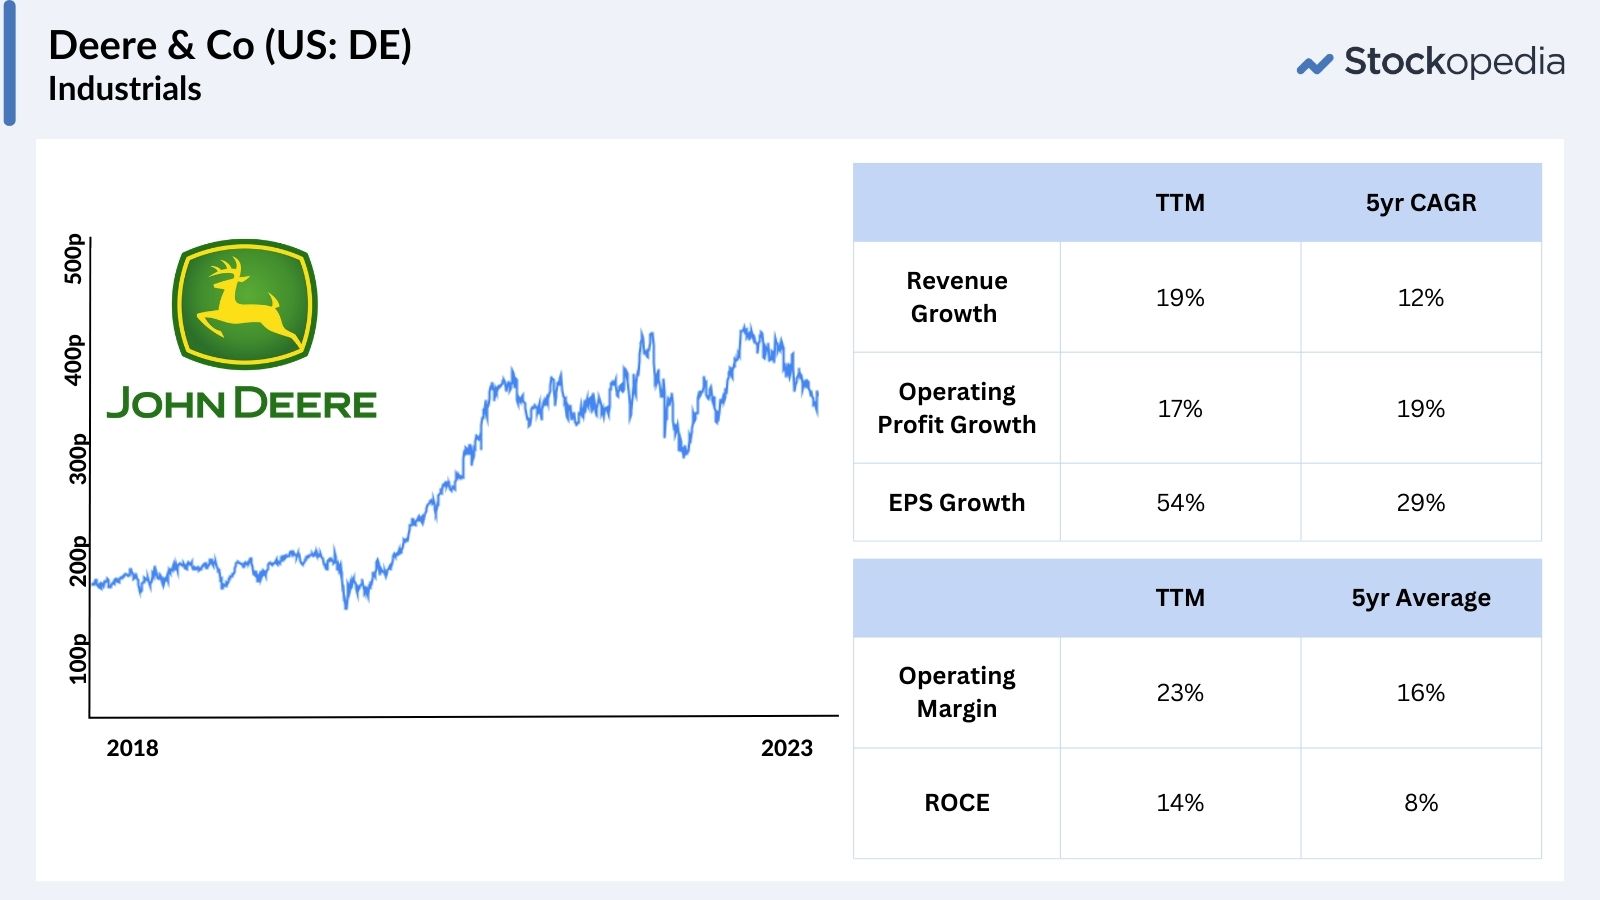
Company sales have risen from $37.4bn in 2018 to $52.2bn last year - a compound annual rate of growth of 7%. More significant has been the widening of operating margins, as the company has sold more tech-enabled equipment. Earnings per share have more than doubled over the last five years.
Now with a market capitalisation just shy of $100bn - equivalent to almost two times last years sales - it’s right to question whether the John Deere growth train has come to an end and whether the company can continue delivering for shareholders. But with its market leading position in a growing market, the company should be able to sustain sales and earnings momentum. And there is plenty of room for multiple expansion (another key pre-requisite of a growth stock) in a company with a price to earnings ratio of 13.
- Tech-sector opportunities
In the last few years, the tech sector has delivered more than its fair share of multi-baggers*.* Scanning through my shortlist doesn’t flag a huge number of UK tech stocks, but the most prominent tech-based sub-sector seems to be gaming.
The UK’s video game design and development market has thrived in recent years with many new businesses coming to market. But a similar number he been bought out of the market - sometimes before shareholders have enjoyed the full scope of share price appreciation.
I like the look of Gaming Realms (which is actually a B2B business, but does own consumer facing brands). Having turned its first profits in 2021, the company seems to have set itself on a growth path - in the first two months of 2023, revenues had risen 53% on the same period of the previous year. The company licences real money games in regulated online gambling markets. With a rising number of markets emerging and continued investment in its own intellectual property, Gaming Realms looks well placed.
Team17 is another interesting stock which has been a favourite among AIM investors since the company’s IPO in 2018. Sales have risen from £43m at the end of that financial year to £137m in the last set of financial results.
But its in Sweden (which punches well above its weight in my multi-bagger watchlist) where I have found my most promising tech stock. Prevas is a tech consultancy firm, built through a range of acquisitions which included acquiring the company which brought in the new chief executive. At its heart, Prevas is an engineering business which attempts to provide specialist technological solutions for its roster of global customers. The market for tech outsourcing and co-development is growing and Prevas is benefiting from that, revenues have risen at a compound annual rate of 12% over the last five years and margins have widened. The company is also now generating a very impressive return on capital employed (25% in the last 12 months, compared to under 10% just five years ago).
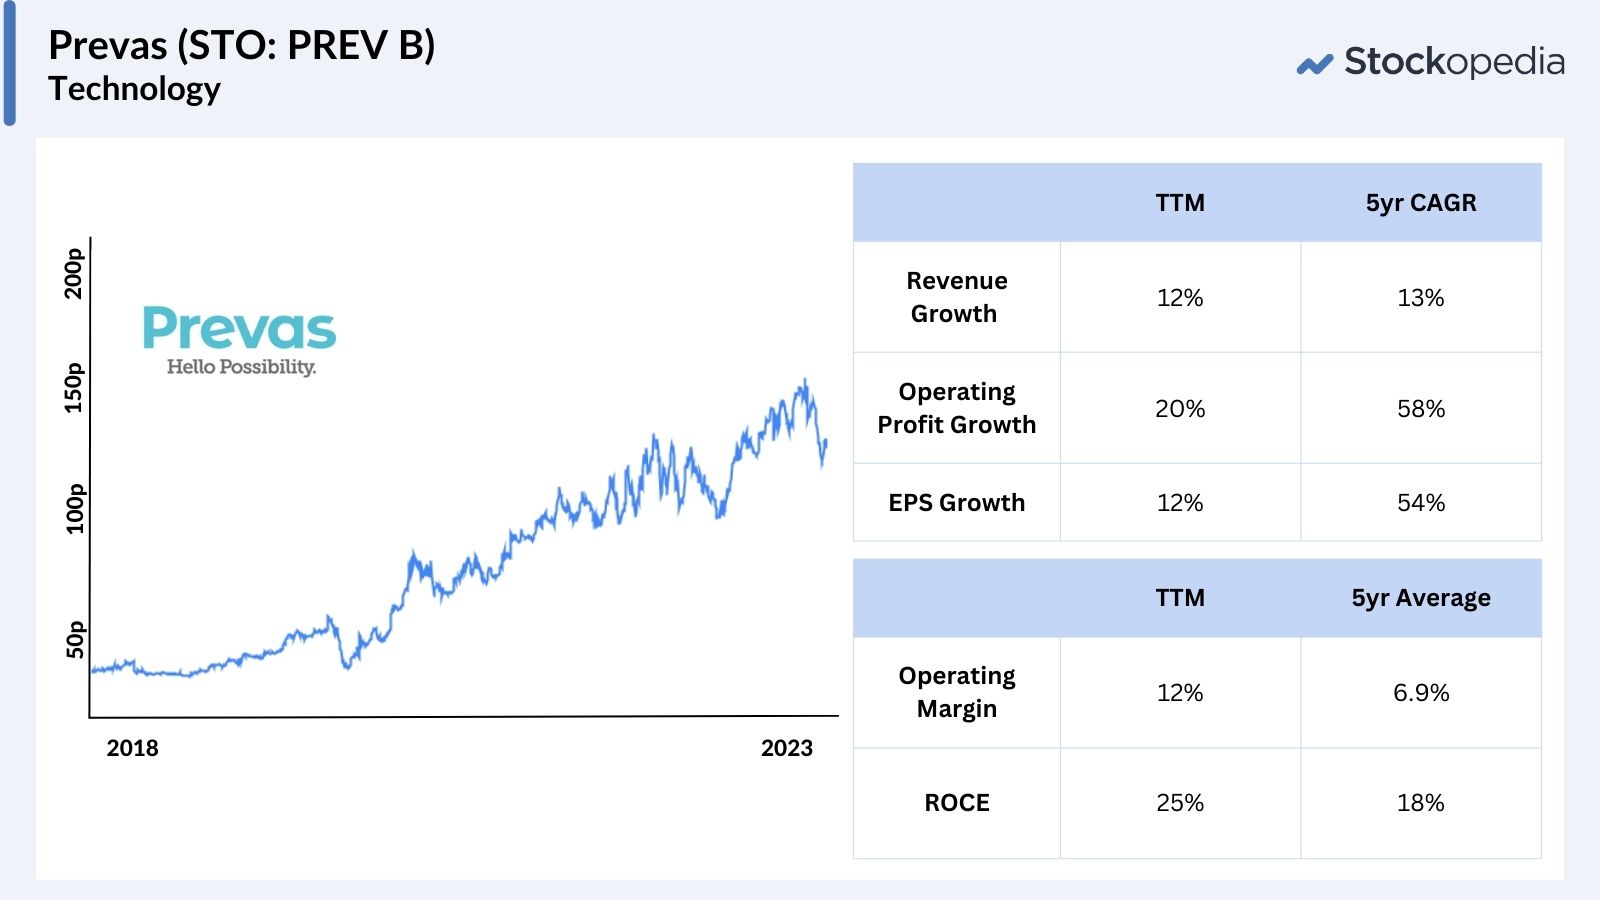
It is worth being wary of the company’s lack of clear protective moat - other consultancy firms can do what Prevas does. But with its strong customer base and rising demand, I am intrigued by the potential here under a new (very enthusiastic) chief executive.
So what next? I am going to keep researching my three highest conviction ideas until I’m confident enough to add them to my adventurous growth portfolio. I’m also keen to hear from the community about any stocks that they’re interested in with big growth potential. Let me know in the comments if there is anything you have got your eye on.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

5 comments
Hi, maybe its just me, but the You can access that full shortlist here link doesn't seem to work. Thanks
Sosandar (LON:SOS) for me. Recently moved in to profit. Successful launch on other market place sites (Sainsbury, M&S, John Lewis etc). Now talking about growth into other countries. Could be a good growth stock long term
I am looking at NET Power (NYQ:NPWR) as a possible multi bagger . It’s quote on NYQ is very recent so financials are virtually non existent .It has some heavy hitter Oil & Gas investors including Baker Hughes Co (NSQ:BKR) .
“NET Power is a clean energy technology company with a mission to globally deliver the “Energy Trifecta”: clean, reliable, and low-cost energy. We invent, develop and intend to license technology that provides reliable, on-demand natural gas power with life cycle emissions that are 90 percent below today’s combined cycle natural gas systems and in line with renewables coupled with batteries. Our technology also delivers a levelized cost of energy that is below both combined cycle gas turbines with carbon capture and renewables coupled with batteries. Founded in 2010 and headquartered in Durham, North Carolina, NET Power has received strategic investments from key industry partners including Occidental, Baker Hughes, Constellation and 8 Rivers.”
“NET Power’s technology is simple:
it makes clean, reliable, low-cost energy.
We figured out how to make the problem (CO2) part of the solution through a crucial innovation. Unlike existing technologies, the NET Power Cycle is closed to the environment.
“NET Power works by combusting natural gas with pure oxygen in a combustor, producing CO2 and water. We mix this with recirculated CO2 and use it to spin a turboexpander, producing power. When the turboexpander exhaust cools, water and byproducts are removed.
What remains is CO2. Most of the CO2 is compressed and recirculated back to the turboexpander while a small portion exits the cycle, like a slowly overflowing bucket, and is captured. The captured high purity CO2 can be easily sequestered or sold to industry. Nearly all CO2 is ultimately captured through the process.”
Their business model is to licence out their intellectual property and there are now several early stage full scale projects going ahead. One of these is on Teeside.
It’s not one for those of a nervous disposition!
Re NET Power (NYQ:NPWR) : It perhaps worth mentioning that the power plants are utility scale around 300 megawatts as a base load but able to peak up to about 370 megawatts. This is around the size of the new generation SMR ‘s such as Rolls Royce’s proposal.
Hello Megan, I'm struggling to understand why you picked Proteome Sciences (LON:PRM), when it fails on 3 counts, to qualify for your screen.