Paragon banks on UK buy-to-let lending

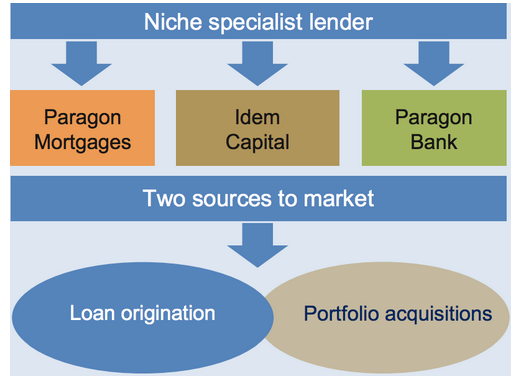
Paragon Group is a UK consumer finance business where the main focus is providing buy-to-let mortgages. The two other divisions are Idem Capital, which buys consumer debt, and the recently launched Paragon Bank. During the global financial crisis Paragon suffered from a liquidity crisis but the underlying asset portfolio was resilient.
Residential buy-to-let investments are popular in the UK and are likely to remain so with the introduction of new pension freedoms in April 2015. These allow pension savers to withdraw their assets when they had previously been forced to buy annuities.
Even before this change the buy-to-let mortgage market in the UK has been seeing a rapid recovery. This is perhaps not surprising given the strong performance of residential property and the imbalance of supply and demand for housing.
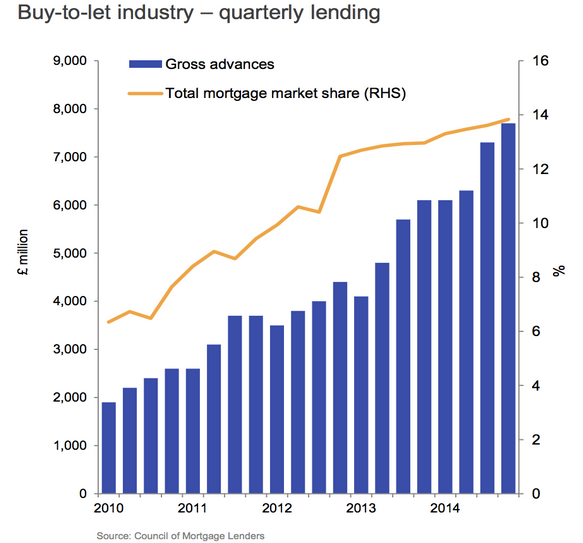
Source: Paragon Group investor presentation
In the 18 years from 1996 – the year UK buy-to-let mortgages were introduced – an initial £1,000 invested in buy-to-let would have risen to £13,000. This reflects the assumed loan to value ratio of 75% and the performance of residential property values.
In the same period a cash buyer of property would have seen their initial investment rise to £4,791 and equities would be worth £3,082. The appeal of buy-to-let residential investment is clear although future house price gains are set to be more modest.
Paragon Group provides buy-to-let mortgages and is currently benefiting from the rapid growth in demand. The company is the only specialist lender to have an independent position in the UK mortgage market.
People who make buy-to-let investments will typically own their own homes and have good incomes. With residential property also resilient this means that the asset quality of buy-to-let loans in the UK should be robust.
Looking at the valuation and Paragon trades on 12.7X forecast earnings for the year to September 2015 which falls to 11X in the following year. The forecast P/E drops to 9.7X in the year to September 2017 which doesn’t appear to expensive.
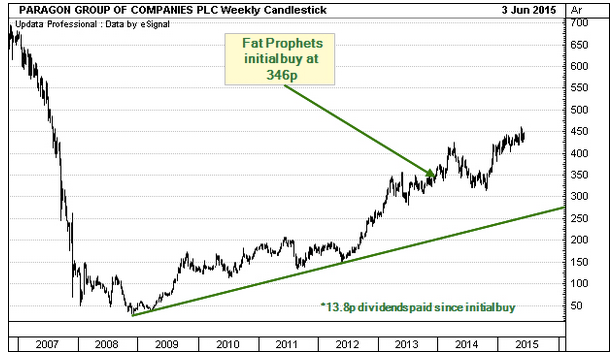
Paragon during the financial crisis
A look at Paragon’s share price chart from 2007 to 2008, though, shows that things haven’t exactly been a bed of roses for investors. This reflects investor scepticism of Paragon’s business model and its ability to access short-term finance.
The concerns were proved correct in 2008 when Paragon’s UK lenders declined to renew a £280m working capital facility. While this facility had been in place for the prior 12 years the credit crunch put paid to business as usual.
Paragon was therefore forced to undertake a rescue rights issue for £287m in January 2008 with shareholders offered 25 shares at 10p for each share owned. This was a discount of over 90% to the previous closing share price of 102p.
The reasons for the withdrawal of the working capital facility aren’t clear but it may have reflected the liquidity issues at UK banks. Paragon’s lenders could also have taken a negative view of its exposure to UK housing given the economic downturn at the time.
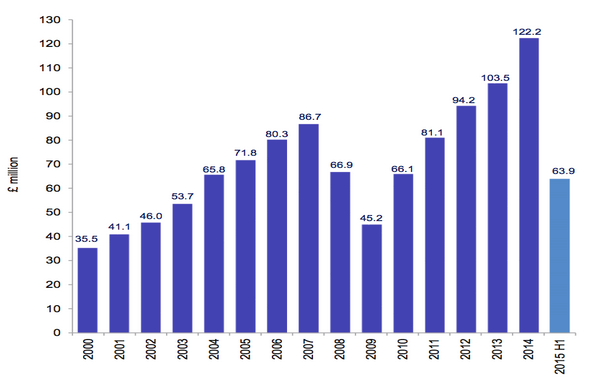
However, Paragon’s loan book has proven to be resilient with the company being profitable during the financial crisis. Paragon did see two years of weakness with profits almost halving from 2007 to 2009 but profits have since more than bounced back.
Paragon profits from 2000: surviving the financial crisis
Source: Paragon investor presentation
Paragon today
Looking at the group today and the business momentum is evident given that new buy-to-let lending is up 65.7% in the six months to December 2014 on the year before. The buy-to-let pipeline at the end of 2014 was also double what it was last year.
Paragon also launched Paragon Bank in February 2014 which allows it to access retail deposits. At the end of 2014 retail deposits came in at £165m and the bank is targeted to fund half of Paragon’s new lending over the medium-term.
Paragon Bank is making direct consumer loans in areas like cars, secured consumer lending and buy-to-let loans. This allows Paragon Group to become more diversified over time although the asset base is still likely to be driven by buy-to-let lending.
The Idem capital business is a leading purchaser of UK consumer debt in areas that include mortgages and unsecured assets. Paragon is currently using the group’s equity to fund these purchases but could look to external funding if volumes become economic.
Paragon Group’s divisions
Source: Paragon investor presentation
Paragon’s strategy: diversification of funding
The experience of the credit crunch has shown that it is not sufficient for Paragon to have a robust asset base. It also needs to have access to funding to help avert the kind of liquidity crunch it saw in 2008.
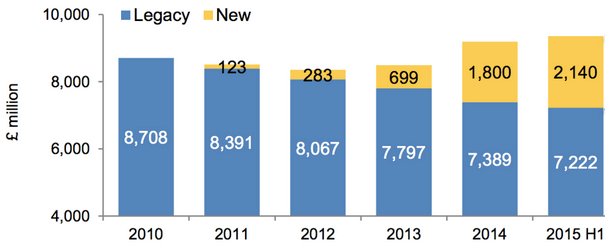
In 2010 all of Paragon’s funding came from legacy sources but in the first half of 2015 post 2008 funding sources accounted for 23% of the total. This trend is set to continue and will reduce the group’s reliance on short-term wholesale funding.
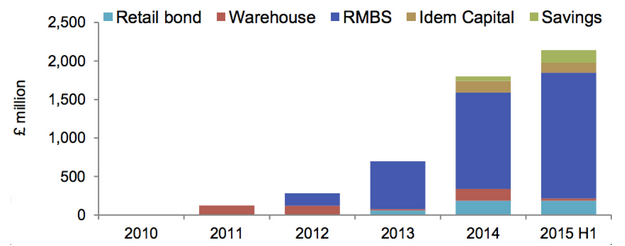
Residential Mortgage Backed Securities (RMBS) are the main area of alternative finance and have seen robust growth. Paragon Bank also helps establish a source of retail funds and will become more important over time.
Paragon’s funding mix is changing: legacy & new funding sources
New sources of post-2008 funding
Source: Paragon investor presentation
Paragon profits momentum
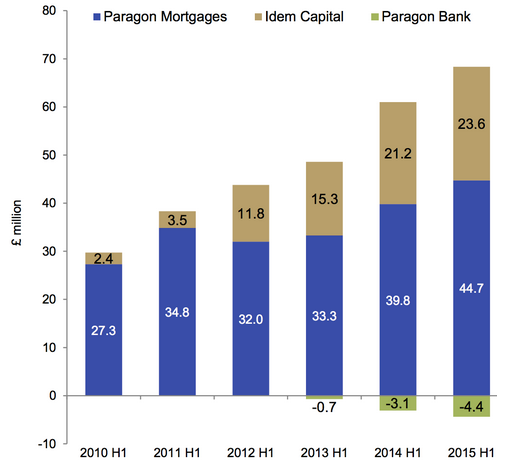
In terms of the recent profits performance, the first half saw operating profits increase by 10.4% to £63.9m. The return on equity improved to 10.8% from 10.5% the year before which is despite the start-up costs for Paragon Bank.
Paragon has a robust capital structure with the Core Tier 1 ratio of 19.5% in the first half which was flat on last year. As such the group boosted the interim dividend by a fifth and has been buying back its shares.
Paragon operating profits momentum
Risk profile
To help avert any future liquidity crisis the group is diversifying its funding streams and has started its own bank. While we can “never say never” the company now looks much better able to offset any future financial crisis.
Paragon’s asset base was certainly more resilient than that of UK high street banks which lend to the corporate sector and cyclical areas like property development. As such Paragon may be less risky than the banking sector if it can avoid liquidity issues.
With the quality of the business improving and a sound asset base of buy-to-let loans Paragon looks well placed. This is not least given strong UK rental growth and the slump in UK new home building to 140,000 in 2014 from a high of 219,000 in 2007.
Rising interest rates are a risk but the UK base rate is expected to normalize at a much lower level than in recent history. Buy-to-let landlords also typically have large deposits which helps offset the risk of higher interest payments.
Summary and valuation
Paragon Group went through a near-death experience in 2008 when its lenders pulled the plug on a working capital facility. This generated a liquidity issue which it could only solve through a deeply discounted rights issue.
However, the solvency of the business was sound with its portfolio of UK buy-to-let loans proving to be resilient. As such Paragon remained profitable and is currently is seeing strong momentum in the UK buy-to-let market.
As such Paragon’s forecast P/E of 11X for the year to September 2016 is not expensive and falls to 9.7X in the following year. The shares offer a yield of 3% for the year to September 2016 which increases to 3.4% in the following year.
It may even be tempting for some investors to turn to Paragon’s shares rather than investing in buy-to-let residential investments directly. Certainly Paragon appears to be well placed to benefit from the resurgence in UK buy-to-let lending.
This report was produced by Fat Prophets Senior Research Analyst, Andrew Latto
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
1 comment
Hmmm, I have just sold my Paragon of Companies (LON:PAG) holding. I bought last year so they have had a good run, but the last 3 months the sp has not gone anywhere and the Stockopedia ranking has fallen, so I decided to take my profits and move on. Will keep an eye on it. Broker forecasts have fallen as well.