Paul's 2023 watchlist - top 20 ideas for value/GARP small caps

My 2023 watchlist for small caps
2022 was a terrible year for me, and for small caps and tech investors generally (with both AIM, and NASDAQ, down by about a third). Personally, I've given a lot of thought to all the things I did wrong in 2022, and learned the lessons hopefully. So I don't think reviewing a lousy year is a productive use of time. I'd rather look forwards, and see how we're going to make the money back again, with good ideas for 2023 and beyond.
Like many investors, I keep a watchlist of shares that I think look interesting, follow the prices, and then sometimes buy things on the list, e.g. if there’s a positive or in line trading update together with a solid outlook statement (I generally only buy after a decent trading update, to reduce the element of guesswork and profit warnings, at least initially). So when I spot an interesting share, I add it to my watchlist.
I thought it would be useful, and fun, to go through my watchlist of c.100 shares, and select what I think are the top 20 best ideas (from a Value/GARP investing perspective), and publish them - as ideas people might want to research further. Never recommendations, as it's up to you to research everything yourself.
Obviously I can’t predict the future, so I have no idea what the share prices of any of these will do. All of them are likely to go up, down, or stay about the same - but unfortunately at this stage, I don’t know which will be which!
In the past I’ve found that in a good year, I typically get a winner:loser ratio of about 60:40, in a very good year it can be as high as 80:20, and about 1 year in 3 or 4, I do badly, and have more losers than winners.
2022 was a very bad year, where my ratio of winners to losers was more like 10:90 - but that’s to be expected when the whole of AIM fell by about a third. Plus I was just in the wrong sectors, and over-concentrated, and I badly misread the macro picture. So there we go. Let's just draw a line under it, with my apologies to anyone who was influenced by my misplaced bullishness on some shares.
However, in the past, I’ve nearly always done really well the year after a bad year. So I’m hoping 2023 will be more like that!
I only own 1 share on the list, which is flagged, so am not talking my own book. But I’m considering purchases at some stage of all the rest.
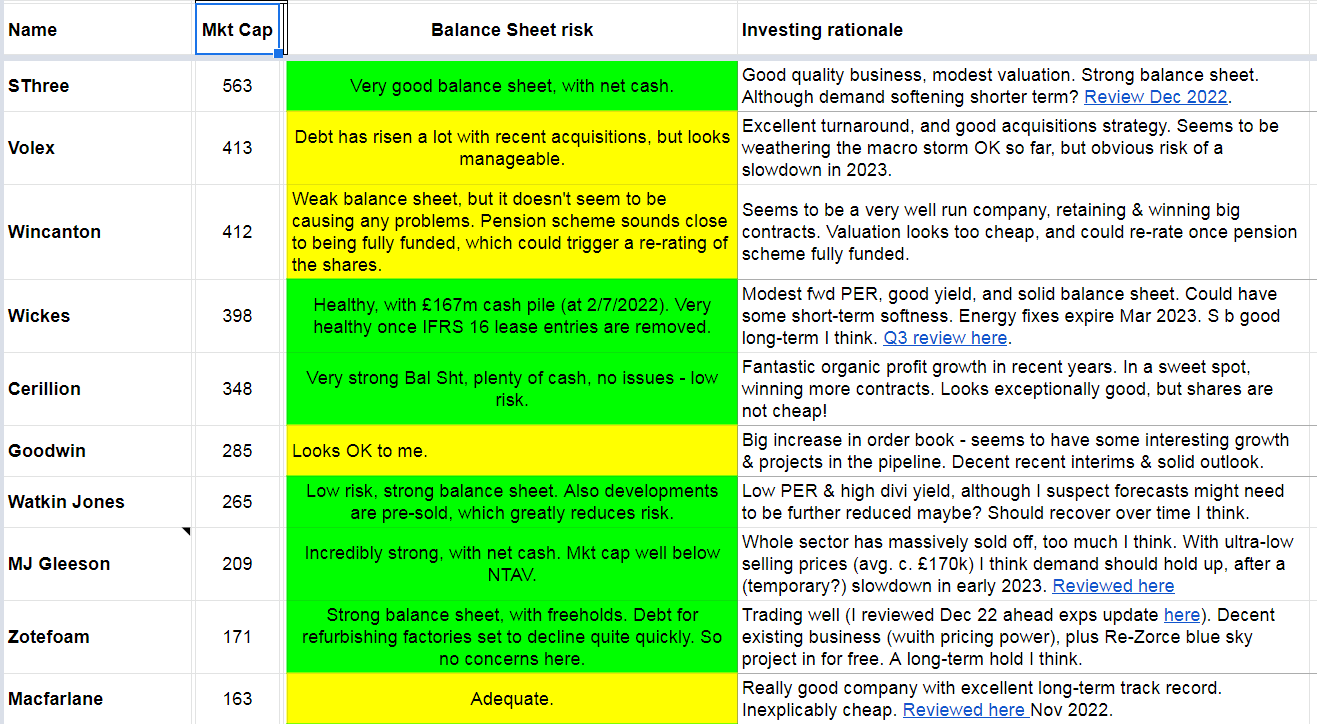
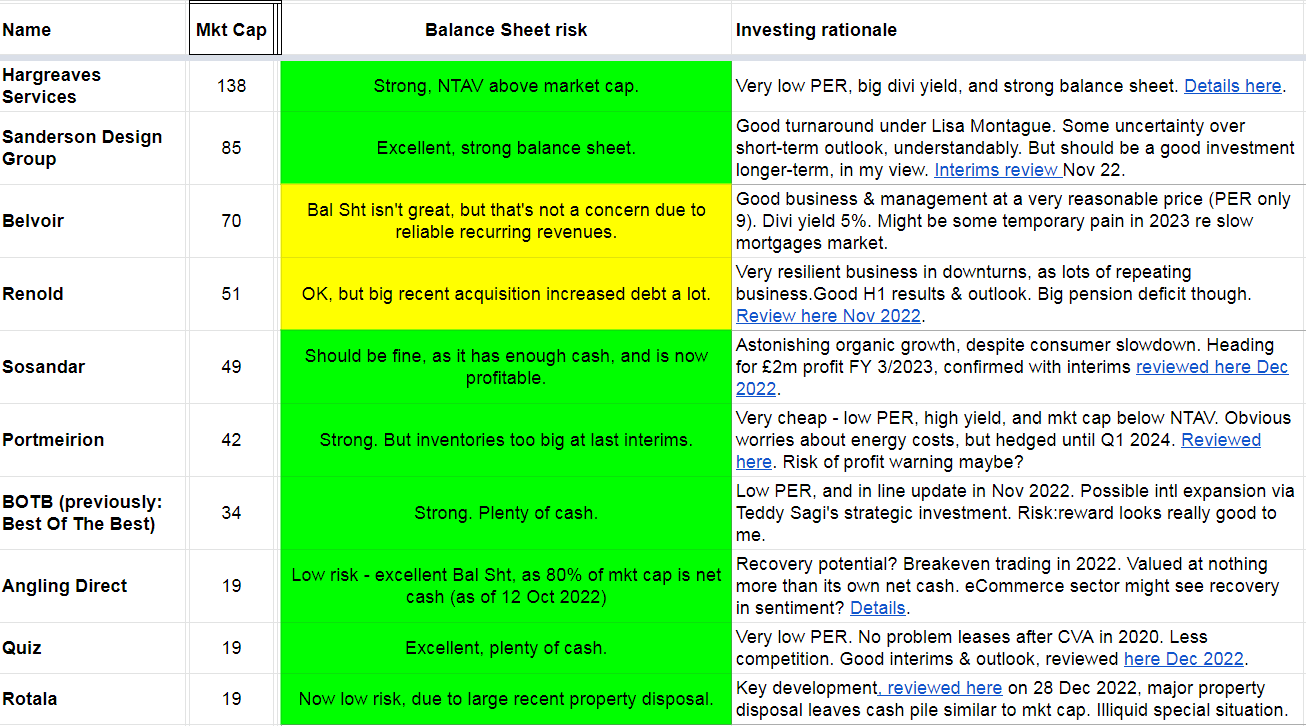
It’s all on a spreadsheet, which you can view or download here [EDIT - sorry I got the sharing settings wrong, should be fixed now] - which contains explanations for why I like each share, my assessment of balance sheets (so we can avoid dilution/insolvencies, and ride out the inevitable short term disappointments that are likely to happen in a recession).
I’ve also added formulae to track this list of shares, and see how it performs in real time, using googlefinance prices that update automatically (scroll to the right, to columns J-L).
So in 12 months time, you can either praise me for picking some good shares, or laugh at my expense at another poor performance.
The list is now locked, so I won’t be editing it (other than for any factual errors that occur).
Good luck to me!
As with all our stuff, you must do your own research, and not rely on me, as my ideas will often go wrong. That’s the nature of investing. Although by selecting companies with sound balance sheets, I’ve deliberately picked shares that can ride out the inevitable profit warnings that occur in a recession. Also I don’t think any of them will need to do fundraisings, even if trading does deteriorate. So I'm not necessarily saying any of these shares will go up in price in 2023. They're more long-term investment ideas, that should do well with a multi-year timeframe. And in many cases pay decent divis along the way too.
Here’s a screenshot of the spreadsheet - to give a flavour -

Here's an abbreviated form of the spreadsheet, making it narrower, for viewing here without opening the spreadsheet -
Let's see what happens. I encourage readers to post your top 5, top 10, or top 20 (whatever you fancy) shares ideas for 2023 too, and the reasons why you like them.
Good luck to all for 2023 and beyond!
Regards, Paul.
EDIT: I'm also working on another 20 speculative ideas (so riskier, and not value/GARP) for 2023. That should be published later this week.
EDIT 5 July 2023 - Half year update is here - short version: they've beaten the small caps market (AIM) by 17%.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

52 comments
Hi Paul, any reason why Warpaint London (LON:W7L) is not in your top 20, you seem quite keen on it?
Hi Rusty2,
Sorry, just seen your message. Unfortunately I forgot to include Warpaint London (LON:W7L) in my list, which was an oversight. Pity, as it's up 48% YTD as of 29 June.
Regards, Paul.
Paul owns up to 2022 being a terrible year. The question is have we taken our medicine from the Bear market or is there more to come this year?
Until we are sure the pain is over it is pointless to re-enter the market.
There has been no capitulation, interest rates are still rising but negative when inflation adjusted, recession is reducing earnings, etc, etc..
Both Paul’s list and the AIM market will do well when the final shake out is concluded.
The questions we must answer first is, “Where are we in the economic cycle? Where stands the investment clock? Is sentiment at capitulation, etc?
Bear markets end in sharp falls and Bull markets rise in small steps. Standing on the side lines and patience still seems the safest strategy. Being late loses no money.
This is just brilliant paul and has started a great sharing of ideas and information for dyor!
I survived 2022 with my top two holdings bank of Ireland and plus500 both more than covering the” rest” .
For this year an eclectic mix.
Destiny pharma, a lot to like, but understanding the reality of needing a partner for US entry is key. Think if/ when they get US partner this could move significantly, again.
Global ports holdings. Fails your balance sheet test I guess with its debt/ balance sheet, but long term and tied to the asset base. A different play on the growing cruise market , and global revenue streams, with the US still to be attacked.
Like others, somero
Sosandar, has macro and fashion risk, but brand loyalty is strong and the management team haven’t really put a foot wrong so far.
can see real growth via further third parties in 2023
Final one is a bit left field , Amedeo air four plus, yield is crazy. I think their market will hold up . Thai air need to survive but if they do aircraft leases go out to 2035. Directors at last six months report, stated they are looking at ways to unlock shareholder value.......!
These represent some of my holdings that i am hoping will produce my greater returns in 2023.
Hope this is of mild curiosity to others .
All the best
Thai Airways should survive, the Thai government own nearly 50% and I doubt will let them go under.
Reading some of the posts, I wonder if everyone realizes these are actual companies chosen not to hold by the blogger?
Actually it is 7, I hold which are: Belvoir (LON:BLV) Cerillion (LON:CER, Hargreaves Services (LON:HSP, Sanderson Design (LON:SDG), Sosandar (LON:SOS), SThree (LON:STEM), Volex (LON:VLX.
Thank you Paul. Very helpful, I hold six of these companies. VLX, WJG, GLE, HSP, BLV & PMP so I hope you are spot on!
I currently hold 6 on the list, most I have held for some time. There are a few that are also my watchlist whichI started last August. Since mid October it is up around 17% which is not bad, considering more are being added recently, certainly better than my current folio. So I'm thinking of dumping a lot of older non performing stocks and start afresh. Although quite a few have bounced off their lows, such as Redde Northgate (LON:REDD), Saga (LON:SAGA, SCS (LON:SCS) , Sanderson Design (LON:SDG.
Excellent list. Thank you Paul. I only hold one Volex (LON:VLX) where I like the management and knowledge of one other Best Of The Best (LON:BOTB) which I use to hold and got severly burned and I don't trust the management but might have to revisit.
Will take a look at the others over the coming month.
Regards
Michal
I've followed you for years Paul and have always been impressed by your honesty when it comes to your investments. It's been a tough year for most of us, who knows when the market will turn in our favour. Your analysis has always been excellent and that's what makes money in the long run.
Ok here goes; never wrote in here before.
I focus on high return on equity, 25% compound over 3 years, doubles your money.
Over the very long term, gains should equal to return equity.
I have 4 stocks that I am focus invested in:
1) CNIC - 50% ROE once publishes this years results. Pivoted the business. Reducing debt, doing share buy backs. Huge sector to address - GoDaddy in the USA valued on x25, CNIC on x10. 70% CAGR revenue growth. NED purchased £3m shares recently. Safe DCF £1.5bln valuation.
2) GAW - 61% ROE. High gross margins, High net profit margins. Significant moat. About to agree deal with Amazon on films. Safe DCF £3.6bln valuation.
3) INDV - Opiod treatment. 85% ROE. High gross margins and net profit margins. Sublocade revenue to grow to $1.5bln by 2025. Currently only $250m. Listing in USA Spring 2023. DCF £5bln valaution.
4) SOM - 51% ROE. 10% dividend. High Gross margins and high net profits. No debt. Chance of take out. DCF £500m valuation.
Somero seems too cheap, they've built capacity to support a $175mm topline business. That's 25% growth from here, if they get anywhere near that over 5 years or so you should get paid reasonably well. Expectations seem too pessimistic. Re. takeout, CEO was there for Dover's purchase and the subsequent spin out so there's some background there.
GAW I was buying quite aggressively under £70, I'd like to buy more but had fair value around £85. Will revisit
How are you getting 50% ROE for Centralnic? I put this one on the too hard pile as the accounts are messy and management seem too promotional for my taste but if that 50% ROE holds water on a forward PE of 10ish I might be tempted into a small position...
CentralNic (LON:CNIC) sentiment seems much improved after recent CEO change and greater focus on shareholder returns.
Hi George, appreciate the comments.
CNIC -
9 months $61m EBITDA /3x4 = $81m (strongest quarter will result in more)
Less $22m Depn and ammortisation = $59m for year
$59m / equity of $114m.
Any comment on INDV?
ROE is a backward looking measure so not usually the main thing I look at - it is useful for things like banks and insurers, but perhaps less so for more typical trading companies. Of course if a company continues to deliver ROE of 50% then the share price is going to see pretty spectacular gains. But just because it did 50% before doesn't mean it will again.
RoE is no more a backward-looking measure that PTP, EPS or DPS. If you calculate it off historical data, then it is backward-looking; if you calculate it off projected data, then it is forward-looking.
Thanks Bouden54; although backward looking, if can be achieved consistently (not a fluke) it means management (in a growing market) can deploy capital at high rates of return. Worth reading the "Dhando Investor" if you want to find out more.
Hi Paul, Great s/s and thanks, very useful. One mistake (haven't checked rest!), GDWN row 9 but formula in K9 refers to B8, (same for row L). Also thanks for the SCVR "summary tables", and of course both your daily efforts. Where do you find the energy? An avid reader but don't comment often.
HNY, BOTH
Holding four in Paul's list. About breaking even on a year ago and holding about thirty shares across different sectors for diversity in security as coming up to retirement, maybe too many to keep track of. In 2022 generally invested into companinies with low debts, good cash flow, low valuations and high dividends,. Polar Capital, one of them, feel could do very well along with other fund managers if and when rotation into growth stocks occurs and market picks up generally, bought Hollywood Bowl as well recently on good results, seems very well managed. One sector not in is housebuilders but valuations look very tempting at moment.
Thanks Paul, great idea. Comment about 60% of ideas working out very relevant.
Great, thank you Paul. I cant download. Use Firefox. Any ideas, anyone for a simple fellow like me ? Thank you in anticipation.
Login to your Google account. I would do this in Chrome personally, just works better being Google and Google.
Copy the link to Paul's spreadsheet (right click on the link and select copy link).
Paste in to your Chrome browser.
Click on File
Click on make a copy.
That should work.
Regards
Michael
Thank you Paul for another super initiative.
Being down 19% last year and 17% across the family portfolios, reduced my average return over 13 years to 14%. Confidence rocked I’ve found it cathartic to distil down to my best 5 ideas for 2023.
My key lesson from 2022 was don’t ‘buy the dip’, be it LON:ATYM, LON: BOO, LON:VLX or even GOOGL but, as you can see, I find it hard resisting ‘bombed out’ sectors
This year’s project is to see if I can be more comfortable (and successful) buying into strength. I find I often wait for good news then don’t like the new share price when the good news arrives!
So, thanks to Ed Croft for this year’s homework – reading ‘Stocks on the move’ by Andreas Clenow and maybe re-reading ‘How to make money in stocks’ by William O’Neil.
Paul
Thanks for fixing the popup problem in your summary spreadsheet.
In that revised spreadsheet you include ACSO coloured blue asking (in the popup) for feedback on whether it's more readable. For me, black on that dark blue is almost UNreadable - you'd need to use white text on a blue that dense. Just my 2p-worth.
Thanks for all your hard work! It really does make the Stockopedia subscription very good value.
If anyone is interested:
1. Avacta (LON:AVCT) (I hold) Potentially revolutionary chemo therapy enhancement, currently in Phase 1a of a trial, results imminent, hosting a Science Day to present findings in Feb '23 - will make me rich or make me poor.
2. Barratt Developments (LON:BDEV) (I hold) Along with pick 3, I've bought these for the long term and will continue to buy in this year. Strong cash balances, pay good divi's when times are good, accept they will likely be a drag on my stats until we get through this challenging time.
3. Taylor Wimpey (LON:TW.) (I hold) as above.
4. Foresight Solar Fund (LON:FSFL) (I hold) Good F-Score, Good Z-Score, nice divi which is well covered.
Looking to open positions in:
5. I3 Energy (LON:I3E) Good divi, well covered, decent F/Z-Score.
6. Wickes (LON:WIX) Good divi, good PER. Good F-Score.
7. Somero Enterprises (LON:SOM) Good divi, good PER, have confidence that this type of business will endure.
8. Castings (LON:CGS) every update I read about these just seems to shout solid organisation. Feel whilst it won't see huge gains in share price, it feels like a safe place to put money and get a reasonable divi.
I've been considering themes and how best to play them for 2023 along with a couple of examples.
Theme 1 is that there are quite a few bombed out stocks with high asset backing that haven't really recovered. Avation (LON:AVAP) is about 100p with a NAV closer to 300p and should be back into profitability. If one assumes air travel is generally robust then this should see a big re-rate at some point.
I could see Gear4music Holdings (LON:G4M) doing well in the next 12 months. It is very bombed out but probably a longer term structural winner across UK and Europe. Absolutely hated right now but often those are where opportunity lies. ie avoid the crowded trade. I have struggled to pull the trigger though as I can't decide the right time to buy. I'd like to see a small uptick in a poor retail market first but annoyingly it is up 12% today so someone has got there first.
Theme 2 : I see a number of Asset Managers in same boat. Sitting on large cash piles with good dividends and once AUMs increase with markets and inflows manifest there should be a re-rating in many of these. Average PER tends to be 12-14* across a cycle (1-2% of AUM is another metric) and when I look forward a number of AMs are sitting well below.
Theme 3 : Resource stocks still look decent to me. Atalaya Mining (LON:ATYM) has been marked down on the cost of power but this will go away for a variety of reasons (not least own solar power generation) and I can see them doubling, particularly as I like copper as a longer term commodity market anyway.
Petrotal (LON:PTAL) appears to manage the geo-political environment in Peru very well and as I see oil in the $80-$100 p/b range for the foreseeable future at a production rate of 22,000 bopd this could have net cash close to its market cap over the next 18 months. Expect dividends too.
I agree with davidjhill about themes, it helps me rationalise why I hold the companies that I do. Occasionally I will invest outside a theme and then it forces you to think why you are doing it. Background: I'm about 10 years from retirement and investing through a SIPP, with around 30 shares held at any one time. Here are my top 5 for 2023:
Volex (LON:VLX) is the only one of Paul's 20 that I also hold. This is part of my 'electrification' theme, I think we are in the early years of a 2-decade transformation in transport and energy systems and Volex is well-placed to capitalise on that, well-run and with good geographical and product diversity. Great organic growth as well as a track record of successful acquisitions.
Atalaya Mining (LON:ATYM) is in the same theme and is one of the few copper miners in western Europe. I have great admiration for the likes of Central Asia Metals (LON:CAML) but the political risks are a concern. There was a nasty impact from energy price rises last year, which are now abating and later in 2023 the company will switch on its own 50MW solar facility. I also hold Rio Tinto (LON:RIO) for the dividends, but it hasn't got the same potential for share price appreciation.
Polar Capital Holdings (LON:POLR) has been mentioned by others and is my pick of the fund managers. The sheer quality of the operation will shine through. I have held this a long time and of course would have been smarter to have sold in mid-2021 and bought back in. But there have been generous dividends in the meantime and I could see these doing well as the recovery gathers pace in late 2023 and 2024.
Kenmare Resources (LON:KMR) is my pick of the 'overlooked miners that are well-managed and just too cheap' category, with a P/E in low single figures, decent dividend and in-demand products. Also in this category is Sylvania Platinum (LON:SLP) although there are worries about their dependency on other mines and whether they will run out of feedstock. I also own Shanta Gold (LON:SHG) which hasn't gone as well as hoped, but I think is well-placed once the new mine in Kenya starts producing later this year. I went into this one too early and have some ground to make up.
Avation (LON:AVAP) the aircraft leasing company is my final share and is harder to categorise. Hit hard by the pandemic, the management team held the business together and it is now well-positioned to make further progress in 2023. I like the way they have positioned the company in fuel-efficient aircraft and the discount to NAV is just too great. Of all five, this is the one with greatest share price potential over 12 months - it could easily double and would still be decent value IMHO.
I also have dull but safe names like Aviva (LON:AV.) and Legal & General (LON:LGEN) that are cash-rich, well-run (some Aviva shareholders may disagree) and pay regular dividends, they are hold-forever stocks as far as I'm concerned. But they are hardly SCVR territory.
And Tremor International (LON:TRMR) of course. Grrr... don't talk to me about Tremor.
Thank you to anyone who has read this far and best wishes for a successful 2023! And of course a massive 'thank you' to Paul.
If it's of any interest to anyone, my top 5 are :
1. Valeura Energy (TSE:VLE). Canadian E & P co with oil assets in Thailand & gas in Turkey. Soon to be 25k bopd producer. Original purchase in summer last year when cash greater than mcap & then did transformational deal to acquire Thai assets for amazing price & shares taken off since. Big hopes for this share, could hopefully be my first ten bagger. Current SP $2.25 CAD, analysts target price $6-8 CAD. If do another amazing deal like recent one then could run even further. Gas assets in Turkey are wildcard. Could be sitting on 20TCF of gas (approx $3bn annual rev worth) if drilling campaign successful but big if.
2.Petrotal (LON:PTAL). US based E & P co with oil assets in Peru. High quality asset with long field life and bargain basement valuation. Still in production ramp up phase, throwing off cash, distributions to shareholders should start soon. Not without risk, most notably angry locals who enjoy protesting.
3.Southern Energy (LON:SOUC). Canadian based gas E & P co with assets in US deep south. Early stages of potentially transformational drilling campaign on traditional fields that have been ignored for past decade in favour of US shale and looking to re-enter with new drilling tech. Play on growing production & global need for natural gas post Russian invasion of Ukraine & green transformation and growing demand for gas as transition fuel. With intermittency of renewable power generation, gas is one of cleanest, most reliable fuel source there is.
4.Filo Mining (TSE:FIL). Canadian based mining co with amazing, world class cu/au porphyry asset on Argentina/Chile border. Filo is spin off of well known, long established mining co, Lundin Group, who have excellent previous record of finding & developing such major deposits. This discovery is all set to become one of biggest & best mines in world. Filo is arguably the best undeveloped deposit in the world at the moment and could even overtake the great Escondida in Chile as drilling continues, but that's a longshot. Mining major BHP recently bought large stake in co. Play on increasing global demand for copper because of green transition and just sheer quality of asset.
5.Alphamin Resources (CVE:AFM). Mauritius based co with S African mgt team. Owns Bisie tin mine in DRC. Big jurisdiction risk but quality of asset is truly world class. Ave tin grade at most miners is approx 1%, Bisie's ave grade is 4% ! Tin is a very interesting niche market with supply dropping & demand set to increase, principally because of tin's use as solder (the glue of metals). Owning mining co's is risky so I tend to try and buy & hold only world class deposits as fairly large positions.
That's my top 5. I went big on energy & mining at end 21/beginning of 22. During covid I was mainly invested in US big tech/SAAS/e-commerce. Don't know if this is of any interest but thought only fair to post mine as I enjoy reading everyone else's posts.
Thank you Paul, a link to your spreadsheet is saved now in the Google browser in my Financials folder under Other Bookmarks.
Paul, I find that I already hold 7 of your top 20 (Volex (LON:VLX) Goodwin (LON:GDWN) MJ GLEESON (LON:GLE) Macfarlane (LON:MACF) Hargreaves Services (LON:HSP) Sanderson Design (LON:SDG) Belvoir (LON:BLV)
Rather me feeling smug about them, you might care to treat this post as a profit warning!
Richard
Thank you Paul - very interesting and always good to share. And in that spirit my top 10(ish) split into the
top 5 MS International (LON:MSI) Macfarlane (LON:MACF) Zytronic (LON:ZYT) Vianet (LON:VNET) and Portmeirion (LON:PMP)
and the next 5(ish) not quite in the top5 but that might change Airea (LON:AIEA) James Fisher And Sons (LON:FSJ) Science (LON:SAG) D4t4 Solutions (LON:D4T4) Mercia Asset Management (LON:MERC)
To be clear - I already hold all of the these and they are pretty much my top 10 holdings. I am fully invested. Very fully invested right now, otherwise I would be buying more of these right now - my current gut feeling being buying more Macfarlane (LON:MACF) Zytronic (LON:ZYT) and Portmeirion (LON:PMP) in particular as they seem particularly undervalued right now.
short commentary on top 5
MS International (LON:MSI) - cash rich, profitable family/founder led engineering microcap fully invested in new products and facilities. No forecasts no analyst coverage. Steep price rise on recent contract news likely puts it on around 12x current year earnings - 10x current year EV - modest in view of future growth prospects. Potentially around 6x FY24 EV - though there is a very wide range of possible outcomes! Not been buying more as its already >30% of my funds.
Macfarlane (LON:MACF) Neglected packaging distributor (Also on Paul's list). Longterm astute management successfully buy and build in fragmented market. Tend to under-promise and over-deliver. Which might be why despite consistent profit growth over last few years the shares have been punished in 2022. Continue to buy more when I find the cash.
Zytronic (LON:ZYT) - Tiny manufacturer of large format rugged touchscreens and controllers. Cash rich turnaround fully invested in new products and facilities. Share buyback and cost reductions increase profitability and returns to shareholders. Prospects are high and rising, order intake has yet to accelerate - which is why I'd be buying now if and when I can find some dosh down the back of the sofa. But significant execution risk as order acceleration may be delayed or not happen despite award winning and patented products.
Vianet (LON:VNET) Not cash-rich but profitable founder-led turnaround moving to SaaS provision of remote monitoring, data management and payment services mainly across hospitality sites and remote vending. Serial disappointer. This time it's (might be) different. Acceleration of contracts in vending sites is significant - leads recurring revenue increase - also high capitalised R&D to overcome which holds back profitability. Once (if) this happens operational leverage will be high on largely recurring revenue. Good product. High market growth opportunity. Significant execution risk. Been buying more on weakness.
and Portmeirion (LON:PMP) Something of a turnaround for this pottery maker and owner of a collection of under-invested tableware brands with considerable potential. Raised capital at the start of pandemic to invest in products, facilities, productivity, logistics and direct internet sales channel. (also on Paul's list). Likely UK volumes falling - but prices rising and record revenue is 2/3 export - USDollar and Freight-rate tailwind. Shareprice has been falling despite in-line update. Seems to have reached a floor. Astute management team raised capital and secured energy (through to 2024) in 2020. Tends to under-promise and over-deliver. Been buying more with any spare change I can find. Did I mention nice dividend as well?
I'll leave it there for now! Maybe come back to the rest if time - or interest - allow,
cheers
Mark
Great work Paul, thanks for sharing.
My top 5;
GAMA (Larger market cap, but consistent ROCE, strong balance sheet)
OMG (large cash pile)
MJ GLEESON (cracking balance sheet, focus on lower cost properties)
SOMERO (Income, strong stock ranks)
WINCANTON (Held for a few years, pension being fully covered and focus on debt paydown should kick in).
Point of note- one of my best performers over the last 3 years has been Ashtead Technologies (I work in the industry). Brought in on IPO after reading all the perspective, then slowly sold down my position as it came up more & more in key magazines (IC etc), Twitter feeds, Stocko chats recently. May have just be conicindent, but I think there is something to be said for finding some 'un-discussed opportunities' to avoid the risk of buying the post-tip hype!
Since using Stockopedia, my annual perfomance has taken a significant turn north. Great resources and excellent commentry so really appreciate it from yourself and the team.
One of my best performers over the last 3 years has been Ashtead Technologies (I work in the industry). Brought in on IPO after reading all the perspective, then slowly sold down my position as it came up more & more in key magazines
Why sell down? Is there a slowdown in the business’ performance or that you’re seeing in the sector. If not, why not ride the growing investor interest and enjoy continuing ATHs? You have an information advantage in the sector after all.
Fair point; I guess when you have market sentiment pulling down some good quality shares, (say a 20% drop on no news), then a holding which is fairly new to the market moving 30% higher, then feels like moving some of those gains to a share which has been hit but with a better track record on the market makes sense? I guess it was also trust in my own judgement too! Seeing a significant amount of IPOs falling flat, and only having my own research to rely on.. needed more trust in my own work!
I could be wrong but I think Ashtead Technology Holdings (LON:AT.) has a long runway for growth. I’ve been topping up at these ATHs. It’s still not expensive, being priced similarly to Ashtead (LON:AHT) which is at a cyclical dip. And that’s where I’d focus when you get jittery sitting on a big gain.
This is great Paul, thank you so much for sharing this.
As requested I would like to share my holdings
My 5 biggest holdings after reshuffling in 2022
RIO (Good Divs, high stockrank, low pe, also a hedge against UK and small caps)
SNWS (Good Divs, low PE, High stockrank, was very cheap )
QUIZ (High stockrank, was very cheap, lots of promise here)
SCS (good divs, high stockrank, a happy hold for many years.)
TSLA (guilty secret, I follow the company very closely and now waiting for the bounce back!)
Wanting to buy and watching very closely
SOS (great growth company, current chart setup looks good)
M
Thanks Paul for this, what triggers if anything these going from watchlist to ownership. Is it just the availability of cash or do you have a target price?
Hi Paul,
Thanks for the list and reasoning. Very quickly my top 5 for 2023 are:
Somero Enterprises (LON:SOM) I believe they are going to show that they can keep paying a handsome dividend. They are priced for a downturn. If they can keep the dividend going (or even maintain a slightly reduced dividend) then what is not to like? They are also a takeover target IMO.
SThree (LON:STEM) & Quiz (LON:QUIZ) agree with you (thanks for the coverage)
Capital (LON:CAPD) Very low PE and PEG. Nice dividend. Supplier to companies like Centamin (LON:CEY) who appear to have turned around. Analysis services growing.
Ricardo (LON:RCDO) Strong projections. A sector I like in the current climate. Possible takeover target. Paying dividend.
I have recently started small positions in the above and aim to grow these as the global outlook develops. All of my choices are rated 80+ Stockrank which is one of my criteria. I suspect that 2023 will be a year where investors look for companies that are safe and offering tangible returns.
Renold (LON:RNO) Like you I am keeping an eye on Renold (LON:RNO) just haven't pressed the buy button yet!
Very useful, thanks Paul. I've just printed this out on A3 and that loses the last column. If you get a chance to reduce it's width, then great. Otherwise I'll hand amend.
Very good spreadsheet. Thanks Paul. I'm down 1/4/7% on my three portfolios v 2021 year end. Bruising but manageable. I think that quite a few smaller companies are still overvalued and may come down further. My most recent purchase was Secure Trust Bank , LON:STB so as usual I am fishing for value and income. IG group (LON:IGG) is another, but obviously a larger company.
By the way, I still haven't worked out how to post a ticker correctly!
Simply replace the £prefix with the @-now that's gone and upset it! Do it, use Caps for the ticker and keep typing, no full stop or comma
Many thanks Paul - At very least a useful list of ideas to take a look at. As usual my problem is insufficient time to research all the new ideas and insufficient new capital to investment in most of them in a meaningful way :)
Have noticed that Thungela yield is 50%, I hold and have had a huge dividend already. Any comments welcome
ditto
Access denied on spreadsheet ?
Ah sorry, I forgot to open the sharing settings. Now fixed, my apologies! If you try again, it should work now.
Sounds interesting, getting access denied on the spreadsheet though!
Ditto. I imagine it needs wider access permissions. Thanks for the effort that has gone into this. Better even than the one released earlier this weekend as it has price tracking embedded. From the extract these all look good choices. I even hold four of the nine already which is an unusually high hit rate for me vs the SCVR - what with me being very picky about debt/ROIC/growth and much less so on valuation. I guess that reflects what a tough year I’ve had in’22 - my quality growth stocks are cheaper than they’ve been for some time!
Thanks BnB.
I've updated the sharing settings now, it should work hopefully.
It's great to have all the top watchlist stocks in one central place. Many thanks for all your work creating this Paul - much appreciated.
Sounds interesting, getting access denied on the spreadsheet though!
Ditto