PCF miracle banking

Today I wish to report on a miracle in banking:
Pcf (LON:PCF)
This company is achieving miraculous firsts and new innovative approaches in banking...frankly its sexy and not dull...I would unabashedly make love to it if I could...
Here are the key amazing things I learned on today's Equity Development call with the CEO:
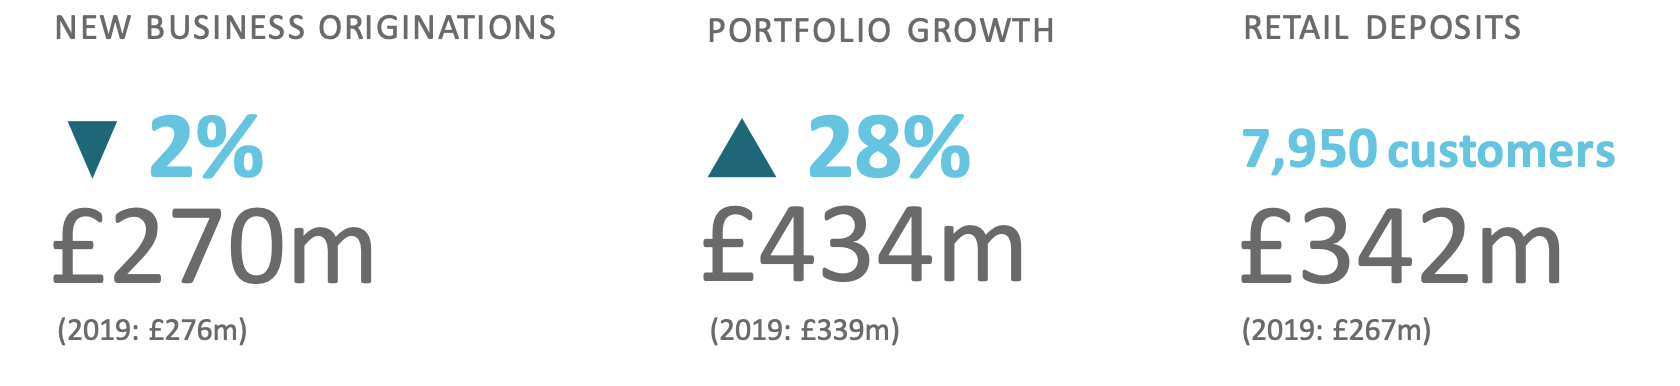
- Increasing lending through a pandemic and flash depression is conservative risk management
- Lending more to existing customer base (+28% portfolio growth when new business originations fall) whilst forbearance goes up massively (ie customers experiencing stress) is conservative risk management
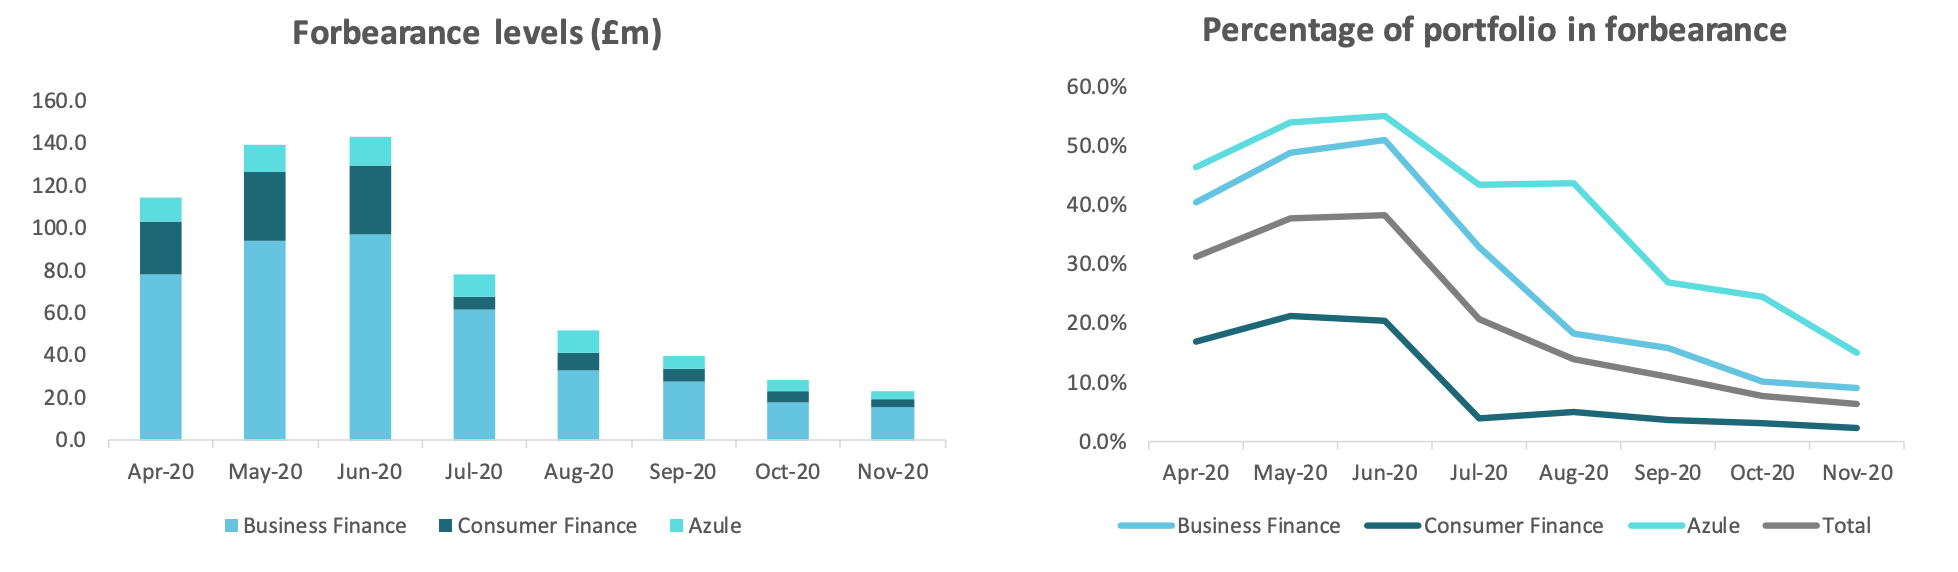
- When a new acquisition like Azule to which you had aggressively ramped up lending (in area, production services, that is notorious for viscous cycles and precarious economics for many participants but you said it was low risk as you'd got security on the cameras etc) takes a massive impairment this is clearly NOT as you don't employ conservative risk management
- More than doubling a new area of business, property bridge financing, during a crisis is conservative risk management
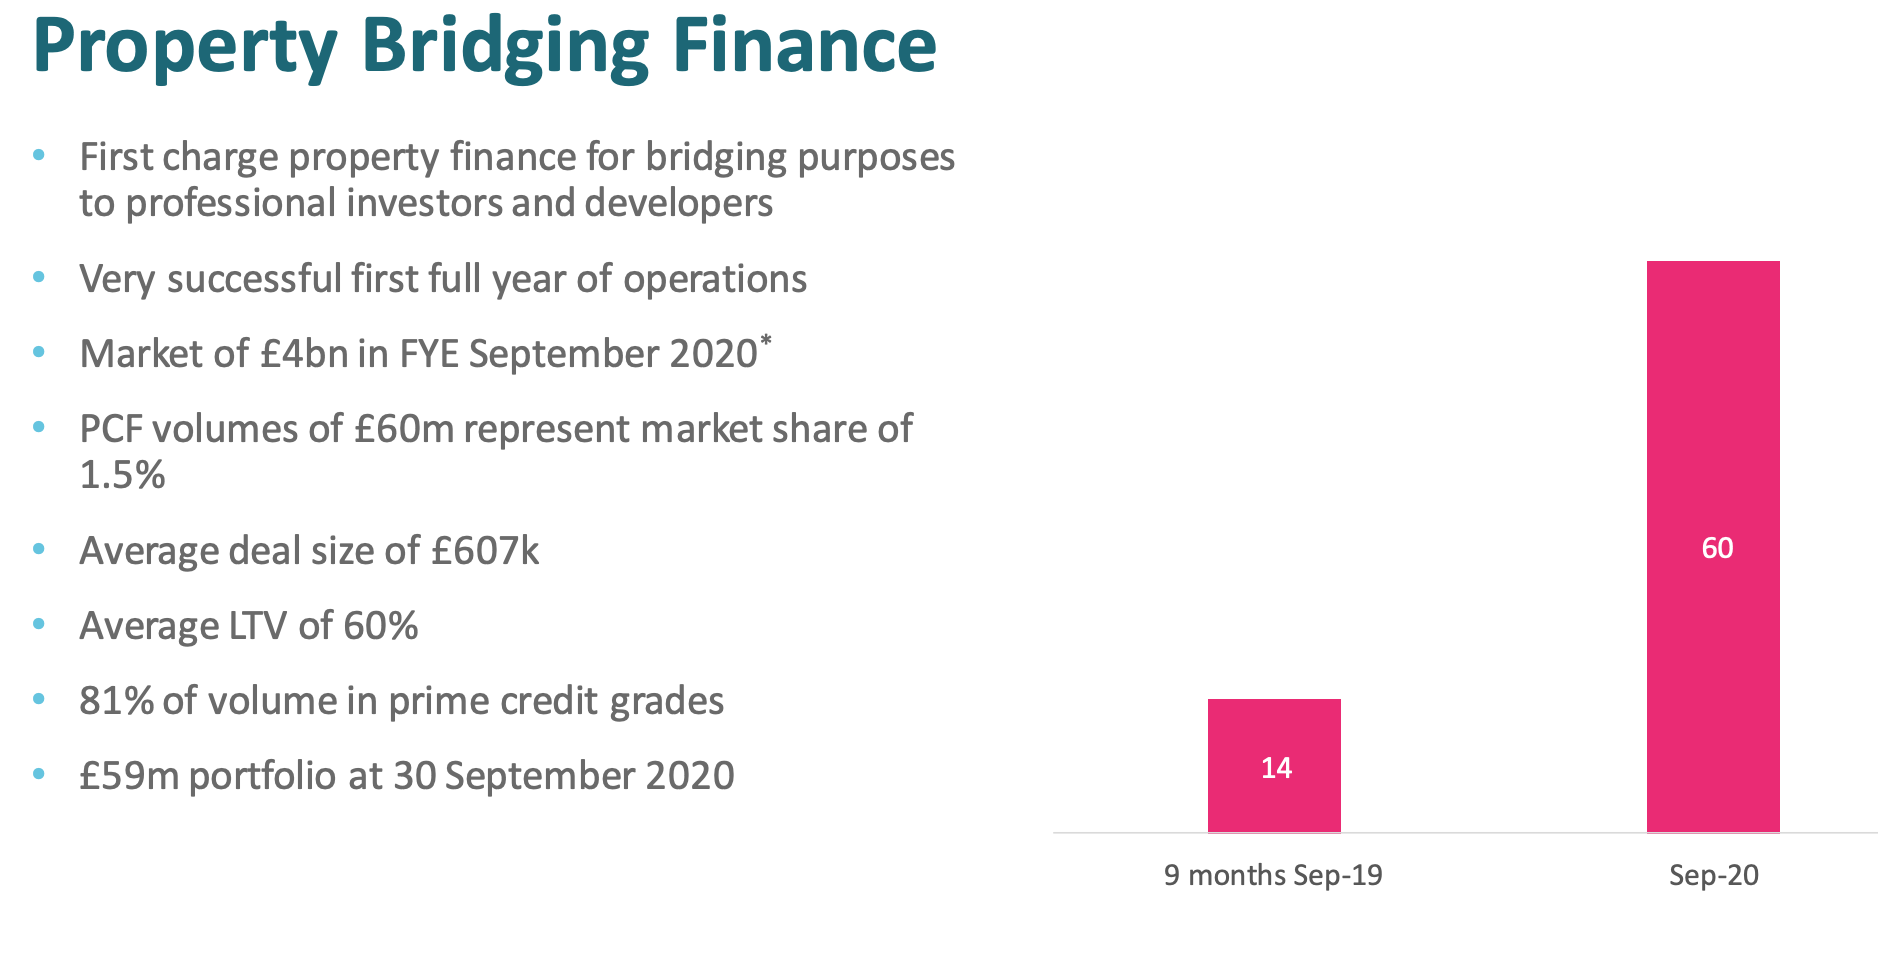
- ...LTV 60% average....brilliant....average UK bank has their mortgage book really well covered too as security price (the house) has risen and much more than loan....so this situation is not really different from say Lloyds...but we love PCF for it as obvs they are better at selecting the risk (even though they are in a new area)....no need to worry about the market freezing during a flash depression and so assets been stranded here (leading to duration mismatch stress, liquidity problems and then solvency)
- Taking on a super high level of new deposits in midst of a pandemic / flash depression is an act of conservative risk management....IS NOT RECKLESS GROWTH IN FUNDS TO ENSURE THAT FUNDS ARE AVAILABLE TO REDIRECT TO NEW AREAS OF LENDING AS CURRENT AREAS ARE DISABLED BY COVID HIT!!!
YUP! Everything about PCF screams conservative and not cowboy.
TBH, this may work out well for current shareholders as they have recklessly stepped on the gas....and if economic risks keep moderating then they may look like great growth.
IMO they don't care. Their 70% shareholders wants them to grow as fast as possible using capital from public market. If the lending goes wrong they'll step in provide capital and take control of the whole thing at bargain price....but have a much bigger banking franchise that others have paid for.
FCA should maybe check the management out just to make sure they know how to run a bank
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
10 comments
I thought Somers would step in and 'white knight' PCF as a listed entity...but looks like they will 100% shark it and wait for the delisting so as to pay zero...then they will undoubtedly step in...they have very large stake so they ain't going to let the value drivel away to nothing.
This has been a very shoddy venture. I think the FCA should really look into this sort of thing on AIM and penalise those involved.
So... look through the smoke and mirrors and we seem to be set on a course for Somers to take PCF (LON:PCF) private for a snip over 5p. Maybe they'll give PIs 6p and thank them for their troubles and that they provided all the growth capital to fund the super rapid growth of PCF. Nice play, Bravo
The miracle unravels further:
https://www.investegate.co.uk/...
It seems that quantifying unfolding risk was not a thing for Pcf (LON:PCF) nor employing processes to resolve and minimise costs of soured loans. I suspect FCA have had a lot to say re competence.
Its poor by PCF and surprising new mgt don't want to develop key resolution competences in-house given they have riskier loan portfolio than typical bank. Working their own defaulted receivables is surely a necessary part of total group risk management. How can they know which loans to underwrite if they don't own the pain of the default? Makes me think that the current corporate construct is not long for this world...
I see Pretend Cash Flows (PCF) still in purgatory....anyone got the scoop on what's going down? For a relatively small and simple bank this seems a very long time to sort out what has so far been relayed as a relatively minor matter (in the context of firm economics)
The new business land grab reminds me of investment bank/broker Lehman Brothers reinventing themselves as a sub prime mortgage originator in the early noughties. Kept the plates spinning for years and everyone made out like bandits ....... until they didn’t and the whole thing fell apart. Anyone remember their “NINJA” mortgage product in the US? 105%+ LTVs to borrowers with “no income, no job, no assets”. Marvellous. Hopefully not the case with Pcf (LON:PCF) when the newly appointed FD finally gets gets to look under the bonnet ...
Gus.
PCF -> Permanent Capital Forfeiture?
Someone just reminded me about this. I’d forgotten. Wrote after mgt call as was bemused most seemed to think things made perfect sense! ...I stick by all the above points but obvs we don’t know what’s going on yet
PCF shares have been suspended, anyone know what's going on?
Pcf (LON:PCF) news 19 may 2021:
"PCF announces that trading in the Group's shares has been temporarily suspended while the Group undertakes a further review in relation to its financial controls and reporting processes. This work is progressing and a further announcement including regarding the timing of the full year results will be made in due course."
Maybe there has been reckless growth....