Picks and shovels 2.0: A curated AI basket

Hey everyone, happy Friday!
Another post to build on the amazing recent webinar from Ed Croft and Graham Neary. This one delves deeper into the UK's AI opportunity, with a list of stocks carefully curated by the Stockopedia analysts.
If you've not seen the webinar yet, here's a link. And if you've got any thoughts or ideas on this article, please drop them into the comments below.
You may have heard of the AI data centres being run from a garden shed.
For those who haven’t, it’s a scheme where participants swap their boiler for a mini-data hub. The heat generated by the Raspberry Pi computers (more on them later) is transferred into the participants’ hot water system, saving hundreds of pounds a year.
Why bring this up? Well firstly it’s a fantastic example of British ingenuity. And secondly, a garden shed seems a good place to start talking about pick-and-shovel stocks.
Investors often say that when everyone’s rushing for gold, look for the companies making the picks and shovels. And as the UK’s AI landscape evolves, a whole spate of listed companies are springing into this space.
In this article, we’ll give you a curated basket of stocks drawn from Stockopedia’s recent analysis, and highlight three candidates in each of our guiding streams:
- Quality
- Value
- Momentum
So you get a series of ideas to supplement (but not supplant) your own research.
Why we’re doing this now
The media’s AI coverage still focuses on a clutch of U.S.-listed story stocks, many of them pre-profit, and treat the UK as a backwater far removed from the party in Palo Alto. But the real picture is changing fast.
- Spending on UK data centres is set to rise by 400% in the five years to 2029 (Barbour ABI, cited by Reuters).
- At the same time, the trend toward distributed data centres is requiring new equipment and supply chains.
- Crucially, a host of companies in construction, property and asset management are now targeting data centre trade.
So which stocks are poised to benefit?
As part of their research for our results season webinar, the Stockopedia team searched for companies around this theme. Here’s how they did it:
- We scanned Stockopedia’s entire back catalogue of RNS and Daily Stock Market Reports since 1 December 2025.
- The research specifically looked for references to AI and data centre clients in either the company’s own rhetoric or the market analysis.
- This scan returned 12 results. These were then analysed in depth to filter out any companies that are simply using AI internally, pushing out generic ‘AI-powered’ product copy, or plan to move into AI but have yet to do so.
- This left a final list of eight companies with real business exposure to AI and data centres right now.
Here is the final list, enriched with StockRanks, 6-month price momentum and current P/E.
| Company | Thesis | StockRank | 6m Price Chg % | P/E |
| Volex (LON:VLX) | Data centre revenue doubled to ~ $236m; high-spec data transmission cabling for Al data centre fit-outs. | 81 | 64% | 19 |
| Calnex Solutions (LON:CLX) | Network test/measurement specialist; material wins selling to hyperscalers, with data centre named as the growth market. | 70 | 14% | 40 |
| Softcat (LON:SCT) | 79% hardware sales growth from "datacentre and networking infrastructure" reseller demand as customers build Al capacity. | 75 | -10% | 18 |
| Iqe (LON:IQE) | Compound semiconductor wafers and advanced material solutions; higher-than-forecast photonics demand from Al and data centre deployments driving increased volumes. | 23 | +660% | n/a |
| Raspberry PI Holdings (LON:RPI) | Surging demand for DRAM from Al data centres is tightening supply of key components used in its microcomputers. | 51 | +90% | 75 |
| Keller (LON:KLR) | Ground engineering; North America growth attributed to large infrastructure projects "and data centres" offsetting US residential weakness. | 98 | +50% | 10 |
| Billington Holdings (LON:BILN) | Structural steel; current contracts include a London data centre, with further data centre opportunities flagged for 2026/27. | 82 | 26% | 9 |
| Computacenter (LON:CCC) | The company's latest annual forecast explicitly cites booming Al and data centre demand, while analysts at Jefferies note "the added attraction of hyperscaler exposure" on top of the company's fundamentals and competencies. | 92 | 32% | 19 |
The direction of travel is clear
You’ll immediately see that most of these companies are demonstrating positive price momentum. Now here’s how the entire basket has performed against the wider FTSE index over the past six months.
Notice that the basket began to take off at the start of March, and has gradually increased its relative strength ever since.
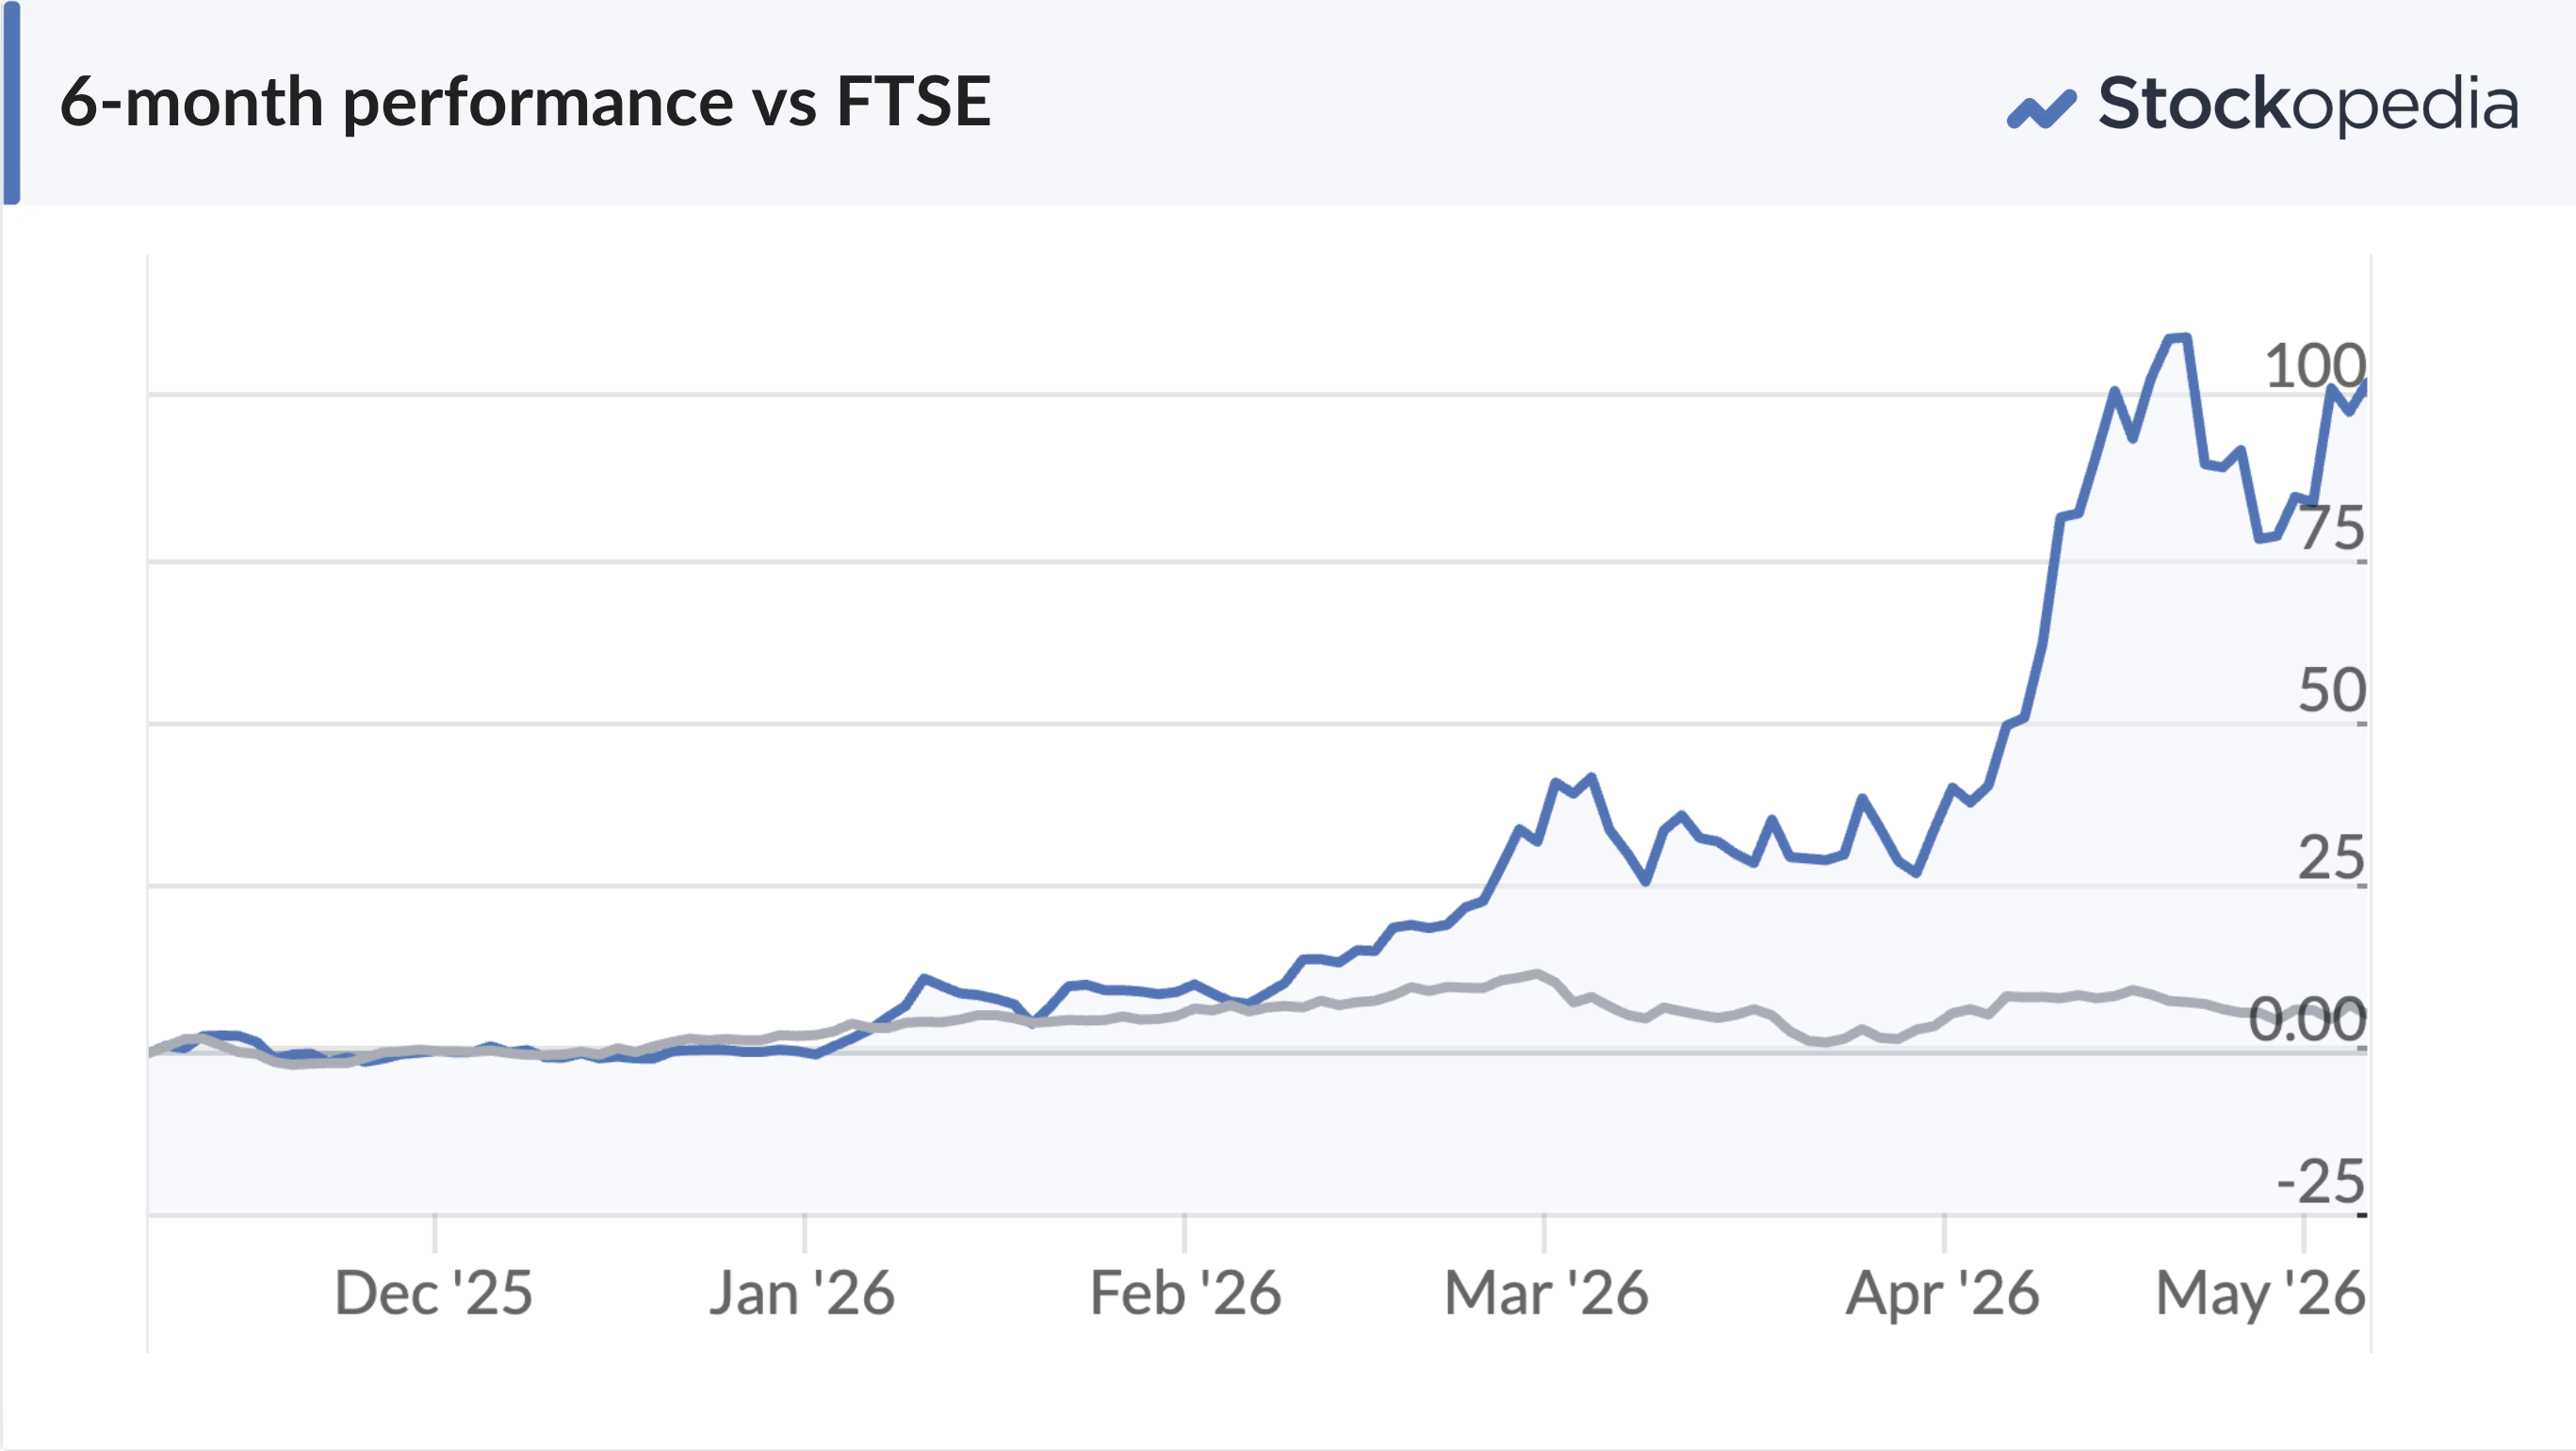
This is partly attributable to the success of two stocks at the bleeding edge of innovation: Raspberry Pi, which powers those data centres we mentioned at the top, and IQE, which makes parts for semi-conductors.
It won’t have escaped you that these two companies have the lowest StockRanks on the entire list. And while Raspberry PI is really only let down by its valuation, IQE has been on the Stockopedia RED list for a while. In December, our team noted that net debt was more than 10x FY25 EBITDA guidance, “an alarming level of gearing.”
But if you move slightly downstream, the value case improves; the six other stocks on this list have an average P/E of 19.3. That may not get value-hunters’ pulses racing, but it’s certainly favourable to the Nasdaq’s current P/E of 26.
What’s more, all of them are showing the indicators that typically drive share price growth.
- Five have posted either an earnings beat or an ahead of expectations estimate.
- Four companies have announced or continued either share buybacks or director purchases.
Now, let’s look briefly at three of the standouts
The Quality Play: Computacenter (LON:CCC)
We could have picked Keller here, but we’ve talked extensively about them extensively in recent webinars and the latest Top Stocks report. My colleague Ed Sheldon has also done a great stock pitch just this week.
So let’s look instead at Computacenter, an IT services provider that’s posted a “significant” earnings beat and an “ahead of expectations” update in a matter of weeks.
- In late April, the company said its full-year results would beat profit forecasts.
- In the same update, Computacenter reported Q1 performance “significantly ahead of prior year and expectations.”
- A core area of growth is group technology sourcing, driven by hyperscalers in Q1. The company also reports that clients have brought forward hardware orders to cope with supply shortages fuelled by the AI boom.
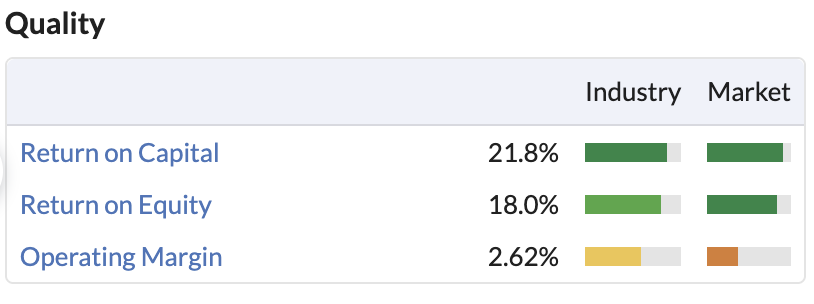
- Computacenter’s Momentum score is even higher than the Quality score (it currently stands at 99!), but we really like the fundamentals here. It’s also worth noting that net gearing is negative at -47.7%, meaning the company has far more cash than debt.
The value move: Billington Holdings (LON:BILN)
This structural steelwork company is a classic example of a ‘trad stock’ that’s jumped on the AI train. Just last month they announced a major contract win in London.
- They’re the only member of our list not to have reported a beat, a buyback or an ahead of expectations announcement in the last six months.
- However, the ‘in-line’ update announced on April 1 (alongside the data centre contract win) is itself good news after a series of downgrades.
- Commenting on that update, Roland said the guidance was “particularly encouraging” and noted the steadily rising StockRank.
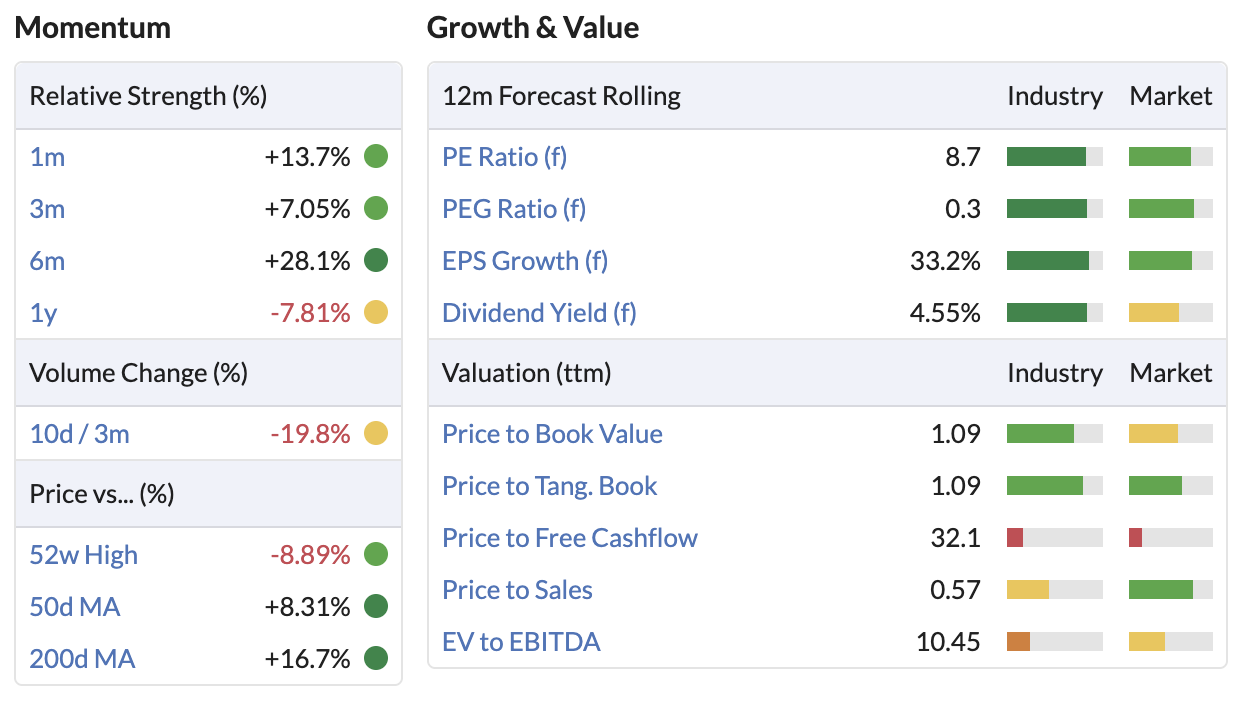
- The value case stacks up well against the other members of the list. Roland noted the “tempting” combination of quality and value in his April write-up.
The momentum option: Volex (LON:VLX)
Volex manufactures the high-speed copper cables that data centres need. And while the stock’s amazing recent performance has weakened the value case, there’s an argument that in this case, the quality’s worth paying for.
- The company released a “significantly ahead” update in March ( revenue of $1.22 billion: previous broker estimate $1.17 billion).
- AI is central to the company’s performance. Sales in its Complex Industrial Technology division are now expected to be around double the $118m achieved in the FY25 financial year (y/e 31 March) – or nearly 20% of total FY26 revenue.
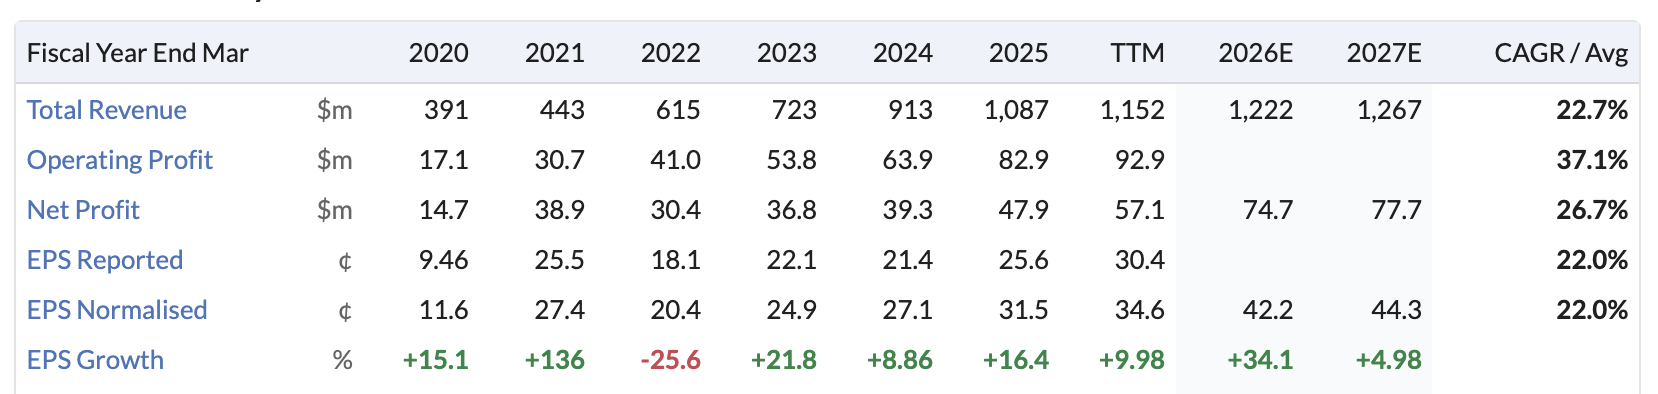
- The share price is now at an all-time high, which might indicate that the momentum is running out. However, Volex’s consistent track record (see below) suggests there may be more room to run.
- Commenting on that startling update in March, Roland suggested the valuation “remains reasonable, albeit not cheap for an industrial manufacturer.” It’s worth noting that the price has moved further north since then.
Now, over to you
Where do you think the picks and shovels opportunities lie? Give us your suggestions in the comments below. It all adds to the collective knowledge-bank and who knows, it may help someone else make a more confident decision.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

20 comments
Why faff about investing in cables etc when AI needs chips, chips and more chips, which is where the serious margin is. Memory chips only made by 3 companies: Samsung, SK Hynix & Micron they are sold out into 2027 and are simply awash with cash. Despite rocketing share prices, they are all trading on single digits PEs. The Chinese player CXMT can't catch up as Trumpy wont let them have any more ASML kit. Virtually impossible for new entrants given the capex, time, expertise required. Dell just landed an epic earnings beat but their margins compressed - because they have to pay up for chips.
What about Ceres Power? The stock is going up a lot after announcing partnership with Centrica
As a biased holder I would add Avingtrans (LON:AVG) to the list Gareth.
I have held the shares for 4 or 5 years and added to over that time. I added modestly today on the news that Adaptix Ortho350 3D X-Ray device had obtained CE certification.
Anyway, back to data centres etc. Below is an extract from the RNS referencing £10m of orders won since the start of the year. The text highlighted in bold is the most relevant. Apologies for the cut and paste, but the announcement explains the company's opportunities more concisely than I can.
"At the turn of the century, the focus was very much on maintenance and decommissioning legacy infrastructure but, in recent years, we have seen a renewed desire to develop new-build nuclear as a sustainable, decarbonised energy source. This has only accelerated in the wake of recent geopolitical instability, with countries around the world seeking to reduce their reliance on third-countries for their energy supplies.
"It is a shift that is also being accentuated by the AI and digital revolution, with data centres being built at an incredible rate, supported by US government investment and greater deregulation. While delivery of specialist cooling technologies creates opportunities for some of our businesses, data centres are also energy hungry, creating the perfect conditions for wide-scale adoption of new technologies - such as small modular reactors (SMR) - that can be scaled relatively quickly, and secure energy supplies locally, without overwhelming distribution networks.
"Avingtrans' businesses are already well advanced developing prototypes for one of the world's leading SMR companies and we expect this to be just the start of a significant increase in market activity across the industry."
Avingtrans' businesses operating across the nuclear and digital sectors include: Booth Industries (nuclear new build and fusion technologies); Hayward Tyler (nuclear new build, fusion and life extension); Energy Steel (nuclear new build, life extension and decommissioning); HT Fluid Handling (life extension and decommissioning); Metalcraft (nuclear new build, fusion, decommissioning and data centre cooling); and Ormandy Rycroft (data centre cooling)."
Two more for you. XP Power - power supplies in the ASML Lithography machines, DiscoverIE - specialist components within the server and data center build out
The other play is asset managers who have a heavy weighting to AI and tech like Polar Capital Holdings (LON:POLR) . Check out the recent performance of their tech funds!
Interview with Ben Rogoff of Polar Capital Technology Trust (LON:PCT)
?si=KWRq1WNSASrFFzn_If we're including BILN on the list then I think we can also include Tritax Big Box REIT (LON:BBOX) which is also getting into data centres, awaiting planning permission for its first one near Heathrow, and has noted that they should significantly increase its margins. 5.6% yield and 0.82x book value.
I`m no expert on this subject, but should these names be added to the list. Ensilica (ENSI) is involved in chipmaking, but is its recent performance more related to space contracts its recently made, so not sure if this should be included or not. Secondly someone suggested Gooch and Housego (GHH) a couple of days ago, and when I looked it up it seems to be in the photonics area. In the US photonics companies like Lumentum, Ciena and Coherent are up massively this year, I believe over 100% for some of these companies, so should we be looking at Gooch and Housego, or is it different. Thirdly Luceco (LUCE) is in the electric field, like Volex- I think they are doing well as a result of increased demand for their electric chargers, but could they be an AI play. Finally should we look at some of the indirect links to AI. United Utilities (UU) was quite bullish on their growth prospects due to the demand for water from data centres in their area (data centres need cooling). Also there`s the increased energy demand from data centres, but I havent seen any companies yet report on this benefitting their growth prospects, as United Utilities have done. I may be wrong with some of these suggestions, please correct me if I am, but the author did seem to ask for further suggestions and I havent noticed any yet.
I do hold Computacenter (LON:CCC) was put off for years, by the low margin but they looked too cheap in March, 26 so l bought some, already up over 1/3.
I also hold Keller (LON:KLR) have been looking to top up but they keep going up. Volex (LON:VLX) held for many years.
Billington Holdings (LON:BILN) held for a while, still under water.
I've nothing much insightful to say, except that I've owned CCC since 2022. It has a high StockRank at the time. Forward PE was quite high. Perhaps not a great idea in retrospect, but it has performed OK. I bought more in Feb 2023, when the price had fallen and the fwd PE was a much more reasonable 13.9. I thought it was a good quality company, and there was a lesson there about buying when PEs are too high. I bought a few more on Oct 2024, when the company was similarly valued.
It's interesting to observe how sentiment in CCC waxed and waned over the period. Now it has quite a high PE, seemingly buoyed up by AI razzmatazz.
I took a look at the ADVFN boards, and in March 2007 someone wrote "I am holding CCC as a Ben Graham style value play.". His entry price was 261p (cf now 3955p). Well done that man! I hope he kept his shares. Probably not, though. I think value guys always tend to sell too soon.
KLR is on my radar as very interesting, although I haven't bought. Forward PE of 10, has had decent growth and seems good all-round quality.
RPI is another company I have a tiny tiny holding in since Jun 2024. I like their products. I bought a pico with Wifi which I hope to try out soon. I had intended to top up in Dec 2024, but the shares had shot up. I decided that it was a bad time. Just as well, as the price subsequently cratered.
It is also interesting to see how the narrative has changed on this, from worries about memory prices at one point to AI hoopla at the other.
I bought into RPI because I liked their products, their commitment to innovation, and I think Upton is a smart guy. It's my kind of "next Arm". Fwd PE of 72 is eye-watering, of course, Probably best wait for a pullback if you're thinking of investing. It's obviously a high risk investment, but I was willing to throw common sense out of the window and give it a small punt.
SCT has been on my radar, too. It looks interesting.
IQE occasionally gets on my radar, but for all the wrong reasons. It hasn't made a profit since 2019, and its revenues are back to where they are in 2015. It's a total bargepole stock. It has been public since 2000 and has had nothing to show for it. It's the worst company in the list.
Thank you very much for the tip and reassuring sight of several companies already owned on your list. However I had missed CCC completely so replaced my NAPS allocation for Supreme for this better performing stock.
Renishaw isn’t about Data Center build out though, it’s more about AI in the edge and physical world automation
Also Billington also has longer term pipelines of work when NPR and Northern Arc get properly underway. Another to look at is Ampeak with its Tidal energy sites coming online over the next few years already with a significant level of direct private data centre energy supply bypassing the national grid
Been in on this thesis since last quarter after the massive capex announcements. By adding Keller, Renishaw, Hill&Smith, and AMD to my longer term holdings of Billington, Volex. Been mulling Computercentre for a few weeks more along the Sovereign Data Centre build out rather than just Uk
Excellent article Gareth.
Of those companies mentioned Keller (LON:KLR) looks the most interesting. This is because Keller “gets in early” to prepare the ground on which AI data centres sit. There is no currently Keller data centre revenue split, but if this becomes significant KLR moves from a cyclical contractor on a PE of 10x, to a higher margin “infrastructure technology enabler”, on a PE of maybe 15x. This could be a rapid transition given the US $Billion AI infrastructure buildout.
Thanks Gareth - but I would have appreciated a lot more info about Raspberry PI Holdings (LON:RPI) From the little Ive seen theres a lot more of interest to take in about this company.
Volex (LON:VLX) You have not mentioned the fact that it has just moved from AIM to the main mkt and will soon be promoted to FTSE250 - I'm sure that is partly why it has been doing so well last few weeks, as Institutional investors are attracted to it. Whereas Billington Holdings (LON:BILN) may well be passed over due to its small MktCap. And where is the pitch for Softcat ?
I was delighted to read a very in-depth article on this site, bringing my attention to RPI during the second week of April pointing out the large stake that ARM had in it. I noticed that despite some cautionary remarks institutional investors had caused a huge surge in momentum and now account for over 80% ownership alongside my own investment which began on the day I read the Stockopedia report on the company and has quadrupled since while their share price has shown no sign of slowing. Like many compamies I am invested in, without Stockopedia they would be completely unknown to me.
If you will permit a wider question that isn't directly linked to which UK companies can benefit from AI, or the AI infrastructure build, what about closer to home ?
I have noticed that quite a few people are using / posting AI to help them with some of the market decisions they are making. Perhaps more suited to machine learning than LLMs - do Stockopedia use 'AI' in order to generate the StockRanks ? It seems to me that with the database that Stockopedia has that optimisations to the StockRanks might be possible. So for instance, with current volatile market conditions the Value parameter might have a higher weighting, or that recent volatility might be more or less relevant to momentum scores. Perhaps you are developing a tool to review RNSs for an input into the SR figure ? etc, etc
I really would be interested in how Stockopedia is continually refining the Stockranks - which IMO are excellent. I dont want you to give away any IP, but I feel that sometimes the StockChat™ overwhelms the StockRanks™
I remember the discussion of whether the word 'curated' in a company RNS heralded a signficant price fall....
I’m confused by your paragraph : the quality play:Softcat . It seems corrupted in some way and doesn’t mention Softcat