PME: Defying Gravity
Today we discuss one of my favourite stocks in Pro Medicus (ASX:PME) and how it has managed to defy gravity in terms of price to know be considered the most expensive stock on the ASX.
For those unaware, PME was started 40 years ago by current CEO Dr Sam Hubert and Anthony Hall in 1983 to basically sell software to help medical professionals (particularly radiologists) manage their practices. But the business was really transformed by the 2009 acquisition of a US radiology software firm called Visage for $US3.5 million.At the time the business was worth just $115 million. Today it has a market cap of $15.6 Billion. Its headquarters are still a very humble office space in Swan Street Richmond (ps… I love that!)
With Visage they got the technology platform, a technical team in Germany and most importantly a foot in the door in America where big hospitals and healthcare groups are much easier to sell to than Australian equivalents. In fact the North America segment currently makes about ~87% of all revenues for the business.
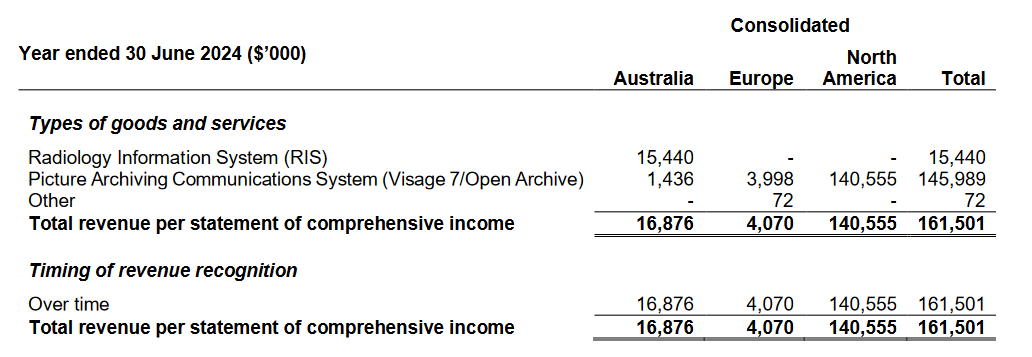
Source: PME Annual Report 2024
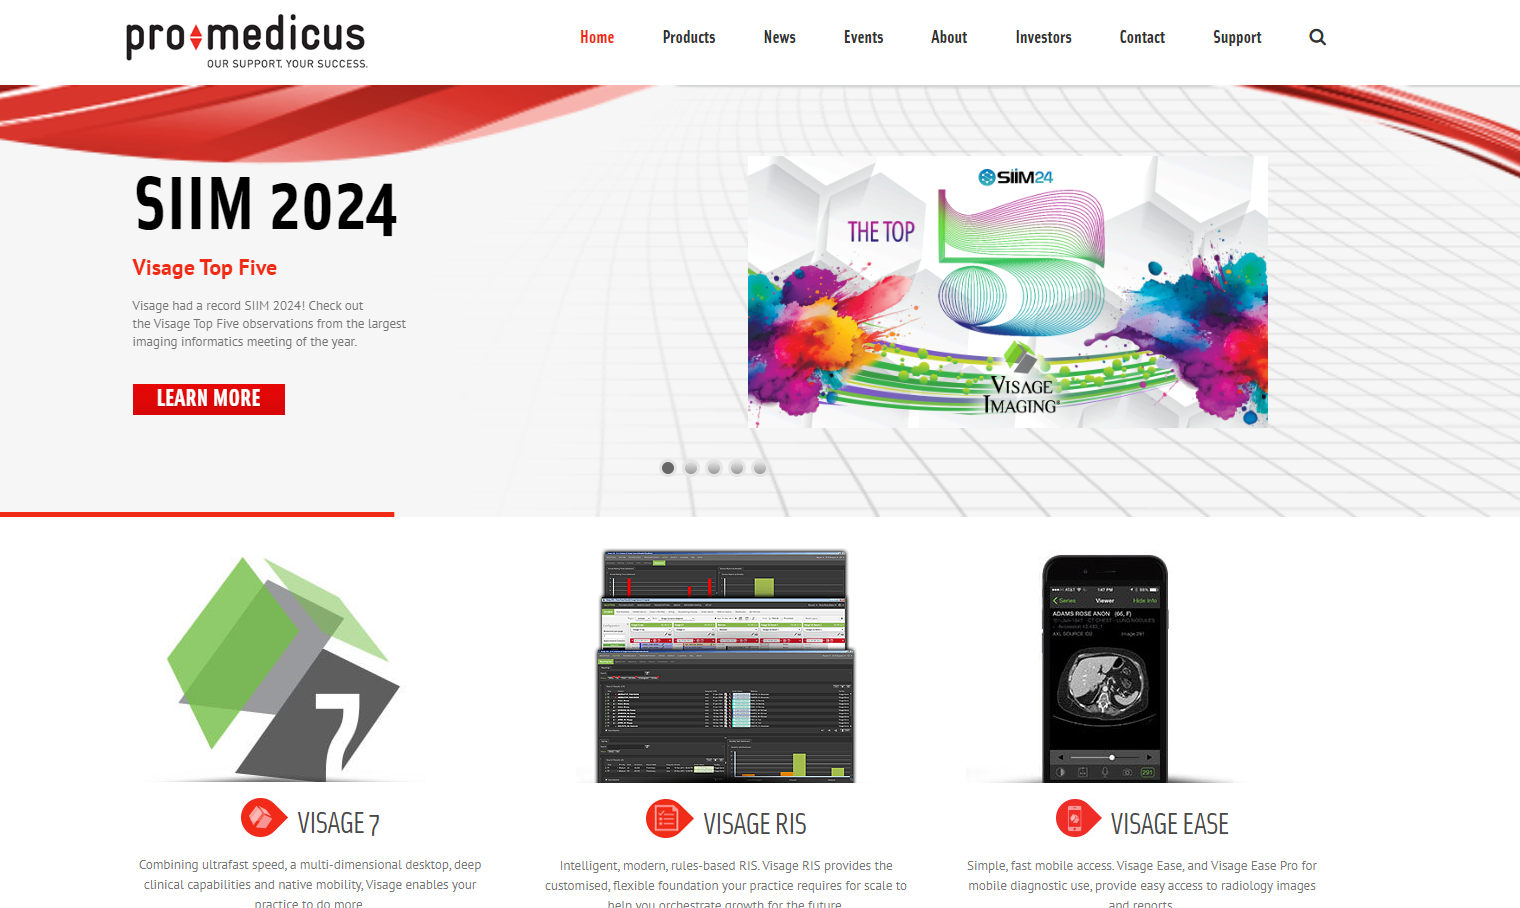
As you may have noticed from the image above, While the website looks flashy, they are still scientists at heart, no better reflected than in a fairly bland annual report that in my view is chock full of great reading, rather than pretty layouts. This includes reference to the nine contract wins this financial year, including the AUD $140 million 10-year contract with Baylor Scott and White, which was the company’s largest contract to date. The company still sees future growth opportunities there as they now service eleven of the top and best 20 US hospitals as well as a rapidly growing number of large and mid-sized Integrated Delivery Network (IDNs) and health systems across North America. They actually see this as a key target moving forward given the size. That said, they see their Totally Addressable Market (TAM) in the US is huge with capacity to manage it all if necessary.
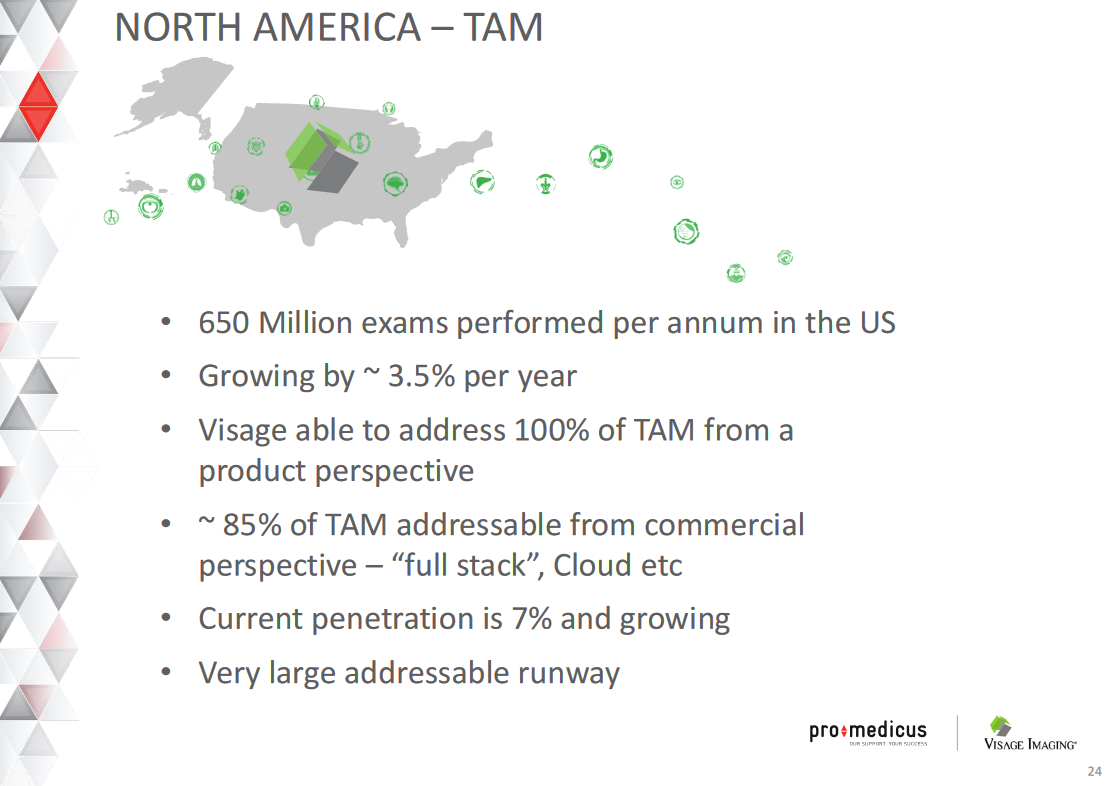
Source: PME Annual Report Presentation
In its latest result, it confirmed all that we already knew. That it is a highly scalable offering with little in the way of Hardware Capex needed. The cost base is well contained and margins are improving as footprint increases. And this is key to PME’s success, “the network effect.” The definition of which is simply a phenomenon whereby a product or service gains additional value as more people/companies use it. For example at the time of their annual report they flagged (assuming they keep key contracts - no new ones) forward revenue > A$624M over 5 years. An amazing number.
The trends that the company has sought to benefit from continue unabated. This includes exponentially larger data sets, everything transitioning to the Cloud, the need for speed, and the increasing interest in the emerging field of artificial intelligence (AI) for medical imaging analysis, technology that shows promise to improve clinical outcomes. Something the management and long term investors have seen in PME well before the recent buzz.
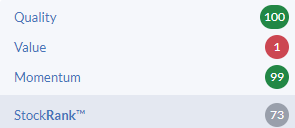
There is so much more to talk about PME and its Visage platform (Currently at Visage 7), but I will leave you to read more about the exciting opportunities that lay ahead of it. However it is fair to say that if you were taking a position today, then you are definitely paying to play. The stock is NOT cheap and therefore a full assessment of the numbers and its prospects are required before considering a position.
Quality
With a ranking of 100 it is unsurprising to see PME at the top of the pops in terms of Quality. It is a capital light business and is spitting out a lot of cash despite its spending on R&D.
First thing I will say is that the latest financials are in the system. And I know this because I can see the period ends in June and I see 2024 on the top main data column.

Try as one may, it is difficult to find anything to fault from a quality perspective. If I was running a business that looked like this I would be in nirvana (but I can invest in it…. So don’t I technically own it?)
I mean look at Net Income After taxes…

In numbers we actually see profitability today that is over 24 times what it was 10 years ago. This outstanding growth in profitability is reflected in all the company’s key numbers and at the time of writing is rated 100 from a Quality perspective.
The highest score available for Quality is supported by amazing scores in ROCE and ROE, very low Bankruptcy Risk (Debt free) and a Piotroski Score of 8. Further operating margins are incredibly strong and earnings manipulation is rated as low.

As has been stated, we have a chance to assess the latest financials and they have grown cash on hand over 5yr CAGR by 36.6%. And all this while not raising a cent from capital raisings,

Even Free Cash Flow which does consider capex has been growing consistently at 34.4% 5yr CAGR

If only all our stocks had a profile like this in terms of a number of key metrics.

To be honest less is more when it comes to this business from a Quality perspective. Suffice to say, it’s good.
Value
Now it is time to talk about the elephant in the room, Value. Or perhaps the lack of it. I can’t remember a day analysing this business where it hasn’t been overvalued. All that aside, today with a value rating of 1, it is the most expensive of businesses.
The company trades on a forecast PE of 138. It has an EV/EBITDA of 122 times and to be honest, of all the profitable companies out there, it would take a narcissist to suggest that there was value here.

Truth be known, stocks like PME (WTC and TNE can be included here) are a key reason why I have personally put little emphasis on value in recent years. It feels like spreadsheets are being adjusted just to accommodate a rising price when no one can look at me with a straight face and suggest there is value here. Whilst the company currently has a price target of $135.14, I cynically think this will be higher in six months (assuming the company continues to deliver.) Looking at the analyst recommendations most are a Hold - and probably still would be even if the stock doubled from here.

So accepting that this is a very expensive stock, one needs to accept they are going to have to pay in order to play with this quality business. The fact is as well, if you are going to dance with the devil, at times you have to expect your fingers to be singed.
I alluded to the fact that this stock was expensive when I first started analysing it. That was back at below $3. Today it is close to 50x that amount - though there have been some volatile periods in between that. Its existence reminds me of the multi-bagger report prepared by the Global team where I can point many factors discussed to this live example.
What I will say is that the current dividend yield looks putrid at 0.37%. However building on the concept of quality compounders (again another concept frequently discussed) back on the eve of the GFC the full year dividend (including Special Dividends) was 7 cents per share. Fast forward to today and once the stock goes ex-dividend on Sep 4 it will be an annual dividend of 40 cents per share. This massive increase, plus the amazing capital appreciation in that time paint a very different picture for me.
Therefore it has been an expensive stock for as long as I can remember, and the current yield based on today’s prices is negligible. But if you are able to hold your nose then there are enough long term themes to keep one interested.

Momentum
Prior to the company reporting the Momentum score was 97. Following the report it is 99.
It’s obvious when looking at a price perspective why the stock ranks highly from a Momentum perspective.

The other part of the Momentum rank is analyst revisions and as we can see under the image attached in the Value section that revisions over the last month and three months have been up on PME. Further supported by the recent profit announcement.
Looking at the EPS Graph alone you will see that there was a bump on the latest result.

However of the 14 analysts that cover the stock, most don’t have the stomach to call it a strong buy. Mainly because of the valuation I dare suspect.

Leadership
The benefits of founder-led businesses have been talked about significantly in a number of different channels. The fact that Dr Hubert still holds the CEO role and Mr Hall is an Executive Director (‘Executive’ means he is still hands on) provides faith to the true believers that extensive experience is retained within the business.
The fact they too are major shareholders still to this day also adds added comfort.

In fact I can remember back to the announcement in 2018 when Dr Hubert and Mr Hall sold down their first million shares (as they promised to the Board they would) it was stated at the time the price was an eye watering $8!!! Given the large sales that they do periodically do each year since, then one can expect them to continue to occur, And as they are conducted as block trades normally off market, to be honest, one would have to be an idiot not to accept that founders are entitled over time to realise their investment. Particularly when one considers the success of PME over the long run.
There has been no talk at this stage of either retiring, but any news on that may impact sentiment.
Outlook
As one would expect, the company is very positive about its outlook going forward.
The Directors anticipate that the 2025 financial year will see more opportunities crystallise for the Company due to improved prospects in North America for Visage 7 (PACS) and the continued commercialisation and roll out of Visage RIS (Radiology Information System).
While no formal guidance was provided, the North American business is key to their expansion hopes.

Source: PME Annual Report presentation
In the year ahead they see increased revenue coming from previously won transaction-based contracts. Further there will likely be continued strong interest in the Visage 7 expanded suite of products in the North American market (now 3 major products).
If anything, Visage 7 proves how antiquated a number of Hospital and Health places are. Their move towards the cloud and AI should benefit PME as a best of breed solution.
There is also the potential for increased revenue from Visage RIS, the company’s new technology RIS platform as the rollout of this new platform continues. Currently it is focused in Australia it will designed to take predominantly imaging businesses completely online from imaging to patient management, supporting many clinical functions.
The ultimate goal as well including the massive TAM is also the fact that the technology being developed by PME extends beyond Radiology.
Risks
As with all businesses that are lucrative and IT based, competition is a big risk for PME. The strength of the moat that the build is crucial in order to keep cheaper and newer offerings at bay. Their continued investment in technology is an essential for a business like this, with the saving grace being that given the constant advancements, each sale tends to stay a retained client for quite a while. This creates the perfect exponential revenue base.
Other than the competitive risk as stated above and the usual risks that an Audit and Risk Committee look at (eg redundancy, financial etc), the other big risk is Cyber Risk. With significant amounts of sensitive data in the cloud accessible via an open source workflow engine and Web Services, the need to protect one self through internal control measures is essential. They have employed a Chief Information and Security Office whose team is responsible for such matters. While there has been no material cyber security breaches or penetration to date, it is always a constant risk.
Conclusion
Many who have read my contributions to date will note my preference towards a QM (Quality/Momentum) investing model. From that perspective PME ticks all the boxes.
I acknowledge that this is a stock priced for perfection and it doesn’t get more expensive than this one. Therefore I appreciate and accept that it may be volatile in the future.
As a business though, in my view, it doesn’t get much better than this either. Therefore weakness may prove a good long term buying opportunity assuming there are no changes operationally. But rest assured, businesses like PME don’t come every day and therefore hoping for the price to crash will be like waiting for a bus on a Public Holiday…. It will just never come (unless of course there is a broad market collapse. But even during COVID the stock hardly fell), and when it does on a report missing expectations, it seems to rebound quite strongly.
Therefore if you want exposure to such a high Quality company in PME today you definitely have to pay to play. But in my view just like buying a first home, it was expensive to someone way back when….but today, it is negligible. If only I had a tape recorder back when the stock at $3 (yes…. They were definitely invented back then!)
Important Information: Stockopedia Ltd ABN 39 757 874 670 UK business registration number 0637267 (“Stockopedia”) is an Authorised Representative of Daylight Financial Group Pty Ltd ABN 77 633 984 773 (“DFGPL”) which is the holder of an Australian Financial Services Licence (AFS Licence No. 521404).
Information in this commentary is current as at date prepared unless otherwise stated. However, please bear in mind that investments can go up or down in value, and that past performance is not a reliable indicator of future performance. For more Important Information please refer to the Disclaimer section of this website.
This communication may contain general financial product advice. It has been prepared without taking into account your personal circumstances, and you should therefore consider its appropriateness in light of your objectives, financial circumstances and needs before acting on it.
If our advice relates to the acquisition or possible acquisition of a particular financial product, you should obtain a copy of and consider the Product Disclosure Statement (PDS) before making any decision.
The author holds interests in the following stocks mentioned in this article: PME (also WTC and TNE). This position can and will change at any time without notice.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
No comments yet
No one has commented here yet! Why not be the first one?