Portmeirion - PMP - British homewares - General Discussion

I own the stock, Do your own research. Do your own reading. Nothing is a substitute for your own research. Fact check everything.
My TLDR opinion: Portmeirion is a quality British homewares business with nostalgic brands that has been left behind in a booming stock market. The next year PE ratio is only 10 on too low broker estimates. It is a Stockopedia 'Super Stock'.

Portmeirion Portmeirion (LON:PMP) description: "encompasses six unique and established homeware and home fragrance brands: Portmeirion, Spode, Wax Lyrical, Royal Worcester, Pimpernel and Nambé."
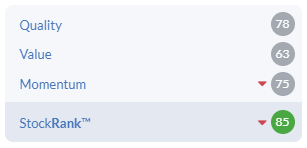
StockRank: 85; Market Cap: £82.5M; Sector: Consumer Cyclicals; Net cash: £0.7M
Price to EPS Ratio: 12; PEG: 0.656; Predicted dividend yield: 2.8%
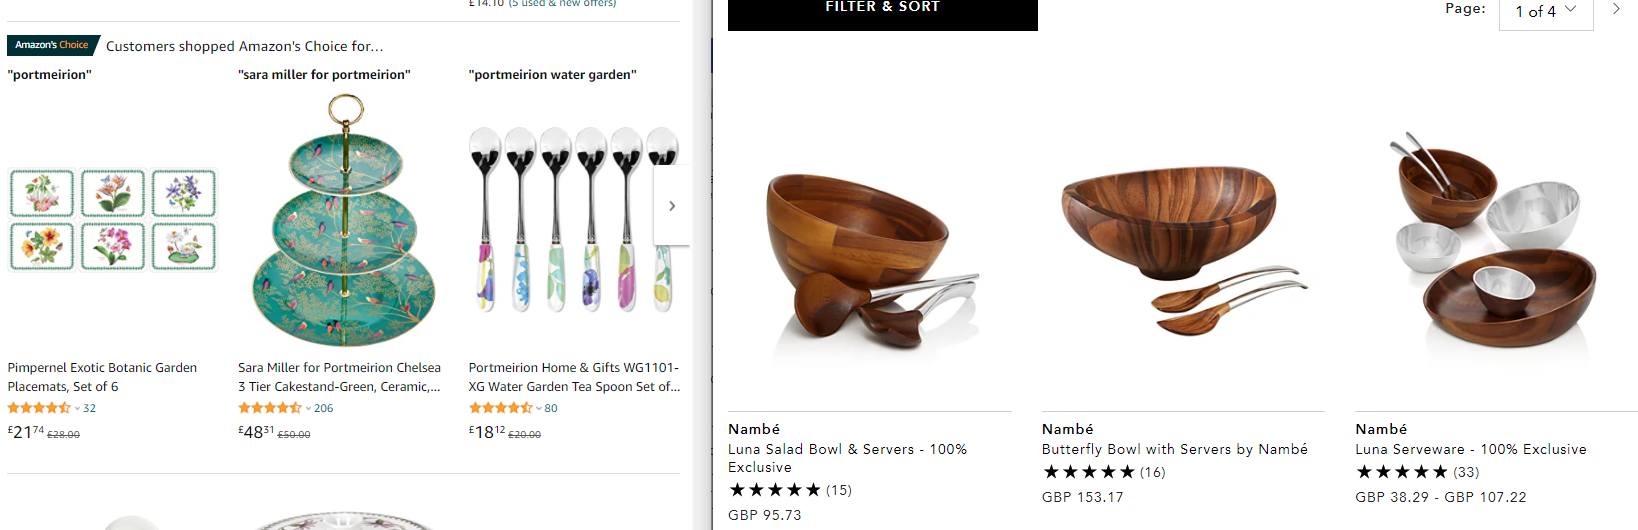
Portmeirion is a British homewares company. Their tagline is timeless design which is true because their brands have been around for literal centuries (Spode since 1770). 38% of sales are in the US, 36% are in the UK, 15% are in South Korea and the rest is in tens of export countries in the world. It did £88M of turnover last year. The brands are found in many places, like Amazon.co.uk or Bloomingdales.
Bear points
1. Brands need upkeep. Portmeirion had a fabulous track record up until 2018, but management did not innovate and systems were tired. A brand business needs investment just like Nike or Superdry and they have been neglected before. They also saturated the South Korean market before and needed two years to recover from that.
2. Portmeirion is a seasonal business and the holiday period in December matters for them. Portmeirion has a second half reliance in its business where it makes most of its profits
3. Portmeirion outsources normally 50% of production to the Far East. A big part of this is into the Asian markets but supply chains matter
4. The new strategies of online penetration and automation are immature and there are risks to them
5. Portmeirion did a big share issuance during the pandemic to give funds to renovate the business. This diluted past shareholders.
6. Portmeirion's dividend has not recommenced yet even though the CEO says one will be committed to at the end of this year
7. The pandemic hurt the business. Turnover was down 11% like for like and headline profits before tax fell from £7.4M to £1.4M
8. Legacy M&A under the previous CEO has left a lot for me to desire... The new strategy of the last 18 months from the new CEO is to improve the existing brands and grow the business organically and optimise all parts of the business and its brands.
Bull points
1. Mike Raybould the new CEO is setting the business on a new path to deliver consistent and accelerated sales growth and consistent operating margin growth. He has a clear plan for Portmeirion as I describe in my following bullet points.
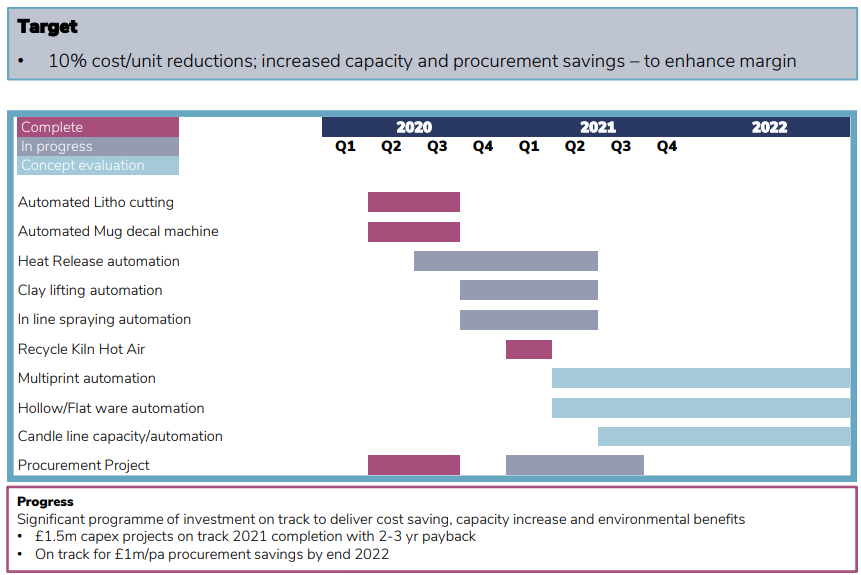
2. Portmeirion is building back better. Portmeirion is putting in place major automation schedules. New machines for pottery, for lotions, and all areas of the business are in plan. Portmeirion is automating what used to be manual processes and are more productive and flexible.
3. Portmeirion is now growing in online quickly. Its Own online is 13% of sales and total online is 47% through the UK and the US. More investment is planned into online and Portmeirion has bumped up its own online target from 15% to 20%. Even in 2021 after the pandemic, Portmeirion is managing to publish strong growth in its online channels.
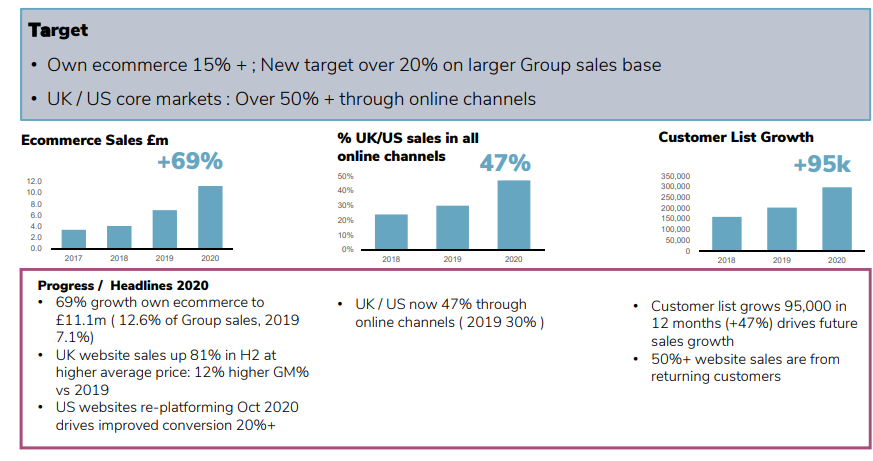
4. Portmeirion is showing a strong start in 2021. Total sales are up 34% in the interim half and are up 6% over 2019 too. This is before additional turnover made from businesses Portmeirion bought since even when there has been "continuing disruption in our markets due to the UK's lockdown in Q1 2021". 50% of sales are still offline that still has room to recover lost ground
Sales for the first half of the year will be approximately £43.0 million (2020: £32.0 million), representing an increase of 34% compared to the prior period. We were pleased to see sales growth across our three biggest geographical markets of the UK, USA and South Korea compared to H1 2020. We have also continued to see strong sales growth in online channels in our major markets. Against pre Covid-19 performance in H1 2019, our like-for-like sales at a constant currency are up by 6% (excluding the benefit of Nambé acquired in July 2019 and the remaining 50% of the issued share capital of Portmeirion Canada acquired in August 2020). Given the continued and sustained improvement in our trading, we re-confirm that we expect to resume dividend payments for FY21.
Mike Raybould, Chief Executive commented:" We have continued to trade strongly in May and June and it is particularly pleasing to see that we are achieving like-for-like sales growth over pre Covid-19 trading levels, despite continuing disruption in our markets due to the UK's lockdown in Q1 2021 and ongoing Covid-19 related global shipping and supply chain delays. This performance demonstrates the strategic progress we are making as a business, including our online and digital transformation and rest of world sales growth.
N+1 singer said
Since the AGM update, strong trading continued into May and June and the Group exits H1 with a strong global order book. Overall, 34% y/y sales growth / 6% LFL (vs H1-19) is a highly impressive outcome against the backdrop of UK lockdown 3.0 and ongoing CV19 related global shipping and supply chain delays. All this reflects favourably on the strategic progress under the new leadership team and supportive of the double-digit sales / margin recovery thesis we see playing out on a 3 year view to near double PBT on our conservative assumptions.
5. Portmeirion has earnings upgrade potential. I feel the £90M turnover forecasts are extremely under-egged. The order book for the rest of the year is good, and economies and retail are recovering from the pandemic. Villeroy and Boch's $VIB3 homewares segment continues to boom too.
Portmeirion was trading 6% above the like for like 2019 before pandemic figure for the first half. In 2019 they did £93M of revenue. In the first half of this year the acquisitions of Nambe and Canada brought in another £6M of turnover I work out so I double this to £12M turnover for 2021 as a whole.
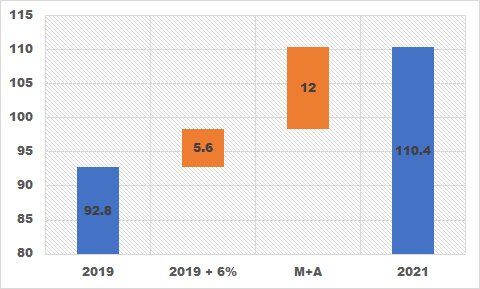
Forecasts have been going up for many stocks this year and Portmeirion's need to go up. This shows how I get to a £110M turnover forecast for 2021 that is 20% more than N+1 singer are expecting. This would be even more revenue than N+1 singer expect Portmeirion to do in 2022 .
6. In 2019 which was not a very good year for Portmeirion the ROE generated was a very respectable 12.1%.
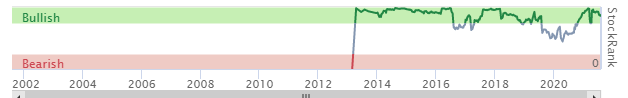
7. Portmeirion has been a high ranker on Stockopedia for most of its life
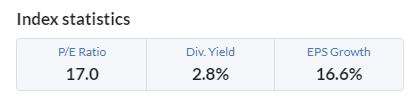
8. On the EPS normalised shown on Stockopedia, Portmeirion is valued on 15.9 turn 2021 EPS normalised and only 10.3 turns the 2022 EPS normalised. This is far below the market levels of valuation from only 5 months time because the EPS normalised growth for Portmeirion is expected at 55% for 2022 compared to the market only at 17%
However I think it gets better because as I showed up the forecasts from N+1 singer are seriously under-egged. This to me means that Portmeirion could be on a single digit PE ratio. Paul Scott said in his last SCVR on Portmeirion
My opinion - unless I missed it, this update ducked the important point of specifying how PMP is trading versus market expectations. This should be explicitly stated in every trading update, from every company. With a footnote to give the figure for market expectations. That said, there seems enough positive commentary in this to imply that it’s trading at least in line.I like the turnaround here under the newish CEO, and the focus on online sales is important. Other problems seem to have been resolved too. Overall, I think the valuation seems reasonable, possibly even cheap, if the full year numbers are hit - dependent on peak season in the run up to Christmas.
Paul sees that he thinks the valuation here is reasonable, and maybe cheap if the full year numbers are hit. I showed that I think the estimates are instead too low and not difficult at all to achieve. Estimates have not yet moved
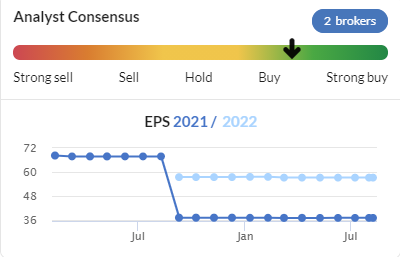
I think the right PE ratio for Portmeirion is 15 turns 2022 EPS normalised. The N+1 Singer forecast would put that on a 855p stock price and I would say that their EPS normalised estimate is too low.
Jack Roland
I own Portmeirion (LON:PMP), Do your own research. Do your own reading. Nothing is a substitute for your own research. Fact check everything. I also own Panoply Holdings (LON:TPX), Getbusy (LON:GETB), Synthomer (LON:SYNT), Gulf Marine Services (LON:GMS), Creightons (LON:CRL) and more
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
10 comments
PMP remains one of my favourite mid term shares. I believe they are (finally) getting their online act together - they sell gifts, collectibles and sets so perfect for this way of selling and at much better margin. Internally, automation in the 50% of production that is UK made is also helping .
However, short term I am looking at H2 sales and the current shipping costs from the Far East.
Assuming, 50% of £60Mn sales in H2 is from Far East, $15K cost/per container (vs $4K pre COVID ie +$11K), I get a cost increase of £2.5Mn. This will require price increases of 8% to cover.
I am confident in topline - but what do people think about the profit line. If there is a miss, on such a thinly traded share, the price could tank again.
Also does anyone have insight into how the the new lotion products are doing?
Hello Peter,
that's an interesting scenario,
I agree that a miss is being punished heavily at the moment. Even the danger of a miss seems to be punished - sadly for me. Like you I see a lot of potential in Portmeirion (LON:PMP) and have been buying steadily from around 350p a year ago. It's now one of my top 5 holdings.
A £2.5m hit to the current forecasts would halve the profit, to 2.6m and the forecast eps from 38p to 19p. I can imagine a severe reaction if that were too happen. But how likely is it?
It's not something I've figured in. But maybe I am being too complacent?
I've no doubt there will be an impact from shipping - but what size it will be and whether they can pass all or most of it onwards I have little idea?
I don't know how much they have to import from the far east - or how much gets re-exported. It was 50% sourced externally a few years ago, but since then the UK manufacturing capacity has been increased and Wax Lyrical and Nambe acquired. But product has to be exported as well, so I'll go with 50%.
At $11k increase per 40ft container additional cost - that would be 303 containers (equivalent) for the 2.5mGBP increased cost - or roughly 100k GBP goods per container spread over £30m? I'm surprised the value of goods shipped per container is not a bit higher? Did that figure come from the company? I can't find it. Knowing nothing about shipping fragile pottery a rough calculation leads me to think it could be £200k - £250k value goods per container? The upper end of that would bring the increased cost down to £1m - which is still significant but perhaps more manageable? Maybe a reasonable best case? But as I say - I don't know anything about shipping pottery.
According to the Statista global east-west chart - the price last week for a 40ft container was a record breaking $10.8k. That's a shipping average. Probably late bookers are paying a lot more, and I've heard some horror stories. The rate at the start of the year was around $4k, and in 2020 depressed by the lockdowns it was below $2k for most of the year. Average increase in price is $6.7k or £5k at current exch rate. That would bring the £2.5m down to £1.5m - or the £1m down to £600k?
And thats assuming all of the shipping is at the current peak rate - it might be over the range from $4k to $10.8k depending upon when it was booked and shipped ? An average would be a best case £300k cost increases. Which is starting to look a little bit too optimistic even to me - but it helps to show the range of outcomes?
£600k would be quite a miss if they cannot pass on any price increase - and happen to be just on the forecasts.
That is possible - but I don't think its the most likely outcome. Nor do the Board taking their H1 outlook statement from a couple of weeks ago,
We are cognisant of the ongoing, widely reported disruption and volatility in
global supply chains, including labour shortages, container shipping delays and
significant market price rises in container shipping rates all of which impact our
business. We have taken and will continue to take mitigating action where possible,
expediting stock shipments, building additional raw material and finished goods
stock contingency, reviewing our own selling prices.....
If they'd been looking at a possible miss just a couple of weeks ago I'd have expected the usual downbeat 'unprecedented' blah,blah,blah, can't tell, blah,blah,blah. But they are pretty much saying that they can handle it as it is at the moment?
The broker specifically resisted upping the forecast after the H1 beat - on the basis of costs rising - but noted that risk is to the upside.
Like I said - perhaps I am being complacent. If so, perahps it's because I don't intend to sell even if they do miss their forecast, as I don't see this affecting the longterm growth. However - it will be fascinating to see how it turns out?
By the way - I am thinking that the current price is around the peak for freight on the basis that by October all the freight slots for delivery by new year are booked. I expect the increase to slow, and possibly reverse soon as booking moves into the new year and the capacity bottlenecks around containers, ships and ports eases. But what do I know? Anecodotally - looking over to the Isle of Wight from the South Downs above Chichester last week there were over a dozen container ships waiting in the sound. That is certainly unusual.
Playing devils advocate in return - have you considered the cost of gas prices rising on their cost of running the kilns? That might be a bigger issue than the freight costs?
I am often guilty of over-optimism, and right at the moment that's not turning out to be such a good things, so please treat my ramblings with caution that they deserve,
cheers
Mark
Mark, Thanks for the response. I have the same view.....of the ships waiting on the Solent out of my window in Southsea!
Being serious and returning to Portmeirion (LON:PMP) ...
1. Re Containers - some is my own research but I was spooked into the calculations by Paul Scott's note on the main SCVR (which is where I sourced the $100K/ PMP container). I also expect the shipping cost to drop right back in a few months as shipping gradually sorts itself out. (At present, not researched, but the shipping container building business must be doing well!) The 50% from Far East was the last figure I had from an annual report although I believe they were already looking to diversify to Portugal, Turkey etc as well as build the UK. (I rate the new CEO - he is delivering change + positive progress). Net, my 2.5Mn is probably worst case but would be material!
2. Re Kilns - I had thought about them but have no sense what % of COGS they would be. I also believe cost increase would apply to 100% on volume ie incl suppliers but be greater on UK internal production. Let's hope they are hedged.
3. Other costs - Labour and all other costs will have been/will be rising - so a lot of pressure.
All said, I am holding and inclined to buy more (see my posts below) if it does spike down. But my best guess is that that we will get a good sized revenue beat whose benefit is eaten up buy costs delivering the current profit forecast.
We will see.
Hi Jack.
Good discussion of the Portmeirion (LON:PMP) investment case. I’ve added it to the index of company discussion threads. You may want to edit your title to include the phrase „general discussion“ to follow the format being used for other companies/encourage others to use this thread to post discussion on this company.
Gus.
Thank you, I will edit the title after a day or two so it can become a general discussion board
Title changed. Thank you Gus
Thanks for setting out separate Portmeirion (LON:PMP) article. Low profile, under-researched companies like this are probably where we as PI's have the greatest chance
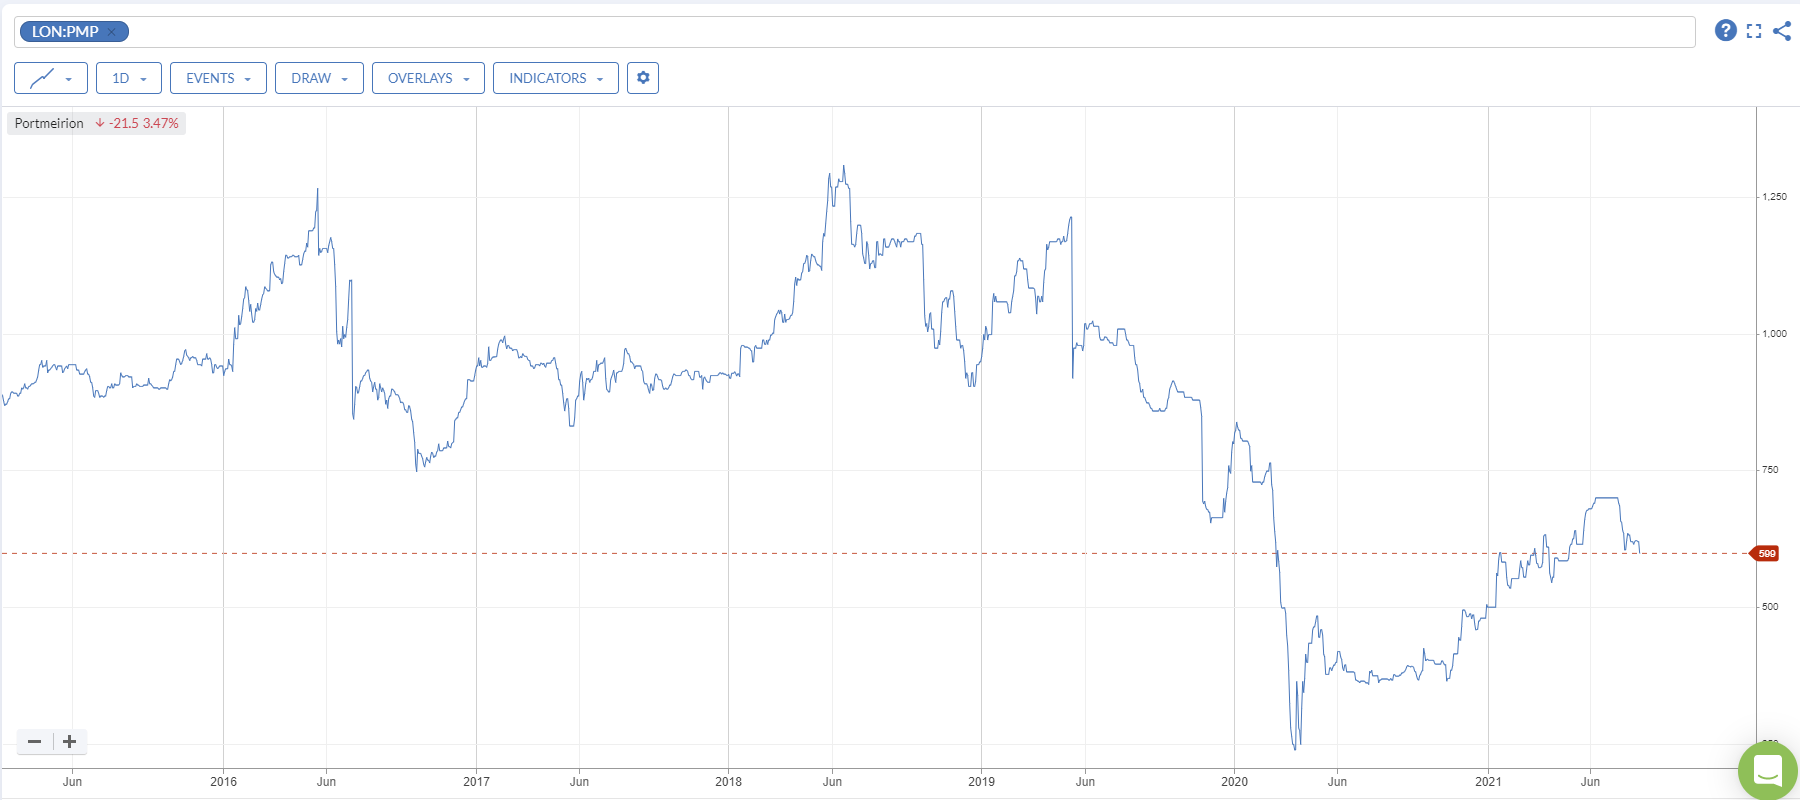
I wrote the note below into the SCVR column on 14 July. Copying it to here to build discussion and points of view on PMP. Since I wrote the price has fallen to 595p today but I have not changed my positive view as I am not aware of significant new news. Stock is so thinly traded even I might 'move the market' some days buy buying a few thousand pounds worth of shares!
By far and away the biggest positive for me is the improving execution of online, given it really is a gift (including self-gifting) and homewares business since so much revenue comes from things like the Christmas tree Spode and (I judge) from initial one-offs like cakestands.
The new hires made in last 12-18months really seem to be making a difference here with new products better linked to gifting occasions and promoted more effectively on digital. Look at the evolution of Spode away from only blue on white designs (outside Christmas).
This business is better margin, should offer repeat sales potential and has a natural tailwind behind it.
(From my note on SCVR 14th July)
In recent years, PMP has underperformed having acquired 2 sizeable businesses (Wax Lyrical in 2016 with £12Mn sales and Nambe (£13Mn) in Sept 2019 but not seen even this T/o gain come through. Arguably, +6% LFL vs 2019 base business is not exactly stellar but….
Equity raise in 2020, diluted cheaply but did strengthen balance sheet and enable what I think have been good uses of cash for the long term
In short, reasons to be cheerful on profit as BOTH topline and % margin should be improving (evidenced by resumption of dividends is confirmed although this was expected).
Crucially, this is occurring when the share price is 640p vs 925-1200p range in 2017-19. A 22% dilution in 2020 occurred so perhaps 780p vs 925-1200p is better comparison). (Reworked as 640p vs 758-983 ie 16-50% less) (EDIT at 10th Aug now down to 595p)
The business is much better now than 2019 but I was prepared wait for end of ’22 for good news to come through.
Now I think the FY2021 results will be very good and a catalyst for a significant re-rating. I would now be disappointed if we don’t see 1000p again by Feb ‘22 (ie +50% vs today excluding dividends). I've bought more this morning.
Thank you for sharing your helpful thoughts. I agree with much of what you have said. The CEO has held some investormeetcompany sessions which are worth watching too
On linkedin they show the new wax lyrical investment is now up and running with first pours this week with the handcare and lotion ranges going online and in store from September
hi ZipmanPeter. I read back your post again and one element to point out. You said "smashing the current analyst forecast of £99Mn". The 2021 forecast is £90.1m and 2022 is £99.5m
Just seen your correction of my typo - you are right. We followed much the same logic and arrived at roughly the same figure and thus conclusion.
I am now debating how brave to be since, whilst I am not predicting life changing gains this is probably my highest conviction share and it it is in its lull phase - unfollowed outside reporting periods, with v low trading. My position size is already large (for me) but I will definitely buy more if it trends down.
BTW - great to set up a specific company thread like this.
Peter