Post Covid Switch to EVs - Nickel Demand Increase and Supply Shortages (Mining) (LON:AMC)

At over $20 billion dollars a year, nickel is already one of the world’s most important metal markets. However, with the rise in demand for electric vehicles, nickel is potentially on the cusp of a fundamental supply shift where quality over quantity comes crashing to the fore.
That’s because not all nickel is created equal.
Approximately 62.4 percent of today’s nickel supply is nickel laterites, which produce products such as nickel pig iron and ferronickel. While abundant, these low-grade metals are inadequate for battery manufacture. Instead, the growing demand for EV battery components must be met by higher-grade––but much rarer––nickel sulphides, which produce such products as nickel metal and nickel sulphate.
- Only 15kt of nickel was sourced from finished (Class 1) nickel in 2017; a single Chevy Bolt features 23kg of nickel in its battery.
- Future battery chemistries are expected to contain more nickel, not less––comprising up to 80% of the battery cathode mass used by companies like Chevy and Tesla by 2020
- Source: Nickel: The Secret Driver of the Battery Revolution
Class 1 nickel (high purity) and Class 2 (lower purity) nickel and sulphide ore versus laterite ore
Class 1 nickel is the high purity nickel that is used in electric vehicle lithium ion batteries. The stainless steel industry uses both class 1 and class 2 (lower purity) nickel, and is the main driver of nickel demand.
The nickel sulphide ore deposits are the better source for class 1 nickel needed to make nickel sulphate for EV batteries, and typically have significantly lower production and CapEx costs. Class 2 nickel from nickel laterite ores can be converted to nickel sulphate however it requires high pressure acid leaching [HPAL], which is expensive with much larger CapEx requirements. Much of the laterite ores come from the rim of fire regions such as Philippines, Indonesia [PNG] and New Caledonia. Most of the sulphide ores come from Russia, Canada, and Australia.
McKinsey state in their November 2017 report, The future of nickel: A class act (emphasis added):
"Currently, class 1 nickel supply suitable for battery production represents approximately half of global supply of 2.1 million metric tons [MT] – although only 350 metric kilotons [KT] is available to be processed into powder and briquettes that could be used to produce nickel sulphate (in 2017 approximately 65 Kt to 75 Kt of nickel content will be used to make nickel sulphate). With annual EV production expected to reach 31 million vehicles by 2025, demand for high-purity class 1 nickel may increase significantly from 33 Kt in 2017 to 570 Kt in 2025. This comes on top of class 1 demand from traditional end-use segments i.e., plating, foundry and super-alloys. A shortfall in class 1 nickel production seems increasingly likely as current low nickel prices do not support class 1 nickel capacity expansions and alternative strategies e.g., shifting existing production from nickel cathode to nickel sulfate or refining nickel intermediates, seem unlikely to provide long term solutions. As a result, not only will nickel prices likely need to move towards incentive pricing but the future pricing mechanism is likely to reflect two distinct nickel products: class 1 and class 2.
A shortage of class 1 nickel will likely see pricing revert to incentive pricing levels required for the introduction of new capacity or the reopening of mothballed capacity. These incentive pricing levels will need to be above current nickel prices and could increase significantly if the supply-side response is slow. At the same time we expect to see two distinct nickel price mechanisms emerge reflecting two distinct commodities: class 2 nickel, primarily for use in stainless steel production, trading at a lower price that reflects its abundant supply; and class 1 nickel trading at LME prices – or above for high-end nickel powders and pellets used to make nickel sulfates – reflecting required incentive prices.
The key thing to understand here is that the nickel sulphide ore miners have a distinct cost advantage when producing the nickel sulphate required for EV batteries.
This is where I think Amur Minerals (LON:AMC) fit in https://www.stockopedia.com/share-prices/amur-minerals-LON:AMC
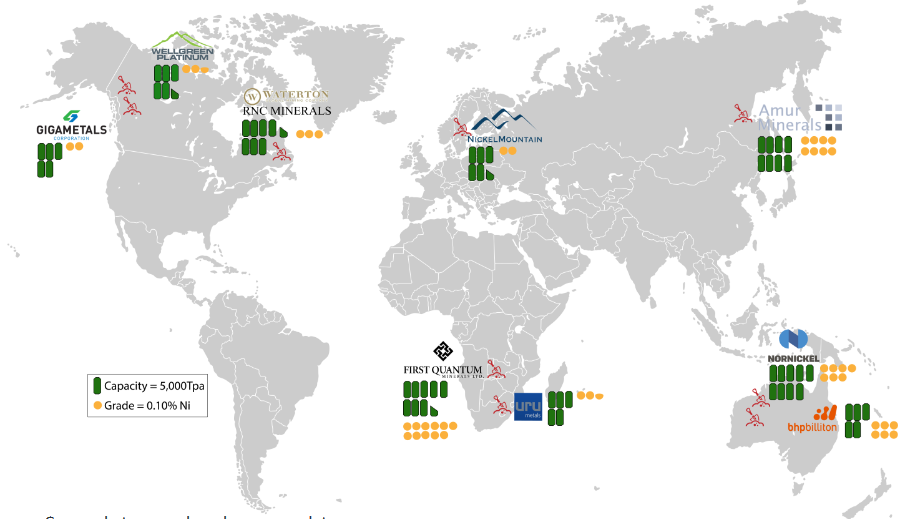
They are sitting on 1.58 Million Tonnes of Class 1 Nickel and one of the Top 9 known Nickel Deposits in the world and currently sitting with a pretty small market cap and current share value considering the shear scale and quality of their asset.
See below map.
Nickel outlook - demand v supply
Demand
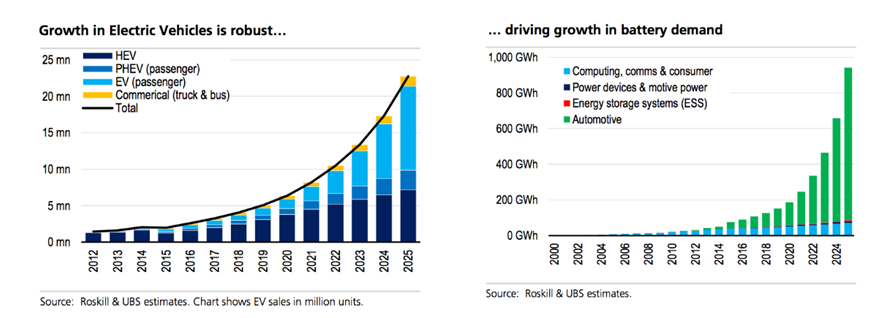
By far the main demand source for nickel is stainless steel. This means nickel demand will continue to be driven largely by global construction demand, still led by China for now. However, what is significant is that increasingly new demand will be driven from lithium-ion battery demand, fueled by growth in electric vehicles and energy storage.
My modeling shows the following effect of EVs on nickel demand
| number of electric car sales pa (% market share) | Nickel (tonnes pa) required pa for electric cars | % of total nickel demand | |
By end 2020 | ~5 million (5%) | ~180,000 | ~7% |
| By end 2025 | ~17 million (15%) | ~620,000 | ~17% |
| By end 2030 | ~40 million (30%) | ~1.4 million | ~26% |
- Assumes that by end 2020 light electric car sales can reach 5 million pa. Based on 36 kgs of nickel per electric car that equates to 180,0000 tonnes pa of nickel required to feed electric cars in 2020, or about 7% of total nickel demand up from almost zero in 2015.
The message here is that nickel demand from surging electric car sales will start to become significant by 2020 at ~7%, more important by 2025 at ~17%, and very significant by 2030 at 26%.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
11 comments
I posted on here earlier complaining about the article writer ramping this share. This seems to have been removed for some reason so I need to re-iterate that anyone reading these posts should also do their own homework before investing in small mining companies like this. Its disappointing that the OP is being allowed to continue ramping this without being challenged
S/he appears to have TWO threads running in which they continue their daily ramping of this stock. They appear somewhat argumentative on the advfn thread for this stock.
It used to be that if posters were starved of oxygen by no one responding to their endless talking to themselves they eventually desisted, but that appears no longer to work :(
Ah - two threads....cunning ;-) While I like the light touch approach that all the other high quality threads and responsible posters thrive on I have just reported these two threads....
59% of Stockopedia community own shares in AMC.
I post articles that suggest that their choice to invest in AMC could be well placed given the impending switch to EV on a massive scale, forecasted Nickel deficit that will come with that and rising Nickel price.
People are advised to do their own research. I have posted about this share since it was just over 1p. If people invested at that point they would be more than double their money in a short period of time.
I always advise DYOR. People are smart enough to make up their own minds. I post the backup to the articles I come across for them to read themselves and make up their own minds.
The Nickel charts were looking very bullish today breaching the $14k per tonne mark.
As predicted, heading upwards in line with the growing demand.
European battery gigafactories boom despite Covid slowdown
The region is on schedule to meet rising demand for electric vehicles, with five major battery factories in operation and at least 11 more expected by 2030
While Covid-19 has brought many industries to a halt, plans to build large-scale battery gigafactories across Europe have remained largely on schedule, according to market analysts.
https://www.climatechangenews.com/2020/07/27/european-battery-gigafactories-boom-despite-covid-slowdown/
Nickel up at $6.2, Elon / Tesla looking at big nickel plays, AMC looking at binding off-takes, TEO on track, majors in acquisition phase, AMC currently performing due diligence on investments to prevent coming back to shareholders.
https://thedriven.io/2020/07/2...
‘Please mine more nickel,’ Musk said. Tesla will give you a giant contract for a long period of time if you mine nickel efficiently and in an environmentally sensitive way.’
“By 2030, we forecast nickel demand from the batteries sector to account for a little over 25 percent of the total nickel market,”
Despite the economic weakening due to the COVID-19 pandemic, Europe and China have strengthened their EV subsidy programs and maintained their CO2 and EV targets, which Roskill believes will continue to support EV adoption and therefore nickel demand from the battery space.
Many of the nations from the Western World have adopted pro EV incentives in light of the improving world environment under lock down.
With AMC's huge Nickel deposit and future mine being lined up to come into production in the next 3-4 years, this would be ideal given the forecast rise of the EV Market.
https://investingnews.com/daily/resource-investing/base-metals-investing/nickel-investing/roskill-partial-demand-recovery-support-nickel-prices-h2/
A very good and interesting interview regards the forecasted Nickel deficit and expected surge in price.....giving Mining companies a huge advantage.
https://www.cruxinvestor.com/videos/7-nickel-ma-picking-up-time-to-pick-your-winners---mark-selby
EV Metal Miners Should Soon Follow The Electric Vehicle Manufacturers Recent Stock Price Surge
https://seekingalpha.com/article/4359517-ev-metal-miners-should-soon-follow-electric-vehicle-manufacturers-recent-stock-price-surge?mail_subject=matt-bohlsen-the-ev-metal-miners-should-soon-follow-the-electric-vehicle-manufacturers-recent-stock-price-surge&utm_campaign=rta-author-article&utm_content=link-1&utm_medium=email&utm_source=seeking_alpha
Conclusion
The past two weeks has seen some very early signs of an EV metals rally to follow the massive rally enjoyed by the EV manufacturers. I did suggest to buy Tesla back in June 2019 at USD 196.80 and today I am saying it a great time for investors to start buying the quality EV metal miners.
Mainstream investment articles have only just now started to appear using phrases such as "where Tesla goes, lithium will follow." This will likely continue in the months ahead, or once the EV metal miners stock prices start to rise.
Given the past 2 months surge in the EV manufacturers it would follow that investors may soon bid up the EV metal miners for fear of missing out (FOMO). The Chinese are already doing this now.
My view is that a significant EV metals miners (lithium, cobalt, graphite, nickel, rare earths, manganese) price rally will happen between now and end 2022, as EV demand surges due to cheaper EVs being available globally starting in 2021/22.
Some background on AMC and it’s current position and progress towards bringing their asset into production and mining that much needed Nickel....
https://www.stockopedia.com/co...
This is a very interesting video from the highly impressive Adam Habib, mentioned in the above article. Adam is charged with securing the financial side of things and bringing the mine into production.
;feature=youtu.beIt should be an interesting 6-12 months for AMC.