Quartix Technologies: a high-quality business with a share price stuck in traffic

Over the past month or so, we have been looking at quality stocks on Stockopedia. I recently wrote an article on why I think this strategy may be due for a comeback.
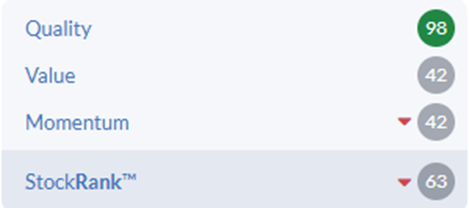
One quality stock that continues to interest me is Quartix Technologies (LON:QTX). The share price has dropped 27% over the last year, which would normally indicate weak financial performance from a business. With this price action, it is unsurprising to see a Momentum Rank of just 42 and dropping:
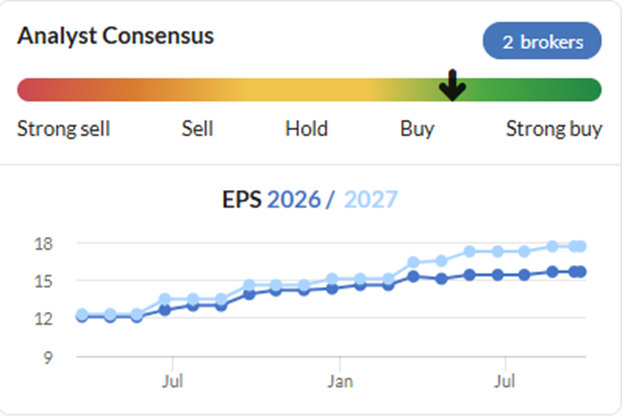
Yet this stands in stark contrast to the broker consensus, which has seen continual upgrades during this period:
Which signal should I listen to: the share price or the broker trend? I've written a Stock Pitch article to find out.
Disclosure: At the time of publication, the author does not hold a position in Quartix.
The Pitch
Quartix Technologies (LON:QTX) is an AIM-listed, Cambridge-headquartered telematics company that has provided subscription-based vehicle tracking since its founding in 2001 by Andy Walters, who returned as Executive Chairman in September 2023 to refocus the group entirely on organic growth in its core Fleet subscription business. It designs, manufactures and sells tracking hardware and software to small and mid-sized commercial fleets (average size around 10 vehicles) across the UK, France, Italy, Spain, Germany and the US, serving 33,600 customers and 342,700 vehicle subscriptions. Walters remains the largest holder with 22% of the equity.
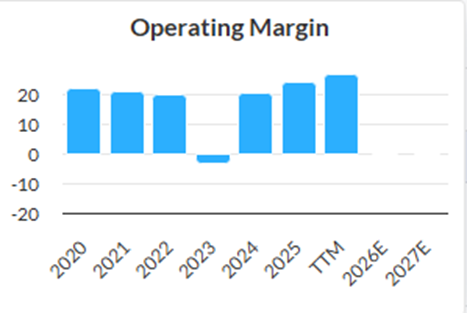
Its Quality Rank marks it as a company to watch, coming in at an impressive 98. Apart from 2023, when the company saw its statutory results marred by a non-cash provision relating to the replacement of all 2G units with 4G units in France and a non-cash impairment of the goodwill from the acquisition of Konetik, the company typically has an operating margin above 20%:
And a ROCE in the mid-20s:
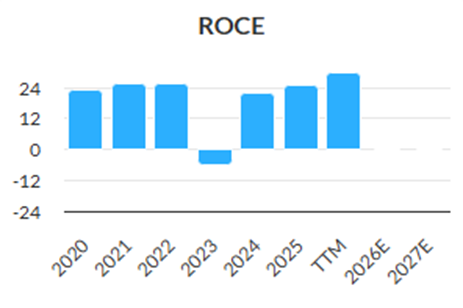
These figures have been increasing recently. Together with an expanding gross margin now above 70%, this suggests the company has a deep and widening moat.
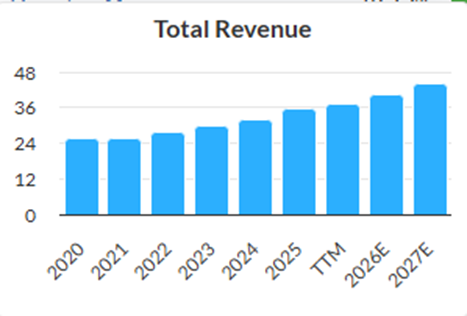
The bigger challenge has been in making the most of that competitive advantage and growing the business. At around 7% CAGR revenue growth, the increase has been steady but unimpressive:
There has also been little operational gearing, with EPS growing about the same rate as revenue:
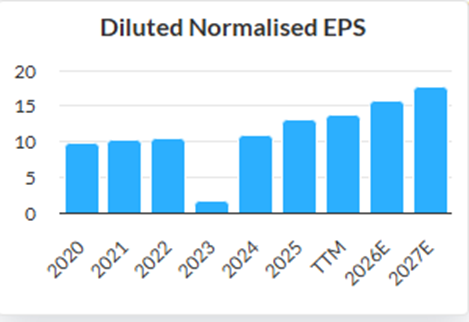
However, there are signs of improvement going forward, with EPS forecast to have grown almost 20% for the second year in a row. If this performance continues, the stock will quickly grow into its 14x forward P/E and more.
The Big Picture
Quartix has several features that mark it out from the average UK small cap:
- A genuine long-run compounder: aside from the 2023 misstep, ROCE has held in the low-to-mid 20s for five of the last six years and now stands at 29.7% TTM. This kind of sustained capital efficiency is rare and allows the company to pay a dividend approaching 5%, despite consistently growing earnings.
- Recurring, sticky revenue: subscription revenue made up 98% of H1 26's £19.4m, and net revenue retention has climbed from 93.0% in FY23 to 98.1% in FY25, with customers typically staying around seven years.
- Real operating leverage: H1 26 adjusted EBIT grew 21% yoy to £4.9m on revenue growth of just 12%, taking the adjusted EBIT margin to 25% from 23% in H1 25, with ARR per employee up 11% to £220k.
- A fragmented, consolidating market: Quartix holds an estimated 2% of its c.21m-vehicle addressable market, in an industry seeing consolidation from deals such as such as the Geotab/Verizon Connect and PowerFleet/MiX Telematics tie-ups.
- A genuine service moat: a 4.8-out-of-5 Trustpilot score and Fleet News' Recommended Telematics Supplier award for both 2025 and 2026 testify to Quartix's ability to push through inflation plus price rises with minimal impact on attrition.
Going Deeper
Annual Recurring Revenue is management's preferred gauge of underlying momentum. This will lead reported revenue and, in turn, profits. Several near-term catalysts could positively impact this metric:
- US acceleration: US ARR grew just 1% yoy in H1 26, hit by higher churn. However, a new, cheaper OBD tracking device is due to reach full production from August 2026. The success (or not) of this tracker is likely to prove the single biggest swing factor in the near-term numbers.
- A UK order backlog: UK ARR growth slowed to 7% yoy in H1 26 after briefly achieving over 100% net revenue retention in FY25, due to slower field-sales conversion. However, management points to a strong backlog into H2.
- Dashcams going continental: Dashcams have added over £0.5m of UK ARR since a March 2024 launch, and Quartix are due to expand this into continental Europe in H1 27. They aim to push Net Recurring Revenue there toward UK levels.
- A cheaper box: the new TCSV17/18 hardware generation is roughly £8 cheaper per unit than its predecessor, targeting a full-production unit cost of c.£30. This has driven gross margin up to 73.2% in FY25 from 69.4% in FY23, and the return-on-capital trend is holding up as the business scales.
- Ownership structure: founder Andy Walters holds 22.4%, with fellow founders, Andy Kirk and Ken Giles, plus institutions, making up the bulk of the remaining holders. This is about the right holding level for a founder as far as individual shareholders are concerned; enough to give him real skin in the game, without opening up the possibility of unilateral actions that are not in the interests of all shareholders, such as delisting.
What The Brokers Say
Some sources suggest that Canaccord covers the company. However, only Cavendish is listed as a broker on the company's website, and this is the only recent research I can see on Research Tree. Cavendish's latest note was published in July, accompanying the H1 results. This reiterated FY26E/FY27E forecasts, following the seventh consecutive organic upgrade since 2024. Their price target was unchanged at 400p, based on 4.4x FY27E EV/Sales and a 3% forecast EFCF yield. Against the current 225p share price, the price target implies almost an 80% upside.
Cavendish compares Quartix to its own Tech 40/Next 50 coverage, where peers trade on a median 2.8x forward EV/Sales and a median 5.4% sales growth. They argue that Quartix trades on the same 2.8x multiple but with roughly double the growth. Global telematics peers such as TomTom, Trimble, Samsara, and Descartes Systems trade at a median 3.3x EV/Sales and 24.2x P/E, well above Quartix's 14x forward multiple.
The Bear Case
- The US isn't yet proving the thesis: While all other regions are showing consistent revenue growth, the US stands out as flatlining over the last few years:
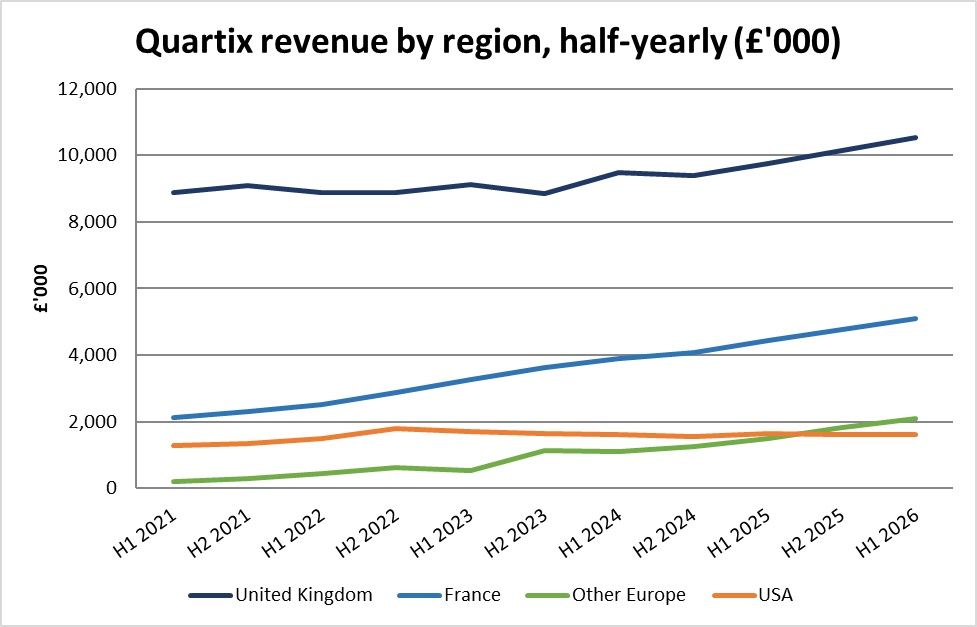
The hopes that the future will look different are resting on a device that hasn't reached full production. - UK momentum has slowed: group net revenue retention fell to 96.9% in H1 26 from 97.3% a year earlier, driven by "temporarily higher attrition from some customers" in the UK. Investors will look for signs this is genuinely temporary when the FY trading update is released in early January.
- Not cheap by classic value metrics: a Value Rank of 42, Price to Free Cashflow of 22.4x and Price to Book of 3.39x mean the investment case rests on growth continuing, rather than assets or near-term cash flow.
- The hiccup and key-person risk: While much of the 2023 write-down was non-cash, the impact was far-reaching, with a full management shake-up and Andy Walters taking on an executive role again in response. Since then, execution has been strong. However, this raises the question of what happens when Walters, now in his 70s, decides to pass on the reins again.
- FX exposure: Given the business reach, FX exposure is significant, with roughly 35% of revenue in Euros and 10% in dollars. Sterling strength against the euro directly drags on reported growth.
- FRC restatement: In October 2025, the FRC's Corporate Reporting Review team questioned how Quartix treated tracking units, dashcams and their installation and carriage costs in the 2024 accounts. Until then, Quartix had treated these as contract costs. In response, Quartix agreed it would keep legal title to the devices, and they would now be counted as PP&E and depreciated. The change was applied to earlier years, and the 2024 and H1 2025 revenue were reduced by £0.6m and £0.3m, respectively. Such accounting restatements don't build investor confidence. Reported profit actually rose, and cash flow was unaffected. However, the related one-off tax charge fell in 26H1, which is why reported EPS fell even though profit before tax grew 21%.
The Bottom Line
Quartix looks like a genuinely high-quality, cash-generative business. With a gross margin above 70%, operating margins above 20% and growing, plus a ROCE in the mid-20s, it is no surprise that the Quality Rank comes in at 98. On top of that, we have net cash and a dividend yield approaching 5%. It is rare to find a company with such high-quality characteristics at a forward P/E of 14.
However, the strength of the cash payout may reflect an inability to reinvest significant capital to drive earnings growth. Historical revenue and EPS trends show steady but rather pedestrian growth.
There are signs that the future may be better. If the company meet forecasts, this will be the second year in a row that EPS growth has approached 20%, and there have been 7 broker upgrades since founder Andy Walters retook the reins.
However, despite many years of operation, the US business is still growing ARR at just 1%, and has just been overtaken by continental Europe ex-France. Plus, UK net revenue retention has gone backwards year-on-year, raising real questions about the growth story management keeps reiterating. The key question is whether the softness in the UK and US through H1 26 marks the start of a genuine slowdown, or simply noise for a company with a proven record of high returns on capital, a cheaper device generation on its way, and a dashcam launch yet to reach its largest market.
For a business with this kind of long-run quality, the shares currently look more oversold than overvalued.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

9 comments
Before investing in Quartix Stock Rank 74 one should also look at Ituran (ITRN listed in Stockopedia). Ituran is an Israeli ADR with stock rank 95 which is in the same business but is much bigger than Quartix with far higher profits. Briefly Ituran 7 x Quartix in Market Cap and 8x profits . Other statistics are broadly similar.
Ituran operates in the USA, Brazil, Argentina and Israel and offers possibly some services Quartix does not and vica versa e.g. stolen vehicle location . I currently hold ITRN and intend to continue to hold - the service is in a growing market with strong annual repeated subscription revenues and IMHO massive international potential.
One point is that its Israeli dividends suffer withholding tax at 25%. Of this 15% can be used by British tax payers as a credit against UK tax under the UK- Israel Double Tax treaty - see below- but this is not advice - confirm this with your adviser .
credit
Further to my diatribe on a favoured share of mine, here are the two websites for USA and France which some may find interesting.
The primary domain addresses for both territories are:
Re £QUARTIX further to my comments on the websites for different countries, the company has changed its approach. Instead of spending a lot of money on updating a variety of websites, they now reverted to their high standing on Trustpilot and that is where you can check the latest comments. Check in to https://www.quartix.com/en-gb/company/investors/
Thanks for the review Mark. You always cover the deep financials in a way that I can't.
I am a long standing shareholder and have been all over this share for some time. For everyone's benefit here, I have reviewed it on here and also on Paul Scott's show several time. The CEO (and only Board member currently) has been on Mello Monday twice in 2025 I believe and then the last one on the same platform by his two long standing Sales Manager and Finance Manager.
I'm interested in the two comments below. Especially the no directors buying and also the response to what I regard as a minor FRS discussion which changed little but seems to frighten people away. Strange, or maybe its me. There are no further directors, and there are significant founding holders, but only the CEO is the key top manager. Maybe the other commentators here thing the long standing other shareholders should be buying into weakness in the SP. I dont know.
The period when the CEO stepped away for the business for whatever reason was sour. The board at the time made a bog of it, bought a German competitor for too much, and screwed up the business in Germany. They probably didn't do much good elsewhere either, but Germany was the real mess. Andy Walters stepped back in - fired the board, got rid of their German acquisition for as little pain as he could, and then set about focusing on the rest of the business. It didn't take that long really fortunately which is an indicator for me of the guy's skills. He has put the focus very much back on the middle management team he left originally - Sales and Finance, and they are good. the French 4G was a necessary technical move, the cost was absorbed, and France continues to be a growing market.
Right, this is what I think. The UK market is very mature, and I am not sure how many businesses in their real target market - quite smallish businesses - are ready to spend right now. However, the £1/2m from all round cameras was successful, and there is little reason to think it wont be in France too.
I think that he is really interested in the hardware, and the results coming up are significantly cheaper product with enhanced performance though at Mello he still thinks the prime motivation is knowing what's happening to all their people and gear around the area/country. Nevertheless, value for money is big in this company's offering, that along with service - which bring us on to the business outside UK and France.
Spain and Italy are going great guns and that says to me that there is more to go at there, and that closer to home makes sense. There is Germany to rebuild, and then there is - for me - the rest of Europe. The installation offering is they will arrange it or the user can fit it themselves/with their choice of electrician - as I read it, and I guess that take quite a lot of handling and managing.
The US is another matter altogether. It goes without saying that it is potentially a temptingly huge market, but its also a long way away for a company which prides itself on its customer service. I guess they must have resellers there - you can find their website in the US if you want to with their case studies etc, just as you can find the French one too. I guess that the US is very tough to get off the ground, there is huge competition (I dont just mean in size - just a lot of it, whatever the niche they are looking for. If I remember rightly, there seems to be a small base on the east coast, and another in the mid-west somewhere - presumably separate resellers. A lot of much, much bigger companies have tried in the US - and failed, costly failures. So I'm not sure that the US promises to be the big growth area this company is looking for, if it has ever stated that in any accounts. Maybe Canada would be more interesting? Maybe I will drop Andy Walters a line if he feels the need to cross the Atlantic.
They have developed a robust and broad sales approach to the market opportunities, their so-called 4 pronged method.
1. using Price-Comparison Websites in the telematics sector, targeting SMEs.
2. Inside Sales (Telephone) The backbone of their direct channel involves their internal sales team that manages inbound leads (generated via digital marketing and price comparison engines) and performs outbound calling. Since Quartix focuses on simple, unbundled tracking packages, their inside sales agents can rapidly convert prospects over the phone using online demonstrations.
3. Indirect Channel (Distributors & Resellers) Quartix has a rapidly expanding international network of authorized third-party channel partners and resellers. This includes: Garages, workshops, and automotive service centres: Fleet leasing companies: Telecoms/connectivity providers and trade retailers. These partners bundle or cross-sell Quartix tracking hardware directly to their existing local commercial networks in exchange for a healthy commission structure.
4. Field Sales Teams. Reserved primarily for its larger geographic markets (such as the UK), Quartix These targeted representatives handle higher-volume commercial fleets, corporate clients, or specialized local tenders that require face-to-face negotiation, site alignment, and managed contract rollouts.
In summary, they have the new gear to relaunch with full scale production just in; they have the camera extension in France after a successful intro in the UK; they have great opportunities still in Spain and Italy. The UK market is tougher to find growth but lets see what the new models can do to re-stimulate the Sales force to go get it. I accept there is the concern about succession but when you see him perform in say Mello Monday, he is certainly a highly active 70s operator. Backing that up. he has the long standing Sales and Financial management team and the separate R&D development team to fall back on. I guess that he will be more careful about his choice of a Baord this time if he chooses to sstep back a second time.
Great article Mark, and interesting comments. Thank you both!
I never thought I'd see Mark pitching a stock above 10x P/E!
Some great additional background, thank you for sharing.
Hi Mark
Thanks for this
I too looked at this a couple of weeks ago and came away deciding not to invest , on the following basis :
I was initially drawn to the business by :
I guess I'm largely in the same position as you, as I've written up this Stock Pitch, and I've not invested!
However, I think you are a little harsh on the moat - the numbers look very strong to me and suggest that competitors can't just undercut them on price and take their business (although no moat is unbridgeable over time).
The question for me is whether they can actually accelerate growth to a level that makes that moat really valuable. If the rating was a single-digit P/E, it would be a buy anyway IMO, but at 14x forward earnings it needs a bit more certainty on growth IMO.
Hi Mark
Thanks for this very useful. I had a quick look at the company a couple of weeks back and came away with the conclusion that they needed to see USA breakout of its seeming rut, decline in subscriber numbers it seems is not a good look if this is deemed a key growth area. I also noted the Key man issue and that the business was only put on the right road when AW came back. The accounting issues were not a good look which made we shy away. Theoretically the type of recurring income from subscriptions is great. Would like to see more skin the game from other directors. At best I am on the sidelines looking for the Dashcam launch in Europe