Quercus Publishing (QUPP): Half-year results

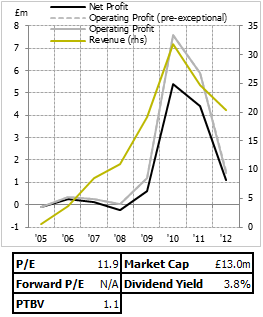 I looked at Quercus a little while ago, but it was ultimately Quarto who made it into the portfolio by virtue of their more diversified offering. Both are book publishers, but while Quercus are publishers mainly of fiction - and thus subject to a rather more lumpy results profile - Quarto's offering of non-fiction books, as well as their operating model, present a more predictable picture. I still liked Quercus, but there were big question marks about just what we could expect from the company coming down off their really big hit; Quercus spotted the Stieg Larsson books (Girl with the Dragon Tattoo etc.) when they were a tiny company, and the contribution from that one series dwarfed anything the company did before or has done since.
We've since had a little clarification with how things are moving along with the company's interim results. The headline figures are decent:
• Turnover up 10.9% to £10.2m (2012: £9.2m) • Operating profit down 7% to £0.52m (2012: £0.56m) • Digital revenue up 46% to £3.5m (2012: £2.4m) • Digital revenue as a % of total revenue was 34.3% (2012: 25.6%) • Cash at bank and in hand £0.3m (31 December 2012: £1.85m)
Digital as a percentage of total is interesting in Quercus's case - it's very high, and perhaps alleviates some of the concerns people have about the sort of secular problems book publishing has; a shift from physical books to ebooks might appear less worrying if the company you're invested in has been involved with ebooks for years already. For what it's worth, I don't think I'm too concerned about this sort of argument. Firstly, I think the pace of change is nearly always overstated. More importantly, I suspect publishers continue to add value whatever the format. Publishers only become irrelevant when all authors want to self-publish, self-promote and advertise, self-distribute (or distribution is irrelevant - the ebook revolution) and so on. They're different ball games, and to call one a substitute for the other is an over-generalisation, in my view.
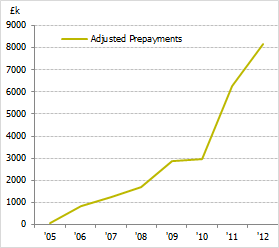 Revenues rising substantially is interesting, and this probably marks the turning point for the company - Larsson revenues have been tailing off for years now, and the company's investment of those profits into future potential revenue streams is becoming evident now. If you want a feeler for the scale of that investment on an on-going basis; Administrative expenses (the income statement line), representing general operating costs, are likely to finish this year at roughly twice that of 2009. They have about 70% more staff. I'll reproduce a graph from my previous piece on Quercus, since it's another way of highlighting the sort of investment Quercus have been putting in: see right. Prepayments are basically investments in future book sales.
What we've seen, then, is two divergent forces at work - the declining sales of the Larsson books, which represented a large chunk of revenue at very low incremental cost, finally outweighed by the rapidly increasing investment in new books. The problem? Each £ of new revenue is worth much less than every old pound of Larsson revenue. This is fairly obvious when you think about it - would you rather have one great book, which you can spend £3m a year marketing and promoting, or 100 decent books, all of which require individual attention? In short - the company, with its current pipeline of new books, is never going to make anywhere near the operating margin it did in its glory days. Operating and distribution expenses are going to be a far higher proportion of revenue than they have been in the past.
At the same time, though, I don't think the company has seen the end of its investment-led growth. The group's just set up a 4 person team in New York, for instance - which must be 250k+ of cost that they think is justifiable on top of the expenses they're already incurring - not a small sum for a business which earnt £1.4m in operating profit last year.
In short, I think Quercus is a noisy picture. It's difficult to disentangle the moving parts and figure out what reasonable expectations for the business are. Perhaps an operating margin target is best - Bloomsbury, a larger listed publisher, earn a >10% operating margin and the Harry Potter books' exceptional effects have probably filtered through there. If we pencil in a bit more growth for Quercus, £22-24m might be a reasonable revenue target on their current asset base - 10% of which gives us operating profits of £2.2m in a company with no debt (though they expect to be drawing down from their revolving credit facility later in the year).
As I said last time, a nice way to look at it might be based on a loose assets definition - what does £13m buy you in Quercus? Well, it buys you £13m in net assets, the vast majority of which are prepayments to authors. If you assume the company simply recoups its money on these - and it would be rather a poor business if it only managed that, on average - the business is worth that value discounted over how long you think it'll take to recoup them - the company amortises that line over 2 years. What's the business's back catalogue worth? Well, it has no balance sheet value - but it seems silly to suggest the sale of the Larsson books, which are still making them money, is worthless. I genuinely don't know how much of a tail there is in book sales. I suspect ebooks will make this bit more valuable, as distribution costs are essentially nil.
It's cheaper than last time I looked at it, and my gut feeling is that it's probably cheap, but I think I'd rather wait for the full year results. I might try and figure out exactly what I think the key questions are so I can come up with a more cohesive thesis.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
1 comment
Down down down, A definite NO from me, Try PTO it is currently going Up up up. This one is not for me.
Cheers from Lightningtiger.