Quintain Estates under offer

Property developer Quintain Estates is developing residential apartment blocks next to Wembley stadium. With demand for London housing outstripping supply the group is well placed. It not surprising, then, that Quintain has received a takeover offer but the valuation appears low.
Takeovers are the closet the city comes to war with two sides fighting it out. In the case of Quintain Estates there hasn’t been much of a fight yet with the company’s directors recommending a 131p cash offer.
Quintain is developing Wembley Park
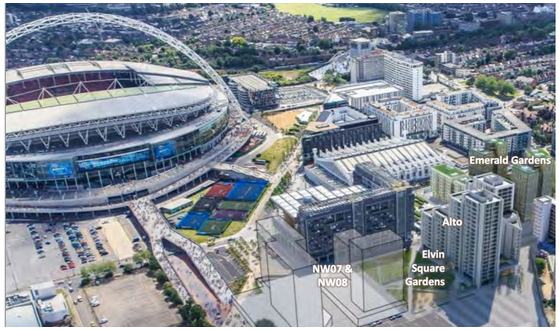
Source: Quintain Estates
This leaves it up to Quintain Estates’ shareholders as to whether they accept the valuation arguments from the company. In our view, it is likely that Quintain’s shareholders will hold out for a higher price.
If the offer falls through then Quintain’s share price could fall back to the pre-bid level of 107p. However, the potential acquirer, Lone Star, looks set to be a determined bidder.
In the recent case of Dragon Oil the initial offer from ENOC was set at 735p a share. This was later increased to 750p a share and then finally 800p to clinch the deal with Dragon Oil’s shareholders.
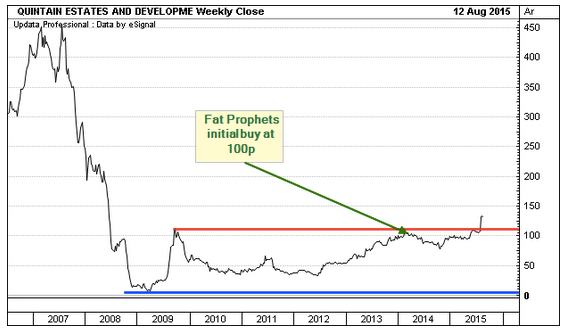
Quintain Estates profile
Property development is a sector that booms in the good times and comes close to bankruptcy in downturns. This is because developers have projects that aren’t generating an income and use debt financing.
When the music stops these two attributes leave real estate developers with nowhere to hide. Quintain Estates certainly faced the music in the financial crisis with its share price falling from 450p in 2007 to 4p in 2009.
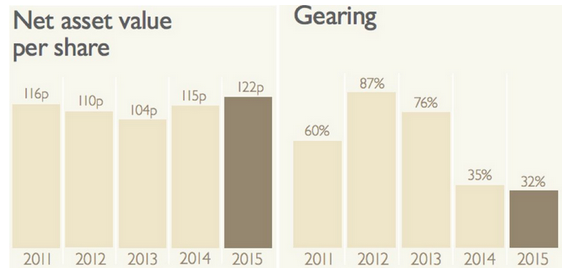
Quintain has recently been reducing its gearing level with it at 32% in March 2015 versus 87% in March 2012. The net asset value (NAV) per share has increased in the last two years and hit 122p at March 2015.
Quintain de-risks and returns to NAV growth
Source: Quintain Estates
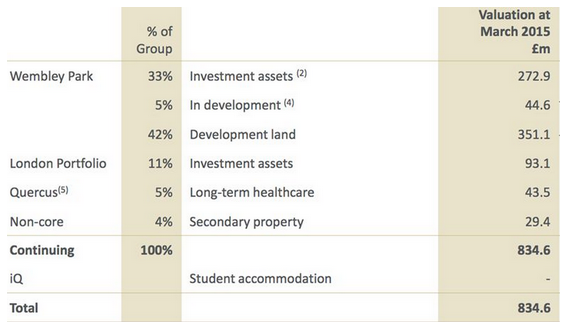
Quintain is now focused on Wembley Park in London with this area 77% of its asset exposure at March 2015. Wembley investment assets are 33% of total assets and development land is 42% of total assets.
Land in development at Wembley is 5% of assets and outside of Wembley the London investment portfolio is 11% of assets. As such Quintain is a bet on the London property market and in particular Wembley Park.
Quintain Estates asset profile March 2015
Source: Quintain Estates investor presentation
Quintain has also increased the proportion of mature income generating assets in its portfolio. This serves to reduce the risk of property development and provides a reliable income.
In the year to March 2015 the group generated £15.8m of rental income which compares to £3.8m the year before. A driver of the higher income has been the completion of the London Designer Outlet at Wembley.
Quintain’s prospects and valuation
In terms of the net asset value prospects and the next few years should offer further gains. This will be driven by further planning permission wins at Wembley and the successful construction of apartment blocks.
Some analysts are forecasting that the NAV of Quintain will be north of 130p by March 2016. This compares to the figure of 122p reached at March 2015 and 115p at March 2014.
Against this backdrop the 131p cash offer from Lone Star doesn’t appear overly generous. This is because it doesn’t appear to include the value of the long-term development potential at Wembley Park.
Lone Star in focus
The bidder for Quintain is the Lone Star Real Estate Fund IV which raised US$5.8bn in April. As such the £700m takeover of Quintain can be easily funded with Lone Star having £425m of debt finance lined up for the deal.
Angus Dodd of Lone Star Europe Acquisitions LLP stated that:
“The proposed acquisition represents a unique opportunity for Lone Star to gain further exposure to residential and commercial assets in London. Wembley Park is one of the largest and most exciting urban renewal projects in Europe…”
Quintain’s shareholders
The ball is now in the court of Quintain’s shareholders with the official offer documents published on 11th August. At the end of March 2015 investment institutions had around a 31% stake in Quintain.
Since the offer was announced on 29th July we have seen a couple of new funds build a notifiable position (over 3%). York Capital Management has a stake of 3.4% and Merrill Lynch now has a 5.8% holding.
At the same time Third Avenue Management has cut its stake from 4.1% at March 2015 to below 3%. In our view, it is more notable that a number of funds appear to be betting on a higher offer coming through.
Quintain’s directors have recommended the offer and pledged their 0.3% holding to accept it. This is fairly small beer and shows that Lone Star has a significant way to go to win over Quintain’s investors.
At over a 50% shareholding Lone Star will control Quintain and at over 75% it can delist the group. If Lone Star gets over 90% of the shares it can make a compulsory purchase order for the rest.
Summary and valuation
With Quintain having deleveraged and seeing valuation momentum it is understandable that it should attract a bid. It is more surprising that Quintain’s directors have recommend the 131p cash current offer.
After all the NAV of Quintain could come in at around this level in March 2016. The growing rental income stream should also support the introduction of a dividend in the medium-term.
This will certainly be an interesting bid battle to watch with the deadline for acceptances 9th September. In our view, it looks more likely than not that investors will hold out for an improved offer.
This appears to be the position of shareholders with the shares trading just above the 131p offer level. A London apartment builder with growing rental income offers exposure that is worth fighting for.
This report was produced by Fat Prophets Senior Analyst, Andrew Latto.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
4 comments
Offer increased to 141p cash. Crux is what Elliot chooses to do. I think there is now a good chance that the offer will succeed. Probably a good chance they will get the 75% level we will find out on the 30th September.
I hope the offer doesnt succeed. If it does I will be interested to see the payments made and jobs offered to the current board and management. As we have seen for some time Quintain has been run very much for managements benefit. It would seem that the takeover offer may be no different.
Maddox,
Interesting that 53% accepted the 131p cash offer. Crux is whether they can get to 75% as this would mean de-listing and would likely force the hold-outs to accept. That was certainly the case for Songbird Estates which was taken over at a fairly low price.
The arguments for accepting the takeover seem so shallow and ridiculous. I.e. because the shares were previously trading at a discount to NAV. So what? Investment sentiment can change and has been changing towards Quintain Estates.
Even if the offer fails and the shares go back to 107p it is still probably better for investors than accepting now. The NAV at March 2015 was 122p. Just seems amazing to me that Quintain's board and management would recommend this offer. I can't understand their argument for doing so.
Hi Andrew,
Spot-on analysis, shareholders have nothing to lose from rejecting this offer - 131 p is just far too low.
After failing to secure sufficient acceptances to their low ball offer Lone Star and QED’s Board, with whom they are in cahoots, have given shareholders the opportunity to reject it all over again! They only managed to get 53% acceptance first time round – way short of the 75% they need to force unconditional acceptance of the deal. Many of the acceptances will have been ‘default accepts’ by the Nominee in view of the Board recommendation. A no vote is the more considered option and so it is a clear and unambiguous rejection to the Board’s recommendation.
With house price inflation figures being revised upwards Lone Star’s 131p offer is looking increasingly unattractive. Despite the market jitters, it is highly unlikely they will get many further acceptances. So, Lone Star will need to re-consider what price they will have to pitch to get sufficient Institution Investors on-board to close the gap. And the wider the gap and more emphatic the rejection the higher they are likely to bid.
So vote early, vote NO!
Regards, Maddox