Reliance Worldwide Corporation: Looking after the plumbing
Anton Crabbe is a new contributor to Stockopedia and we look forward to reading more future insights. To learn more about Anton you can read his profile here.
Reliance Worldwide (ASX:RWC) is a company that I like, and on the recent pull back in its share price due to the broader market reaction to the failure of SVB. I like it even more. Being in the building and construction space, they will experience the ups and downs of the construction industry as it inevitably cycles through its boom-and-bust phases.
Management has done the right things by shareholders and returned excess capital, and not issued excessive amounts of shares since listing in 2016. For a manufacturer/supplier in this space, they are conservatively geared with a 55% net-gearing ratio. They have stuck to their knitting and management has not decided to go off and buy a movie studio or start manufacturing EVs, or something daft like that.
RWC is involved in designing, manufacturing and supplying high quality, reliable and premium branded water flow, control and monitoring products and solutions for the plumbing and heating industry. They have expanded this offering in the USA through the acquisition of EZ-Flo. The jury is still out on this acquisition and time will tell if they got it right, but early signs are looking good!
StockRank:
The quality of RWC is starting to show in the face of a construction industry currently experiencing a downturn.
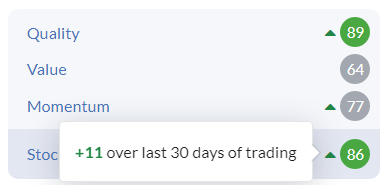
RWC’s stock ranking has increased by 11 over the last 30-days to 86, quality increased by 9, and momentum by 17 to 77. Furthermore, over the last 4-years RWC has basically maintained its super stock classification.
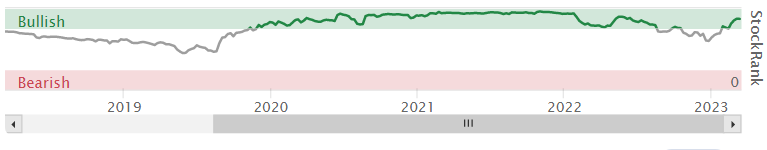
This is reflected in the overall quality of this Consumer Cyclical business.
Financials:
RWC has increased sales revenue from $453m in FY17 to $1.1b in FY22. The increase in sales has resulted in higher profits. With profits growing from $49.9m to $137m over the same time period, with profits peaking at $141m in FY21.
However, in FY22 RWC’s profits and cashflow declined. This is mainly due to increased input costs (raw materials) and an increase in inventory. Inventory levels increased as RWC looked to insulate itself against supply chain issues caused by COVID.
In their 1QFY23 update, RWC noted “Higher input costs experienced early in 2022, particularly copper, zinc and stainless steel, have eased since their peak in mid-2022 which is expected to positively impact operating margins later in FY23”. It also noted that during FY22 RWC had successfully integrated both EZ-Flo and LCL into their business, acquiring them for $332m and $28m respectively.
LCL is a strategic acquisition, as they are Australia’s largest producer of high-quality copper-based alloys and processes using both new and recycled materials, to produce a range of brass alloys. This secures a major part of RWC’s supply chain, with LCL’s brass operations located in Melbourne next to RWC’s. EZ-Flo on the other hand is located in the US. It was a bolt on acquisition and contributed $124m to revenue in FY22 and $58m to revenue in 1QFY22.
The USA is RWC’s largest business segment, accounting for $790m of $1.1b sales in FY22. Though it noted it has experienced decline in volumes recently in the USA and EMEA, but APAC still had rising volumes. RWC increased prices to help offset the effects of higher inflation and input costs, resulting in sales growth for FY22 and 1QFY23 despite the slight pullback in volumes.
Over the last 5-years, management has improved efficiencies and managed the business well. The current ratio of 3.4 is indicating RWC’s short-term assets will cover short-term liabilities and the company has good liquidity. This is also indicated in days debtors and creditors reducing, thus speeding up the time it takes them to pay their bills and to collect money owing.
Further to this point, days inventory has reduced over the longer term from 147 days in FY17 to 131 days in FY22, highlighting they are now selling more and turn over more inventory than what they were 5 years ago. However, something to watch closely here though is that days inventory actually increased from 112 days in FY21 to 131 days in FY22. This is to be expected with the build up of inventory as noted by RWC, but cannot continue to increase, as it will create cash flow issues for RWC and they run the risk of their inventory becoming stale. This can lead to potential inventory write downs and discounting, which will negatively affect profits and their share price. The increase in working capital has been due to acquisitions and increased levels of inventory. RWC does have a healthy capital expenditure program, as they are spending, more often than not, the same or more than they depreciate. Management is not trying any tricky accounting as their effective tax rate is basically the same at the corporate tax rate of 30%.
Most of the above are based on my own calculations but are supported and mostly incorporated in the F-Score, M-Score, Liquidity and Efficiency ratios.


I’m not too concerned by the cautious Z-Score as RWC has good liquidity (as noted above) and with interest coverage at 8.99, earnings are more than able to cover their interest payments. Also, at previous points in time during FY19 and FY20 RWC did have a safe Z-Score.
Furthermore, COVID supply chain issues and input costs are easing and expected to normalise in the second half of 2023. With these reduced costs and no more need to hold such high levels of inventory, this in turn should increase cash flow and the overall financial health of RWC (this is something to keep an eye on though!)
RWC has shown financial discipline by paying a prudent dividend, as seen by their dividend cover constantly round 1.8 to 2.0, showing they are retaining profits and reinvesting this back into the company. RWC will continue to pursue its policy of paying out 40%-60% of annual net profits as dividends (i.e. higher profits equal higher dividends). RWC is only able to pay partially franked dividends for Australian taxation purposes due to the geographic mix of its earnings.
This brings me to my final point, RWC has increased or maintained their profitability measures on the back of increasing sales and earnings. Thus, further showing the quality of the business and its ability to create long-term value.
Consensus opinion:
Currently 10 out of 16 brokers have a buy recommendation and only one with a sell.

Investors considering buying RWC now, note you are purchasing them counter cycle and that there may be more pain ahead before the current downturn ends and conditions improve.
This can be seen in flat profit estimates for FY23 and FY24 coming it at $137m and $141m respectively (FY22 $140m), flat FY23 and FY24 EPS forecast, and their valuation ratios all looking a bit stretched.
Any continued weakness though may prove to be a larger opportunity in a quality business such as this.
Liquidity and Ownership:
RWC have 790m shares on issue with a free float of 763m or 96.5% of issued shares can be traded. With 58.2% of shares held by top 20 shareholders and the remaining 41.8% held by other investors. AustralianSuper is RWC’s largest individual shareholder with 86.1m shares or 10.9% of issued shares. On Average 3.7m shares are traded each day. All things being equal, DIY investors buying/selling small parcels of shares will be able to get in and out of the stock without any issues.

Outlook:
In RWC’s FY23 half yearly report, revenue increased 15% to $601.3m and volumes were up 11% on pcp with these numbers including a full contribution from EZ-Flo for the half-year. Excluding EZ-Flow, volumes were down 2% overall.
Revenue growth in all regions was due to an average price increase of 8.5%, across their product range as high input costs and inflation are continuing to keep pressure on margins. They noted that inventory levels were still high as a result of a pending new product release and the lingering effects of COVID but said they will be looking to reduce inventory levels in the second half of 2023. RWC did not provide forward earnings guidance but are expecting cost pressures to ease and the benefits of cost reductions to be a positive for the rest of 2023.
On the downside, they did cite falling volumes and a potential lack of confidence of consumers to spend on home improvements as areas of concern.
Conclusion:
RWC is a quality consumer cyclical business supported by strong StockRank and Quality rankings. And despite the obvious worries around the industry brought on by rising rates and supply chain issues, the enduring quality of the business will shine through when conditions improve, thus rewarding investors with increased capital growth and dividends.
Important Information: Stockopedia Ltd ABN 39 757 874 670 UK business registration number 0637267 (“Stockopedia”) is an Authorised Representative of Daylight Financial Group Pty Ltd ABN 77 633 984 773 (“DFGPL”) which is the holder of an Australian Financial Services Licence (AFS Licence No. 521404).
Information in this commentary is current as at date prepared unless otherwise stated. However, please bear in mind that investments can go up or down in value, and that past performance is not a reliable indicator of future performance. For more Important Information please refer to the Disclaimer section of this website.
This communication may contain general financial product advice. It has been prepared without taking into account your personal circumstances, and you should therefore consider its appropriateness in light of your objectives, financial circumstances and needs before acting on it.
If our advice relates to the acquisition or possible acquisition of a particular financial product, you should obtain a copy of and consider the Product Disclosure Statement (PDS) before making any decision.
The author holds interests in the following stocks mentioned in this article: RWC. This position can and will change at any time without notice.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
2 comments
TRADING UPDATE FOR NINE MONTHS ENDED 31 MARCH 2023
Sales for the first 9-months came in at USD 932m up 10.3% pcp. This includes a full nine-month contribution from EZ-Flo and excluding EZ-Flo on constant currency basis sales increased by 5.7%.
By Region:
Americas: sales up 18.5% - volume up 12%
APAC: sales flat 0.1% impacted by a 20% reduction in new residential commencements, price increases helped offset lower volumes.
EMEA: Sales up 8.7% mainly due to strong performance of UK plumbing and heating up 16.7% with low single digit volume growth offset by price increases and total UK sales growth up 12.5%.
Operating Margin:
Input costs have eased since their peak in mid-2022 which has positively impacted operating margins progressively during the period. Adjusted EBITDA margin for the nine-month period was higher than that recorded for both the first quarter and six-month results for FY23. RWC continues to expect FY23 second half Adjusted EBITDA margin will be higher than for the first half of FY23 and are still on tract to realise $15m in cost reductions for FY24.
Forward Guidance:
RWC did not provide any forward guidance. Consensus estimates is for FY23 profit to increase from $137m (FY22) to $213m (FY23).
Reliance Worldwide (ASX:RWC) on 28/03/2023 announced the release of two new product ranges in the USA and Canada. The new Shark Bite Max range will be rolled out in the USA and Canada over the next 15-months and the Pex-a pipe range is only being released in the USA. Majority of the Shark Bite Max manufacturing has been moved from AUS to the USA. With the aim of this move to increasing the resilience and efficiency in their USA supply chain and free up capacity to refocus their AUS manufacturing faculty to service and grow the APAC region. This is a welcome announcement, as increasing inventory levels have been of concern, and inline with previous guidance, should result in inventory levels reducing for the rest of 2023.