Revisiting Reliance Worldwide - RWC
Revisiting RWC
This is the first stock we have revisited since its original publishing, with its products lasting longer than our review. Some see it as a boring stock, I get it. But it just keeps delivering strong results, despite the tougher environment, so I can’t ignore Reliance Worldwide (ASX:RWC)
RWC design, manufacture and supply premium branded water flow, control and monitoring products and solutions for the plumbing, heating, and remodelling industries. The company comprise of three business segments Americas, Asia Pacific, and EMEA.
The last I wrote about RWC on 15th March 2023, I was concerned about the build-up of inventory levels, high input costs hurting margins, and the jury was still out on their EZ-Flo acquisition. But I was confident RWC was managed well, and the enduring quality of the business would prevail. Also, RWC had given guidance that they expected both inventory levels and input cost to decrease throughout 2023, and the lingering effects of COVID on their supply chain would dissipate also.
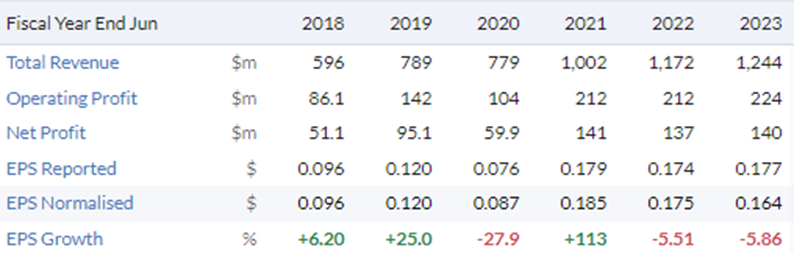
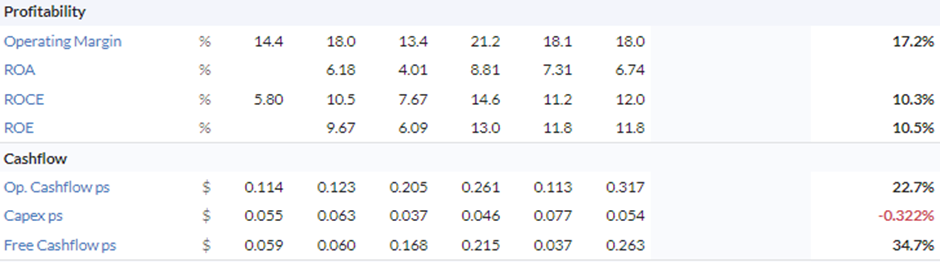
With this backdrop, RWC reported an increase in revenue, earnings, cash flow, and profits (underlying NPAT declined 4%) for FY23. While maintaining profitability ratios. However, more encouraging was that RWC reduced inventory levels from $316.0m in FY22 to $289.0m in FY23, on the back of two new product releases in the Americas.
Furthermore, margins were higher in the second half of FY23 on the back of lower input costs and RWC increased cashflow from operating activities by 110% to $250.0m. This was due to the reduction of inventory levels, realisation of cost savings, and synergies from the EZ-Flo acquisition.
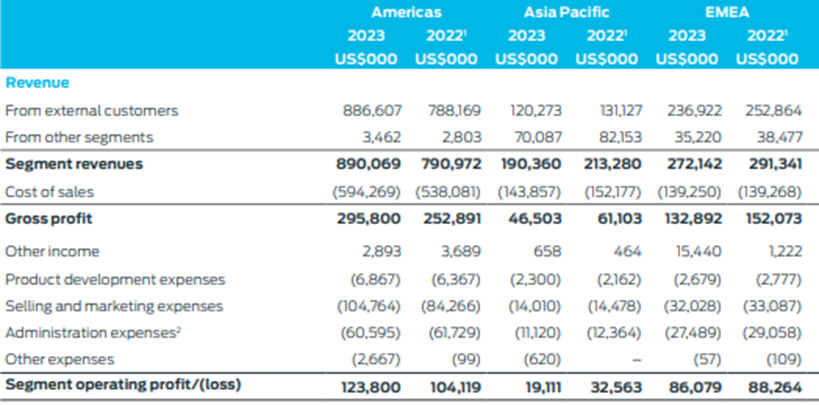
Source: RWC 2023 Annual Report 21/08/2023
Looking at RWC’s segment breakdown for FY23, it was the Americas doing the heavy lifting as it was the only segment to report an increase in revenue and earnings. Revenue was up 13%, which includes a full 12-months contribution from the EZ-Flo acquisition. Excluding EZ-Flo revenue for the Americas was up 4%. Based on this and RWC maintaining their profitability ratios. It looks like the EZ-Flo acquisition is profitable and creating value for shareholders.
StockRank:
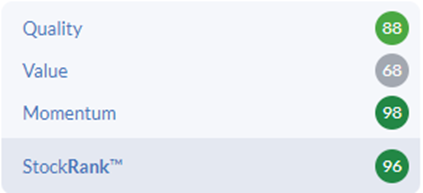
Looking at RWC’s StockRank and individual QVM indicators, most of the increase in their share price and StockRank from 15th March 2023 can be put down to an increase in Momentum. As it has increased from 78 to 98 at the time or writing, with Quality and Value indicators remaining flat. As you would expect, RWC’s share price has increased from $3.42 to $4.32 at the time or writing.
23rd January 2024
14th March 2023
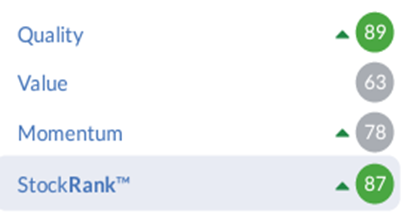
With QV remaining flat, but Momentum increasing by 20, this has resulted in an overall increase in their StockRank of Nine points. Looking closer at Momentum, some the initial fall will be as a result of the drop off in short positions from one year ago to today (1.7% on 16th January.) This pullback does not come as a surprise, as some would have been betting on a poor performance from a cyclical stock like RWC.
But to be fair, RWC reflected the tough business conditions it is experiencing when in their Q1 update for FY24 In October they reaffirmed that:
“At a consolidated level, we continue to anticipate that revenues will be down by low to mid-single digit percentage points in FY24 compared with FY23 due to lower sales in most markets.”
Trading conditions and sales for Q1 reflected this sentiment too, with all business segments reporting a decline in sales volume. However, RWC has indicated that they hope to offset this by further price increases and cost savings throughout FY24.
23rd January 2024
14th March 2023
Given the above guidance, Q1 performance, and the fact that RWC’s net-finance costs increased from $15.8m in FY22 to $32.3m in FY23. One would be excused for wanting to head for the exit door.
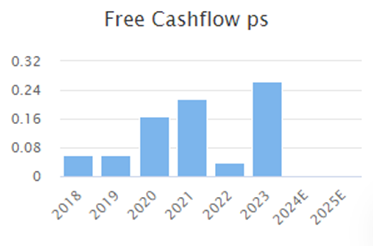
The silver lining in all this is that due to RWC ability to increase operating cash flow and free cash flow they were able to pay down debt and improve their net gearing position from 55% to 43% and maintain their dividend policy of paying out 50-60% of profits.
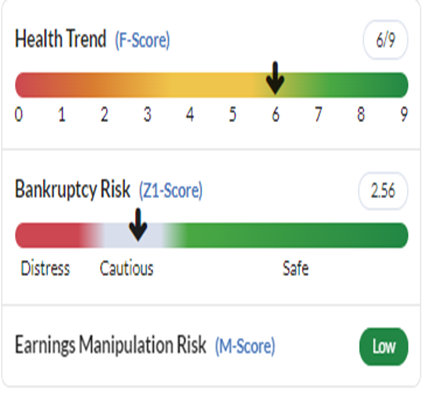
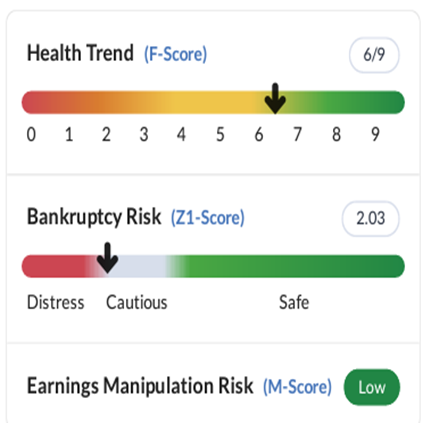
The net-effect of all this has resulted in very little movement in RWC’s F-Score and Z1-score, with a small decrease in the former and increase in the latter. For me, RWC’s ability to substantially increase operating cash flow in tough trading conditions speaks to the quality of the business and management. With this continuing to give me confidence to hold the stock.

Liquidity and Ownership:
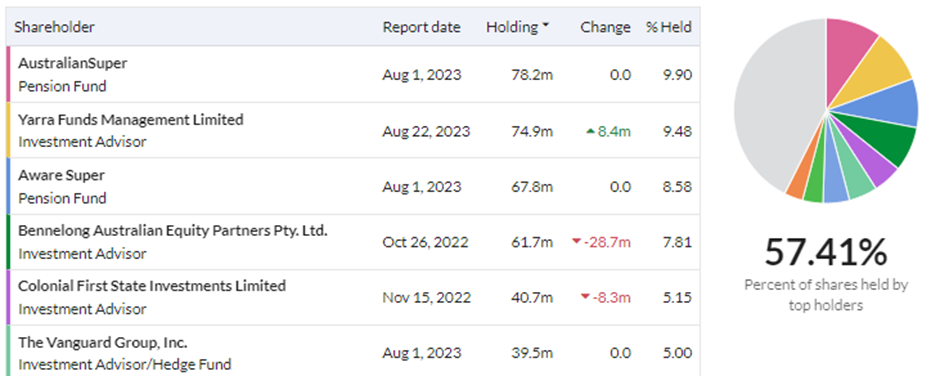
Once again, as you would expect from a quality stock, there has been little movement from top shareholders with shares held by the big guys reducing from 58.2% to 57.4%. With AustralianSuper still their largest shareholder at 9.9% down from 10.9%.
Further to this point, shares on issue and free float remain flat at 790m and 767m respectively. Meaning there is plenty of share liquidity here for DIY investors, and RWC have not issued more shares or diluted shareholders.
Outlook:
In the words of RWC’s Chairman Stuart Crosby from their AGM in October 2023:
“2023 was a challenging year. Higher interest rates adversely impacted consumer sentiment, and we experienced a softening in demand and slower growth than in previous years in most of our markets. RWC nonetheless performed well, and our business demonstrated tremendous resilience. Our volumes were underpinned by the orientation of our core business towards repair, maintenance and remodel work. ”
On a more positive note, and given the Americas generated some 70% of RWC’s total revenue in FY23, “we expect EBITDA margins to be higher than FY23, following the progressive transfer of SharkBite manufacturing and assembly from Australia. The phased timing means this will be more evident in the second half of FY24”
Despite this positive sentiment with the previous mentioned guidance, when looking at the Q1 trading update and it’s looking like FY24 will be another tough year for RWC. Furthermore, estimates for FY24 has profit remaining flat at $137.0m before increasing moderately in FY25 to $153.0m.
Conclusion:
For me nothing has changed since the last I wrote about RWC and if anything, I’m more confident in the quality of the business and its management.
Especially given their ability to increase cash flow and reduce debt in tough conditions. Having said this, the next 18-months look like they will be tougher than the last. This should more than likely be reflected in their share price. Given I hold RWC, for me I still see this as a buying opportunity. As I still expect RWC’s financial performance to improve as economic and business conditions do, and this is what you would expect form a quality consumer cyclical stock like RWC.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
No comments yet
No one has commented here yet! Why not be the first one?