Risky roll-outs - how Crawshaw showed that expensive growth can be dangerous

Jim Slater, the late British investment legend, used to have an affection for firms that could ‘clone’ their own activities. He saw the likes of retailers, restaurants and healthclubs as potential cash cows that only had to refine and prove their formula once. After that, they could expand at will. And with expansion would come high rates of return on capital and sequentially lower group overheads.
One nagging problem, though, is that roll-outs don’t always roll smoothly and growth stories can be hit by setbacks. This is exactly what investors in butchery chain Crawshaw have recently found out. Here I’m going to look back at the rise of Crawshaw, the factors that made it an appealing stock and the key signs that could help investors understand the risk of exposure to companies susceptible to sharp corrections on profit warnings.
How sentiment changed towards Crawshaw
Crawshaw has been a popular name among private investors over the past four years. Much of the investment case hinges on a profitable roll-out of its butchery and hot food stores. They’re anticipated to number 224 by 2024 - up from 39 in 2016. This process has been directed by chairman Richard Rose and, latterly, by chief executive Noel Collett, who was previously COO of Lidl UK.
So there was a great deal of disappointment this week that its like-for-like sales look set to fall in the first half of the year. Among other things, the company blamed the result on a combination of international football, adverse weather and Brexit - reasons that left investors feeling incredulous. It didn’t go down well, and shares in the company collapsed by more than 40%.
This could be a blip. It could be a temporary setback for a small company (now with a market cap of £33m) that’s utterly focused on expansion. All eyes will now be on how the management respond. But what can investors learn from this episode?
Learning lessons from Crawshaw
To get an idea why Crawshaw’s price fell so sharply it’s worth looking at how its profile has changed over time. One way of doing that is to look at Crawshaw through the lens of the StockRanks.
The StockRanks are designed to find good, cheap, shares on an upward trend. They use a combination of ratios and measures to score and rank stocks based on their quality, value and momentum, which are then blended to arrive at an overall StockRank score. You can find the StockRank of any stock on its StockReport or by looking it up in the Directory.
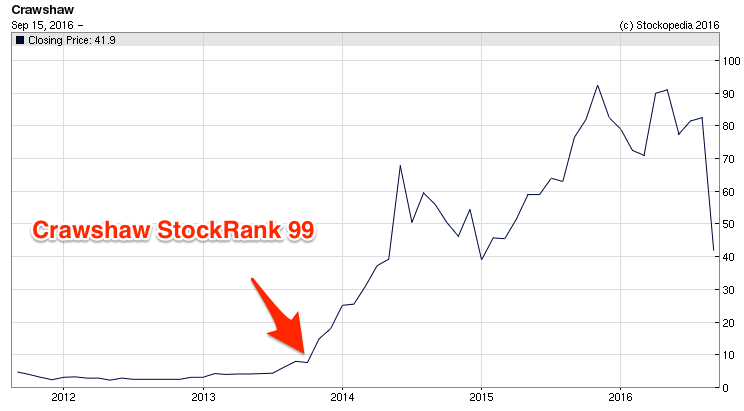
Back in November 2013, Crawshaw had a share price of 10p and a StockRank of 99. On every ranking factor, the company was eye-catching. Not only that, but in Richard Rose, it had a man on a mission to expand rapidly.
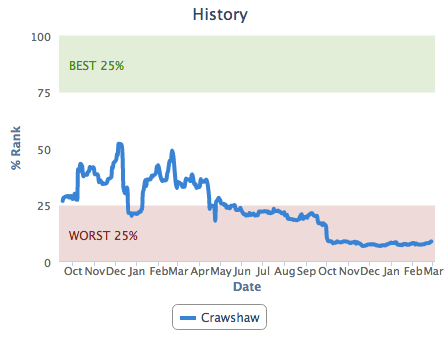
Investors that saw it at this early stage did exceptionally well. But as the sentiment warmed up, the stock’s value appeal naturally fell. In fact, in the four months to March 2014 its ValueRank fell from 97 to a much more modest 55 as price momentum took over. By December 2015 - 21 months later - the ValueRank hit a low of just 7.
Crawshaw was showing all the characteristics of what Stockopedia calls a High Flyer. Its quality and momentum ranks were generally high and stable throughout, but the valuation had become stretched.
Below is the Value Rank history for Crawshaw, which shows very clearly how the valuation became increasingly expensive over time. Stockopedia members can track changes in StockRanks using historical StockReports (using the dropdown menu from the ‘print’ button).
High Flyers can crash
In many respects Crawshaw is a classic growth story, ploughing capital into new stores and offering the promise of major expansion. Under those circumstances, heady valuations might be warranted - even though the company posted a small net loss in 2016. Indeed, High Flyers can be incredibly successful investments. But one of their enduring traits is the risk that the story changes. With the valuation underpinned by hope, any wobble can be catastrophic.
Crawshaw isn’t the only one. Even established High Flyers are prone to reversals. Take Restaurant Group, a roll-out play behind the Frankie & Benny’s and Chiquito chains. After a six-year run that saw the shares rise by 500% to 700p, Restaurant was a classic high quality, high momentum stock that never looked cheap. But in early 2016, when it raised concerns about the economic outlook, the stock more than halved in just a few months.
When they work, High Flyers can be home to some of the best investment returns in the market. But as Ed wrote about here, investors need to be aware of any change in sentiment because momentum reversals in expensive stocks can be ruthless. Fortunately for investors in Crawshaw, its half year results are due at the end of September. By then, the company should be prepared to reveal more about its plans to reinvigorate sales.
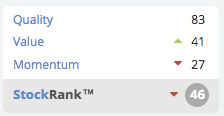
For the moment, Crawshaw’s StockRank has slumped and it currently looks like a one-factor company. In other words, the quality is high but the valuation is still racy and the momentum has collapsed. Deciding how to act on a profit warning is a supremely difficult decision for investors. For that reason, our team has been researching past trends to understand the likelihood of companies managing to rebound from profit warnings. The results aren’t pretty. But more on that next week.
Summary
- The profile of a High Flyer is that it’s expensively priced (low Value Rank) but with high Quality and Momentum Ranks.
- High Flying shares can be highly rewarding investments. But they can crash if they reveal surprising bad news.
- Crashes among High Flyers are hard to predict. You can diversify some of the risk by ensuring other parts of your portfolio aren’t exposed to the same sort of expensively-priced shares.
- You can instantly check the Quality, Value and Momentum Ranks of any stock using its StockReport or finding it in the Directory.
- You can track the monthly changes in StockRanks for any company using historical StockReports (using the dropdown menu from the ‘print’ button).
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
5 comments
Makes sense to me. I keep looking for "4 Button" stocks 90+ Stockrank, 90+ QM, QV, & MV ranks.
Time will tell how well that works.
Ben
This is very much "an after the event article."
You say in Nov 2013 the Stockrank was 99, but you do not say what it was in March 2014 or December 2015, the 2 other relevant times you referred to. In other words you moved the goal posts.
Can subscribers look up the Stockrank for a share on any given date?
Dendyver,
If you go to the relevant stock page and then click on the down arrow by the PRINT icon you can see a snapshot of the historic stock front page taken each month for about the past three years, For example, for Crawshaw (LON:CRAW) the SR in Mar 2014 was 91 and in Dec 2105 was 76.
Gus.
Thanks,
Valuable "tip"
should be able to make a nice profit if it keeps droping to around 25p. But shorters should stear clear after that as gets a little unpredictable.