Robinson issues its third consecutive profit warning; balance sheet provides hope

Analyst’s view:
Unfortunately, this is just the latest in a series of profit warnings from Robinson. I'm not surprised to hear that the company is now looking at how it might cut costs. On the bright side, it had balance sheet net assets of £25.7m (or £24.5m after stripping out intangibles) at the interim results, and property disposals are ongoing. However, profit warnings do tend to be followed by more profit warnings, and so I'm going to take an outright negative stance on this share today, until there are clear signs of stabilisation.
Down 6% at 115p (£19m) - Trading Update
It's a profit warning this morning from Robinson, "the custom manufacturer of plastic and paperboard packaging based in Chesterfield":
The Board now expects underlying operating profit for the year ending 31 December 2026 to be in the range of £1.2m to £1.6m. Revenue for 2026 is expected to be approximately £59m, 6% ahead of 2025. Sales volumes are expected to be 1% below 2025.
The company did not include the prior guidance in today's RNS, but if you scroll back to the interim results, published in August, they said then that underlying operating profit would be "between £2.2m and £2.6m".
So at the midpoints of each range, today's downgrade is a 42% reduction in expected profitability this year (£1.4m now vs. £2.4m in August).
Robinson explains that in the seasonally important second half, "demand has been weaker than anticipated in the Paperbox and UK Plastics businesses".
There have been a wide range of disappointments across these two businesses over the last two months, but most of them are effectively summarised as lower-than-expected demand and lower sales.
Looking ahead:
Excluding the benefit of potential mitigating actions, the Board expects FY2027 profitability to be in line with FY2026.
Estimates: Cavendish have published on Robinson today, so thanks to them for providing new forecasts.
Their new 2026 adj. PBT forecast is £0.5m (previously £1.5m).
And for 2027, the new adj. PBT is also £0.5m (previously £1.4m)
So these are very significant cuts for both years.
Graham's view
Unfortunately, this is just the latest in a series of profit warnings from Robinson.
At the interims in August, FY26 forecasts were slashed.
Then another profit warning last month took the wind out of FY27 forecasts.
Today's profit warning hits both FY26 and FY27.
I'm not surprised to hear that the company is now looking at how it might cut costs.
The August warning was attributed to higher costs and uncertainty around how quickly these higher costs might be recovered through higher pricing.
September's profit warning was due to the loss of a large customer contract.
At the interims, the company reported net debt of £6.4m but on the bright side, it had balance sheet net assets of £25.7m (or £24.5m after stripping out intangibles). Property disposals are ongoing.
While I do think that Robinson's balance sheet strength should provide long-term support to the valuation, I have to respect the fact that this stock is currently in the midst of a string of serious profit warnings. It's possible that there are competitive issues or other challenges that could make recovery difficult. I can't discount the possibility that more profit warnings are on the way and that the business model needs to be fundamentally changed. As we've learned through experience and research, profit warnings tend to be followed by more profit warnings.
For these reasons, I'm going to take an outright negative stance on this share today.
Due to its balance sheet strength, I'll be happy to revert to a more optimistic outlook as soon as there are signs of stabilisation, perhaps as soon as the next update. The fact that the share price has only fallen by 6% today suggests that the market already has very low expectations of the company.
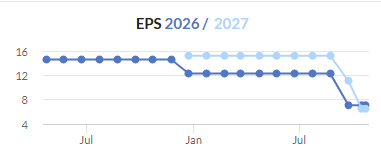
Here's the trend in EPS forecasts, prior to today's additional downgrade:
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
Discussion on Robinson (1)
Comments here are also visible in the Daily Stock Market Report
Thanks for your analysis Graham, much appreciated as always.
I just wanted to briefly say how much I like the new Stock Market Report format with each company analysed having its own individual page, together with related comments. Great stuff and a big thumbs up from me.
Fellow packaging company Mondi has been another in this industry to avoid for some time now.
Richard