S32: Worth another look now?
South32 (ASX:S32) began life as a listed company in 2015, when it was spun out of BHP
Over the proceeding 9-years S32 has become a global diversified commodities producer with a focus on producing and growing their base metals portfolio. S32 produces a wide range of commodities including bauxite, alumina, aluminium, copper, silver, lead, zinc, nickel, metallurgical coal (used to make steel) and manganese.
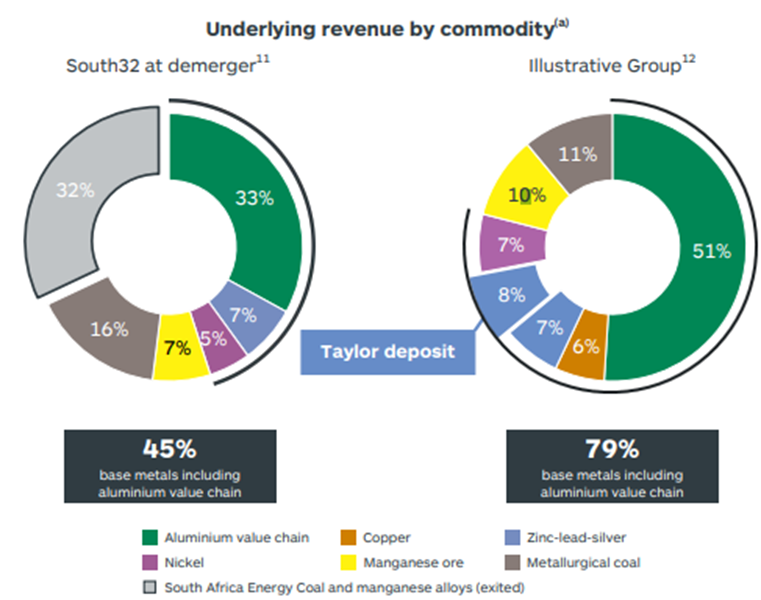
Source: 2024 Half Year Results Presentation
Since listing, S32 has transformed their commodities portfolio from 45% base metals to 79% base metals and added copper to the mix in FY22 by acquiring a 45% non-operational share in the Sierra Gorda open pit copper mine, located in northern Chile. Post the impending sale of their Illawarra Metallurgical Coal asset scheduled for H1 FY25 to Golden Energy and Resources Pty Ltd, their exposure to base metals will be 90%. The basis of this transformation, according to S32, is to increase their exposure to minerals that are critical for a low-carbon future.
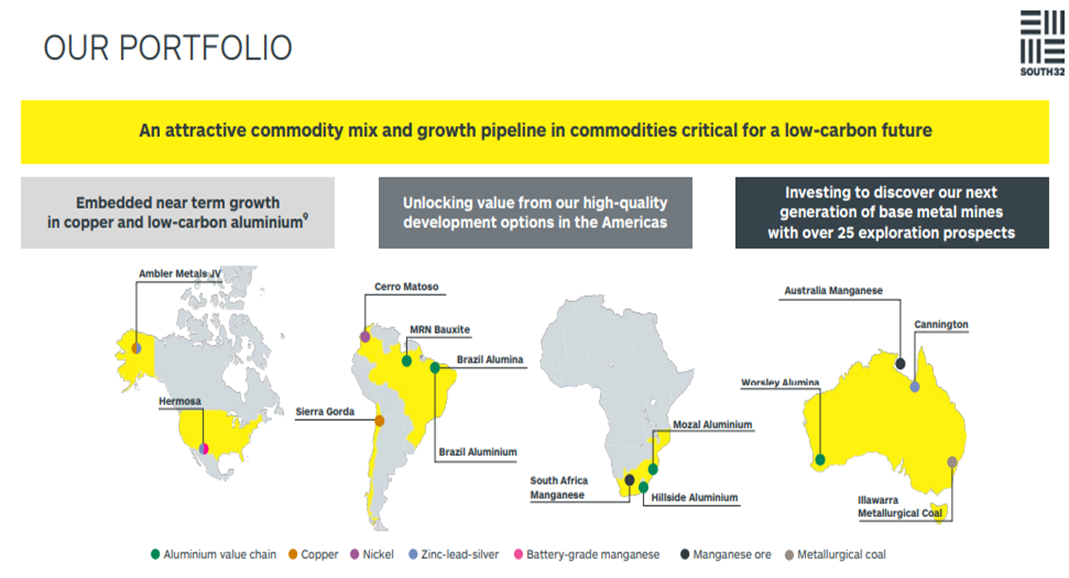
Source: 2024 Half Year Results Presentation
S32 also has two development opportunities in North America and several partnerships with junior explorers around the world. One of their North America development options is the Hermosa project located in Arizona USA. This project is home to the Taylor Zinc Deposit (also containing lead and silver). S32 announced the FID for the Taylor Deposit in Q1 2024. S32 sees Zinc as a critical part of a low carbon future as it is used to weatherproof (galvanise) building materials used in the construction of renewable energy infrastructure. According to S32, there is a supply deficit for zinc due to increased demand:
“With global zinc demand growth expected to outpace production by ~3Mt to 2031, we expect higher incentive prices for zinc as Taylor ramps up to nameplate capacity.”
S32 believe the Taylor mine has quite favourable economics and once up and running in H2 FY27 has a 28-year mine life, will hit nameplate production in FY30, and they have allocated US$2.2bn in capital expenditure to progress the mine into production phase. Once producing at nameplate levels, the mine is expected to generate average annual EBITDA of US$400m at a 50% EBITDA margin and produce US$320m of annual average net cash flow. Furthermore, progressing the Taylor deposit to a producing mine is only the first stage with key infrastructure constructed during this phase expected to open further growth opportunities in battery grade manganese and copper at the Hermosa project.

Source: 2024 Half Year Results Presentation
By far the largest part of S32’s base metals exposure is their aluminium value chain. S32 has operations mining bauxite and refining alumina in Australia and Brazil and smelters producing aluminium in South Africa, Mozambique, and Brazil, and operate the southern hemisphere’s largest aluminium smelter.

In FY23 their aluminium business was responsible for generating $4.6bn or 49% of total FY23 revenue of $9.3bn and their soon to be sold coal business generated 17% or $1.6bn of FY23 revenue. In short, the last 5-years have been a rocky ride for S32 and shareholders, as earnings and profits have fluctuated from year to year. The main driver of this has been COVID, the Ukraine War, and recent fall (off their highs) of commodity and base metal spot prices.

However, a quick look at their StockReport shows that S32 has generated positive operating cash flow through this period. This indicates that some of the losses reported have been partly due to non-cash items.
StockRank:
Looking at the last 5-years of their StockRank movements, we can see S32 has been a consistent performer with an overall StockRank in the 90s to high 80s, highlighting the strong underlying performance, and of S32’s ability to keep producing positive cash flows through this period. This performance peaked in FY22 on the back of COVID and the Ukraine war pushing the prices of commodities and base metals up.

However, FY23 and the start of FY24 have been a different story as higher costs and lower prices resulted in lower earnings, margins, and profits for S32. And as you would expect S32’s StockRank has fallen from its highs to 56. With not much to talk about when it comes to value and quality.

April 2024 StockRank
Encouragingly though, and on the back of more robust numbers from their HY24 report and most recent quarterly update, the proposed sale of their coal asset, and more favourable outlook for base metal prices. S32’s momentum has seen a 13-point increase over the last 30-days. Something that could weigh on this is a broker on 23 rd April downgrading S32 to neutral from buy. S32’s share price has also started to rise again. For the record, I hold S32 shares and bought them at $2.94.
Financials:
Due to S32’s inconstant financial performance and reported net losses their F-Score is languishing at 4 out of 9. However, their score of 4 is a result of their ability to generate positive cash flows, not issuing shares, and low debt levels. In fact, they have recently completed a share buy-back reducing the amount of share on issue.

I don’t have any concerns about S32’s Z1-Score edging into distressed territory given their proven ability to generate positive cash flows, low gearing, fair current ratio, and excellent interest coverage ratio. Something to keep an eye on is S32 has increased debt levels in recent years. However, S32 did note in their most recent quarterly report net-debt reduce by US$154m to US$937m. I would expect this to continue as their financial performance improves.


Furthermore, I would also expect their financial health numbers to improve in line with S32’s improving financial and production performance in future years.
Liquidity and Ownership:
With a market cap of $14.3bn at the time of writing and over 4bn shares on issue. S32 are at the big end of town and have plenty of shares to go round. With top shareholders only accounting for 19.47% of shares on issue and their top shareholder holding just 6.10%. A smaller DIY investor will have no issues getting in and out of the stock and the opportunity to build a position in the stock is very attainable.

Outlook:
Some commentary from S32’s CEO (Graham Kerr) from their recent quarterly report released to the market on 22nd April 2024 sheds further light on S32 at the minute:
“We also announced our decision to sell Illawarra Metallurgical Coal for up to US$1.65 billion, which will realise significant value, further streamline our portfolio and unlock capital to invest in our high-quality base metals projects.”
“This quarter, we delivered improved operating results, highlighted by record year to date production at Hillside Aluminium and South Africa Manganese and a 60 per cent uplift in quarterly volumes at Illawarra Metallurgical Coal.”
“With the exception of Australia Manganese (due to cyclone Megan halting production), our FY24 production and Operating unit cost guidance is unchanged, placing us in a strong position to capitalise on strengthening market conditions for many of our key commodities”
This comes on the back of S32’s HY24 report released in Q1 2024, Where they saw return to positive profits and reported a net profit after tax of $53m and net operating cash flows of $203m. Furthermore, consensus estimates are forecasting the return to positive profits to continue with FY24 and FY25 profits expected to come in at $372.5m and $887.2m respectively. Also encouraging for investors is, 13 out of 15 brokers who cover the stock have a buy or strong buy recommendation.

Conclusion:
Before investing in S32, one does need to consider that weather events and project delays among other things can cause production issues and negatively impact S32. Also, mines are diminishing assets and investor are reliant on S32’s ability to keep developing mines and bringing on new production flows to replace old ones. However, on the back of recent results and their pivot towards base metals, things are on the improve at S32 and it looks like they have recovered from recent lows. With the firming of commodity and base metal prices and S32’s strategic position within these markets (green and brownfield). Coupled with S32’s low debt, ability to produce positive cash flows, and freeing up of capital post the sale of their coal asset in FY25. S32 are set to capitalise on the increase in demand for their base metals for many years to come.
Important Information: Stockopedia Ltd ABN 39 757 874 670 UK business registration number 0637267 (“Stockopedia”) is an Authorised Representative of Daylight Financial Group Pty Ltd ABN 77 633 984 773 (“DFGPL”) which is the holder of an Australian Financial Services Licence (AFS Licence No. 521404).
Information in this commentary is current as at date prepared unless otherwise stated. However, please bear in mind that investments can go up or down in value, and that past performance is not a reliable indicator of future performance. For more Important Information please refer to the Disclaimer section of this website.
This communication may contain general financial product advice. It has been prepared without taking into account your personal circumstances, and you should therefore consider its appropriateness in light of your objectives, financial circumstances and needs before acting on it.
If our advice relates to the acquisition or possible acquisition of a particular financial product, you should obtain a copy of and consider the Product Disclosure Statement (PDS) before making any decision.
The author holds interests in S32. This position can and will change at any time without notice.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
4 comments
Appreciate Anton's commentary on S32 road to recovery and establish as a significant player in the Future Facing Base Metals. Last couple of months have been volatile, pleased to note that the share price is recovering. I too believe S32 has a promising future, being a S32 shareholder myself, sincerely hope S32 wisely invest the proceeds of the Illawarra Sale to consolidate its future as a powerhouse in mining.
I echo your thoughts there too, Chulani. S32 have done some heavy lifting to position themselves strategically in base metals and will get a timely cash injection from the sale of their coal business; hoping they stay the course and use the funds prudently by investing them back into existing and future projects.
Thanks Anton, great article. I was surprised that Australia Manganese being taken out of action didn't have much impact on the share price. Particularly considering they generated $67 million in EBIT IN H1, and presumably will require additional CAPEX to bring the jetty infrastructure back online. I suspect the market is anticipating it will be covered by insurance. Obviously, as a diversified miner, these events don't tend to move the dial as much as they would for a single commodity producer.
They had made an announcement prior to their quarterly regarding their Australian Manganese mine halting production, but at that stage S32 was unsure for how long. Yes, I agree, how soon they can get Manganese shipments flowing again is of concern and if they can or how much they can replace the cash flows from their coal asset will be interesting too. I will be a very keen reader of their full year report, that's for sure.