Safeland PLC: Profitable Nano-Cap Trading At Half Of Its Net Current Asset Value

Summary
• Stock meets Benjamin Graham's 'net-net' criterion: current assets minus total liabilities are greater than 150% of market capitalisation
• Almost 10% of last year's net income has been spent on stock repurchases so far in this financial year
• Net income for FY 2017 was £2.3m; current market capitalisation is £7.8m
• Management has excellent record for increasing net asset value and generating returns for shareholders
Company Profile
Safeland PLC (SAF:LN) trades, refurbishes, develops and invests in property. It seeks to add value to properties, in the short term, through redevelopment and by improving management.
Four companies, whose services range from property insurance, management and architecture to storage space, workspace and operating hostels, have demerged from Safeland between 1996 and 2014. The company's expertise lie in quickly identifying opportunities to buy properties that they can add value to by reconfiguring or changing use.
The stock is currently trading at 52p, which is half of its net current asset value (net of total liabilities) per share. The stock is very thinly traded, with only 138,012 shares changing hands last week. The bid/ask spread is currently 8%, but has been much lower when trading volumes have been higher, and many brokers are able to offer more favourable prices for investors to buy or sell at.
Management and Governance
The increase in Safeland's net asset value per share indicates that its management is capable of creating value for shareholders. It has grown consistently in recent years whilst a fair portion of profits has been paid as dividends.
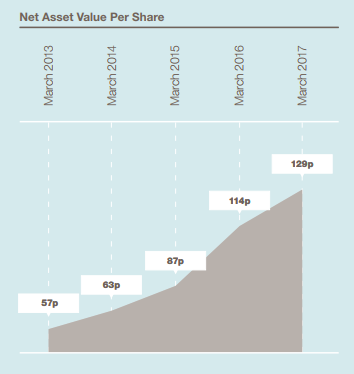
Source: Safeland PLC 2017 Annual Report
Safeland has redistributed profits to shareholders, through dividends and share repurchases, intermittently. The inconsistent dividend schedule is due to volatile earnings and the company identifying investment opportunities at variable times. Management have chosen to retain a higher portion of earnings on these occasions.
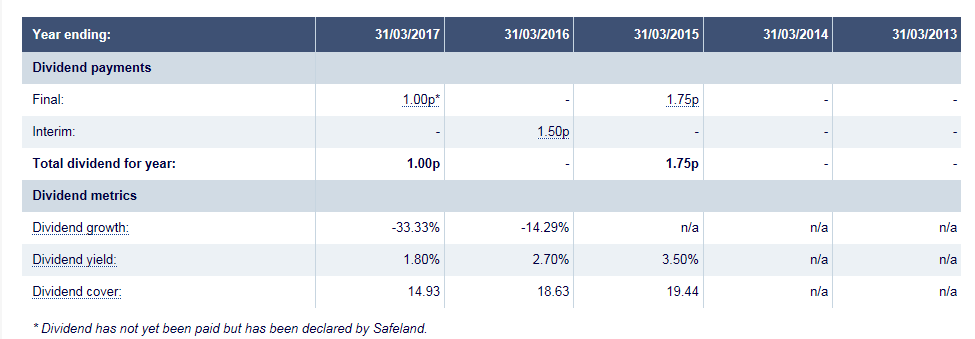
Source: www.hl.co.uk
Buying back shares in the company has signalled management's belief that the shares are undervalued. £65,000 of shares were repurchased in FY2016 and £10,000 in the following year. Since the financial year ending 31st March 2017, 380,000 shares have been repurchased and cancelled by the company at a cost of £214,672 excluding transaction fees. Companies that buy back their own stock tend to outperform.
There is significant insider ownership, which is encouraging for shareholders who can be confident that management are acting within their best interests. Executive director, Errol Lipman owns 4.58% of the company.
The two executive directors are part of the family that founded the business in 1986. The only non-executive director, Eddie Young, has been on the board since 2008. It is, generally, within the best practices of corporate governance to have the majority of the board composed of non-independent directors with a short tenure to mitigate the risk of the principal-agent problem.
However, the board appears to be acting within the best interests of shareholders by buying back shares and its recent record for generating returns for investors has been outstanding.
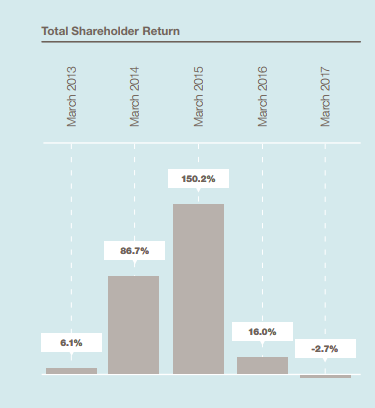
Source: Safeland PLC 2017 Annual Report
The directors of the company received less compensation in FY 2017 than the preceding year due to the departures of two executives. They are paid within the company's means and bonuses are linked to their performance.
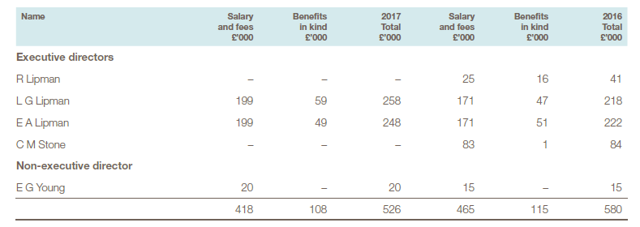
Source: Safeland PLC 2017 Annual Report
One key concern is the lack of clarity surrounding the £548,000 'Other expenses' under administrative expenses. These are significantly higher than in the previous year and there is no note in the annual report that details these costs.
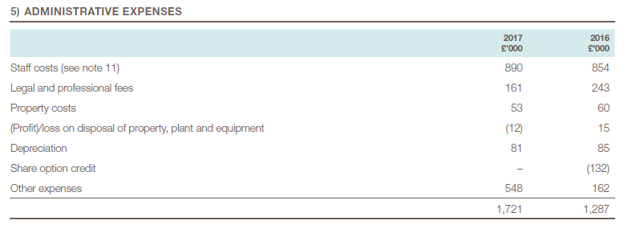
Source: Safeland PLC 2017 Annual Report
Profit for the year was almost half of the previous year, but £2.3m is still a good return on the 2016 net asset value of £17.7m. It is difficult for a small company in the real estate sector to consistently grow earnings as trading opportunities in the property market are not always present.
Valuation
Net cash inflow from operating activities was £4.7m for FY2017. This helped its cash balance rise from £3m at FY2016 to £5.3m in its latest filing. However, earnings quality cannot considered to be high, overall, due to the negative growth in revenue and operating income.
Revenues and profits have not been steady, so it is difficult to forecast financial data, but on an asset base, the stock looks considerably undervalued. It is extremely unusual that the company is trading at a discount to its net current asset value, considering it has been profitable for each of the past six years.
According the Bloomberg, the industry average P/E ratio is 10.6 and P/B is 3.6. Safeland's ratios are 3.5 and 0.4, respectively. With a return on equity of 13%, it does not seem reasonable that the company should be trading at any discount to its book value, and its P/E ratio should not trail its peers' so significantly. Therefore, it is logical to conclude that the intrinsic value of the stock is at least double its current level.
Potential Catalysts
Major increases in revenue may not be a realistic expectation. If the company had identified major opportunities in the property market, it would have retained a higher portion of its earnings instead of repurchasing shares. Catalysts for a share price increase are more likely to come from the stock being discovered by high net worth retail investors or institutional investors that do not have high liquidity requirements.
The next financial report is due to be released in November, but announcements of acquisitions, property sales or de-mergers could trigger an increase in the share price, which could be compounded by news coverage.
Risks
Price fluctuations in the property market in the UK have been prevalent for many years. The performance of the economy is a major factor in prices and there is considerable uncertainty surrounding the effect Brexit will have on the UK economy.
Increases in interest rates will increase expenses for Safeland as it uses bank loans with variable rates, but this risk has been partially mitigated with the use of derivatives. A tax rate increase that may occur when the UK leaves the European Union will also decrease profit margins.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
1 comment
Tom - thank you for the excellent writeup; couple of thoughts:
1. The large cap REITs - ie British Land / Land Securities etc are also trading below NAV. So perhaps it is worth considering how much discount one needs vs the large caps (especially given their REIT status) to justify buying a nanocap property co.
2. In the big cap space investors differentiate between eg London Offices, residential, retail (malls eg Hammerson), logistics and warehouses (eg Segro). Do you have any feel for the sector or geographical focus for Safeland.