Safestyle (SFE): A different flavour of IPO

 It feels like a lot of companies have come to market recently. Poundland, Pets at Home and Boohoo.com hold very little appeal for me at current valuations - and the whole IPO process is one which immediately makes me a little suspicious, anyway. There is one company which caught my eye enough (just post IPO) to give them a proper read through, though. I was planning to write this post last week, but the imminent publication of their full year results for 2013 gave me enough of a reason to sit on my hands and twiddle my thumbs for a while longer. I now look at them with a round 33% more financial data (four years of results instead of three!). Quite the boon.
Many of my UK readers will, I suspect, have heard of Safestyle. I might go so far as to read your mind with regard to the first thought, which I suspect will be this; one of those adverts so annoying it becomes memorable.
For those who don't know them, they are a manufacturer/distributor of windows. They're the largest seller of replacement windows in the UK, which is a market worth about £2bn a year and which has a surprisingly fragmented structure; their market share sits at 7.9%, with Anglian and Everest (which I assume are the other two in the top three) pooling 20% between them. The rest is made up of smaller, regional players. Their positioning - if you couldn't tell from the advert - is distinctly at the value end of that spectrum. From anecdotal experience, Safestyle are significantly cheaper than their competitors. The scale of that cost difference - as well as the incentives at work in replacement windows (how long are you planning to stay in the house for? How much do you care about quality?) likely explain Safestyle's continually increasing market share; 4.4% in 2007 and 7.9% now. The value proposition to customers appears to be sticking.
They manage all of this with a relatively slim amount of capital; their corporate structure is extremely (overly?) light on commitments. 'Asset-light' is a term you often hear, but with Safestyle it goes one step further; their door-to-door canvassers are self-employed, their installers are self-employed and their sales team is self-employed. Obviously, there are logistical and cost benefits to this, but I feel a little suspicious about it all. I think I read somewhere - though I might be wrong, so don't quote me on this - that the tax liability which they settled with HMRC just prior to listing came about as a result of these structures - when is an employee not an employee and so on.
You can make up your own mind about the benefits and shortfalls about the way Safestyle goes about doing business. Clearly, they're extremely efficient and relentlessly value focused, which are great things for a consumer in the market place. They also get a lot of flack for aggressive sales tactics and their employment structure, though, and these things are at least slightly entwined. These two factors are pulling my opinion in entirely opposite directions; the first is something I love to see in a company, since providing value for consumers will always drive growth. That is a bottom line - if you can sell a product at half the going price, people will buy it. On the other hand, companies which raise my eyebrows with some form of strategy - N Brown and their milking of customer finance charges, Cupid and their dubious dating site practices (which have apparently been disproved, but still) and this - they're all above board, but at least slightly unattractive. Regulatory and market pressures catch up with these sort of practices eventually.
Anyway, before it starts to sound too negative, I've slipped all the positives for a perfect bull case in here: it's a value-orientated, growing company with great returns on capital. What that means for investors is that, if they continue growing, relatively little of the profit generated will need to be reinvested to support that growth, leaving today's buyers sitting on a business which can both pay out plenty of cash to shareholders and continue to eat into more and more of that fragmented market. Not only that, but the market as a whole seems likely to grow in the next couple of years. Replacing windows is an expense which you can quite easily defer, and also seems likely to be correlated to the level of activity in the housing market generally.
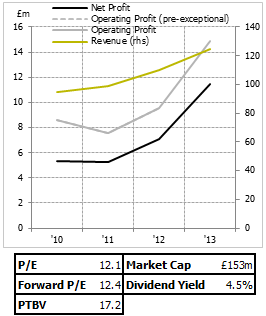
In that context, the P/E of 12 on which they currently trade might seem rather cheap indeed. They have, apparently, scope to expand production at their facility in Barnsley - something which, in combination with the business model being inherently cash generative and not subject to particularly long lock-up periods, should allow them to be generous with dividend payments.
I think it's an interesting one. I'm looking forward to reading their annual report. I'm a little ticked off I didn't clock it when it came to market (I didn't even know it had until recently), since I hope that at 130p I would've picked up the shares. At 50% higher I still think it's probably cheap, but I've got a few questions about the business I'd rather wait for a full annual report to answer. Perhaps I'm being irrational, but I still feel a little leery with IPOs in general.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
No comments yet
No one has commented here yet! Why not be the first one?