Sell rules - the key to locking in profits from multibaggers

Every investor loves to own a multibagger - a stock that rises to become many times its original purchase price. The problem is that we often sell these positions too soon, before they have a chance to appreciate in value. If we don’t sell, we sometimes get too complacent and hold on to them for too long, only to watch our profits vaporise as the share price falls further down the line.
The author of Contrarian Investment Strategies, David Dreman, argues that ‘even amongst the professionals, few religiously follow their own sell rules’, while many private investors don’t seem to have any at all. Fortunately, Dreman offers a solution. Let’s take a closer look, and use a recent multibagger, Victoria PLC, as a case study to test Dreman’s approach.
Taking the 'Round Trip'
Benjamin Graham, the father of value investing and the tutor of Warren Buffett, argued that Mr Market (an allegory for the stock market) had manic-depressive characteristics, shifting from euphoric moods one day to depression the next. These mood swings are represented on the chart below, where the share price (black line) oscillates around the intrinsic value (ie. true worth) of a stock, which is more stable over time.
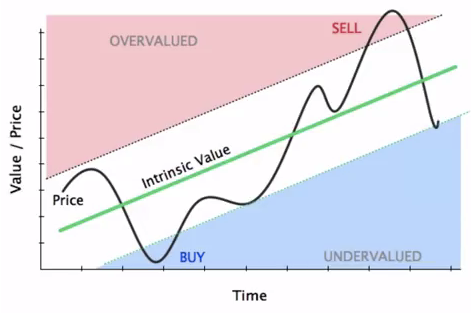
At the heart of value investing is the idea that investors should take advantage of Mr Market's mood swings and buy stocks when the share price falls below the intrinsic value. Investors should then sell when the price rises above its intrinsic value. This might sound straight forward, but David Dreman explains that ‘one of your most difficult decisions is when to sell’. It is sometimes tempting to hold onto stocks when they rise above their intrinsic value. Dreman observed that:
'If the stock was originally purchased at $20, with the sell target at $40, and it shot through $40, the manager would often bump the sell price higher. This frequently resulted in the manager taking 'the round trip': riding a stock all the way up, only to ride it all the way down again."
Mechanical Sell Rules to the rescue
To overcome this problem, David Dreman argues that investors should 'rely on mechanical guidelines, which filter out much of the emotional content of the decision.' Indeed, Dreman insists that investors should ‘pick a sell point when you buy a stock. If it reaches that point, grit your teeth, brace yourself, and get rid of it.’
It is crucial to understand that picking a sell point doesn’t necessarily mean selling a stock just because the share price has gone up. Dreman explains that ‘if you are a low price-to-book player, you may find that even after a stock has risen sharply, it still sells at below-market P/BV because its book value has continued to go up.’ He adds that prices may keep rising as stocks retain low valuation ratios (eg. PE or PB ratios).
- Dreman pays close attention to the PE ratio. He likes to ‘sell a stock when its P/E ratio (or other contrarian indicator) approaches that of the overall market, regardless of how favourable the prospects may appear.’
- Jim Slater pays attention to the PEG ratio. He explains that ‘I would try to buy shares with PEGs of under 1.0 and sell them at about 1.5.’
Selling simply because a company’s share price has risen might lead investors to miss out on greater profits. The stunning recent run in Victoria PLC illustrates this point.
Case Study: Victoria PLC
Victoria manufactures and distributes carpets - not exactly the kind of profile you’d expect for a multibagger. The company has been on an takeover spree in recent years, acquiring carpet manufactures like Whitestone Weavers, Abingdon Flooring and Globesign. Back in November 2013, the company traded at around 100p. An investor like Dreman may have decided to invest back then, when the company was cheap across many valuation metrics (see below).
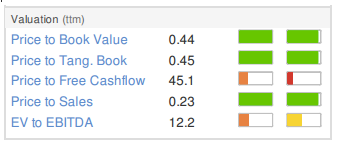
The company enjoyed a handsome rise of 20% between late 2013 and April 2014, when Victoria’s share price reached 120p. Investors could have sold the stock there and then, only to see it rise by more than 800% between April 2014 and now.
The better approach, to avoid being flushed out would have been to wait for the valuation to normalise. We can use the Stockopedia StockRank as a valuation measure (given that it is a blend of multiple valuation ratios) and look at its trend over time. Investors could have bought Victoria in early 2014, when the StockRank was 97, and held it until the StockRank dropped below 50, in February 2015. This would have enabled investors to benefit from mean reversion - the process whereby a stock’s valuation moves from extreme (ie. above 90) to the average/normal levels (ie. around 50). During the twelve months ending January 2015 Victoria’s share price rose from around 100p to 600p…
Holding beyond the ‘sell point’
The company is no longer exposed to the factors which have driven share price returns in the past. Back in February 2014, Victoria was a good, cheap, improving stock, with strong quality, value and momentum ranks, as you can see from the image below, but over time Victoria’s StockRank has now dropped to 45
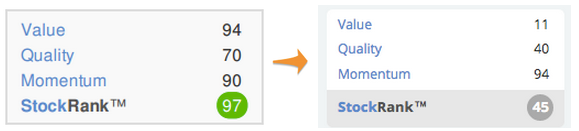
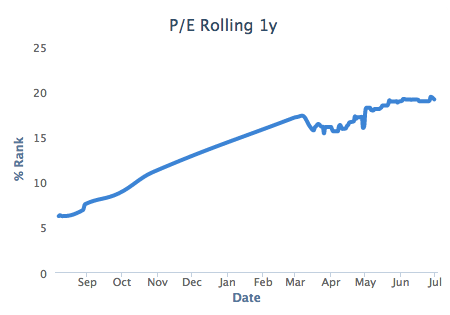
Victoria is starting to look like it has the characteristics of a Glamour Trap - a company with strong momentum (94), but poor value (11) and weakening quality(40). These stocks may be popular in the market, with strong share prices and sentiment. However, deteriorating fundamentals and stretched valuations can’t contradict forever. With a high price and poor earnings, the company may be exposed to downside risks. Indeed, an investor like Drehman would maybe be thinking about selling, as the company’s PE ratio has normalised. The Rolling PE ratio has risen from 6 in August 2014 to 19, where it stands today.
Conclusions
There are many stocks which have performed strongly over the last few years. Investors who hold these stocks should be assessing whether the companies still meet the criteria which led them to invest in the first case. If valuations have reverted back to normal then it's worth taking a long hard look at why they should still be held. Discipline is everything in investing, and sell discipline is the most important of all. Many investors may find it prudent to take a leaf out of David Dreman's book and put his contrarian sell rules in action.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
5 comments
How do you create the rolling PE chart on this share?
It looks a very useful one to create; are there any other ones that can be created by your software?
I really enjoyed this article. One of my weak points is knowing when to sell. I've been guilty of taking the round trip a few times.
Thanks Alex, I've been lucky enough to ride the momentum wave with VCP for some time now. Bought in around April last year, got a huge special divi and bought some more last summer. Can't really believe its now £10 a share after being at 160p at one point. I agree selling is the tricky part, but a while back I already topsliced my entire original investment, so everything that's left is pure multibagger profit.
Would be facinated to know what others think as its case of 'its starting to look fully priced' versus 'run your winners'.
It's definitely been an under the radar kind of share - if I could find a few more like it I'd be a very happy man.
Cheers, James
A very good & thought provoking article.
The way that I approach this is to:
1) Have a rigorous buying process to select the right growth companies to buy. Always follow it.
2) Have a rigorous selling process to select the right shares to sell. Like the buying process, it should be forward looking. Always follow it.
3) Monitor the holdings frequently. Any share whose prospects are in doubt should be put through the selling process. This applies both to shares whose prices may have fallen or may have risen many times over.
4) Keep making improvements to both the buying & selling processes.
These processes can be rather time consuming. Fortunately for me, I have the time and I rather enjoy the required research.
Thanks, interesting article on a share I have not looked at before. There is one thing that does concern me, 2 charts I looked at have the share going up to over 400p in about July 2014 before crashing down to around 140p, was there a share split? This is not shown on Stockopedia charts.
Yes I agree selling is difficult so this may help me.