September Stocks: Five Value Plays to Watch

Last month, I decided to begin listing value stocks I was interested in - ones that I perhaps hadn't covered yet, wasn't planning to for some reason, or numbers that just caught my eye as I cast my gaze down my various screens. August's list was rather monumental - a feat that I don't think I'll be able to match for quite some time. As I'm looking for diversity, most of the value stocks I discuss became cheap because of both a combination of company specific and sector-wide factors. But it'd surely be no fun if my 'value list' entirely comprised of all the UK housebuilders trading on small tangible books - that doesn't give anyone ideas, just reminds everyone that the housing sector is down in the dumps at the minute! And so, this month, I've aimed for 5 companies in different sectors, giving different types of exposure, but with one common theme - they all look cheap on an earnings or assets basis. Upon further investigation, I'll probably find most of these difficult to invest in for one reason or another; but throwing them out here at such an early stage helps show what I look at and perhaps will give fellow investors some ideas.
Capital Lease Aviation (LON:CLA)
This certainly comes under the 'interesting' category! CLA buy (using a large amount of debt) aircraft, which they then lease to other companies - Thomas Cook currently in possession of 3 of their fleet of 6. If you've ever wanted to own an Airbus, then, here's your chance for a slice of that - and you're getting a slice off the actual value, too, as the business is trading for 57% the value of its net assets. The structure of the business means it's currently highly cash generative - depreciation is its main 'expense', with huge cash flow spikes as a new aircraft is purchased and extremely strong inflow otherwise. Realistically, I know I can't invest - I'd want far more knowledge about the depreciation of aircraft, and Thomas Cook being in possession of half their fleet isn't hugely reassuring. With no fundamental knowledge of the aircraft leasing industry, I have no idea how easy it is to renegotiate leases, and industry dynamics are especially vital in a company as leveraged as this. For anyone with that inside knowledge, it may be worth a look.
Begbies Traynor (LON:BEG)
Begbies Traynor look like a nice counter-cyclical play - potentially a good hedge for my portfolio, whose top three constituents (Barratt, Howden Joinery (LON:HWDN) and N Brown (LON:BWNG)) are very closely tied to the whims of the British consumer. They popped up on Twitter a while ago as a fellow tweeter asked for potential 'recession' stocks - ones that'd benefit from a double dip - and my off the cuff answer, sticking true to my value roots, was Begbies Traynor. This nature comes about from their business - insolvency, restructuring, liquidation and risk management. Essentially, their pool of business grows as the number of failing businesses grows. The balance sheet is surprisingly sound for a professional services firm (which usually have few assets and substantial borrowings) , cash flow looks strong, and profits both last year and forecast are good. Last year was marred by a number of exceptionals which more or less saw them breaking even, though, so that'd have to be an area for further investigation. Founder Ric Traynor still sits on the board with a substantial shareholding, which is nice to see, and the dividend richly rewards shareholders, though it was recently cut. Curiously, on the day of writing, the share price has fallen 11% on ostensibly no news. That may be the incentive I need to take a closer look - Communisis were a similar story, with one large and determined seller thumping the price down ~20% in one day. Of course, I need to be certain it's not just a large piece of information I've missed!
Topps Tiles (LON:TPT)
Topps Tiles shouldn't need too much explanation - the clue is in the name, if you're unfamiliar with the business. The nationwide tile retailer looks to have been decently profitable over the last 5 years, with a good deal of consistency in their revenue figures. The recession, though, has significantly slowed profits down - and the issue of a profit warning earlier this year has sent their share price spiralling. As a value investor, I see this as a potential buying point - as it's entirely unsurprising they're not making as much money in this market, do I think the business is fundamentally sound and will return to strong profit when the market picks up? Cash flow is good, though the business unusually reports a net deficit on its balance statement. This doesn't particularly concern me, as it just means they haven't fabricated intangible assets such as 'brand value' to cover up a deficit of actual assets. While the business looks cheap, and I like the potential for improvement as the cycle naturally picks up, I can't help but feel Topps Tiles is a little old hat. I'm not really sure what niche they operate in, and I suspect bigger DIY chains are probably nibbling at their market as the years go by and the trend towards 'all-in-one-place' shopping continues. As with Johnston Press, large debts are worrying in declining industries, as debt ranks above equity in the capital structure. A declining profit stream paying off large debts may mean nothing left for the equity holder, so I would have to be fairly certain of a bounce back in profits - or at the very least, absolutely no further falls.
Chime Communications (LON:CHW)
I like marketing/advertising firms at the minute - both Creston (LON:CRE) and Communisis come under that broad niche, so it's unlikely I'll be buying more, but Chime look to offer some cheap exposure to the sector for those looking to take a stake. Profit figures look good and the company pays a reasonable dividend, and though tangible assets are unsurprisingly negative, they're not far into the deep zone - company working capital management seems good, enabling them to keep term debt (and therefore finance costs) to a minimum. My experience with firms of this nature leads me to very quickly look at customer concentration, which can be an issue, but Chime doesn't look too bad on that front from the figures I've seen. While organic growth remains positive, they're also gobbling up smaller firms - something I'm usually positive on in companies of this size - helping to contribute to their 5th successive year of operating profit and revenue increases. First half results point to a continuation of that upward trend, even in this difficult market, and so a P/E of around 7 seems like a very reasonable price to pay from my quick analysis.
Impellam (LON:IPEL)
Impellam Group are a diversified recruitment firm operating both in the UK and globally in a range of sectors - including healthcare, accountancy, hospitality, marketing etc. Their share price has experienced a strong rise over the last year - something that always doses me with a healthy sense of scepticism - but its metrics still look fairly reasonable, on a P/E of 7 and a forward of less than 6. Revenues have been very consistent in the past, with profit growth coming about from an improvement in margins; 'efficiency measures' and 'revenue quality initiatives' apparently making up this sharp increase. I can't see any huge red flags, so I suspect its flattening out is simply down to the scale of the share price rise and the depression in the recruitment sector at the moment - Morson, my slightly more niche pick, are even cheaper than Impellam. The lack of dividend is slightly disappointing with a firm of this size, especially considering my previous discussion about director interests. The directors emoluments are stuck deep down in the notes to the financial statements, and note the £1.6m directors' wage bill - of which £984,000 went to the chairman, Cheryl Jones. It's a rather healthy pay packet, though not ludicrous, but doesn't seem to be tempered against any share options or ownership. She therefore has no financial alignment with shareholder returns, and while I have no reason to distrust management, I don't particularly like the combination of factors set out. It looks to be a good company, but those are a few factors I'd like to tie up.
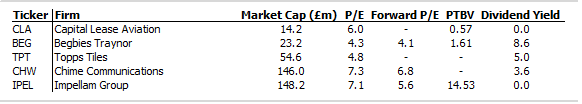
So there we have it - 5 potential value stocks for September. I suspect I may be looking into one or two in further detail in the coming weeks, so stay tuned for that - and as ever, drop me a line or leave a comment below if you've any points on my brief analyses.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
No comments yet
No one has commented here yet! Why not be the first one?