Seven Splendid Turnaround Stocks

In my last article, I wrote about how turnaround stocks may be a good place to invest right now and some ways to screen for these types of stocks. The screen I produced had 29 results. Here is a first look at seven of those:
Works co uk (LON:WRKS)
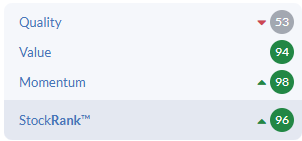
Investors will no doubt be aware of this chain of high-street shops. They describe themselves as "the retailer of affordable, screen-free activities for the whole family," which is a clever way of rebranding, given the evidence that excessive screen time can rewire children's brains in undesirable ways. This is one of the highest VM-Ranks, and when I reviewed it on last week's DSMR, I suggested this was only going to increase in the short term:
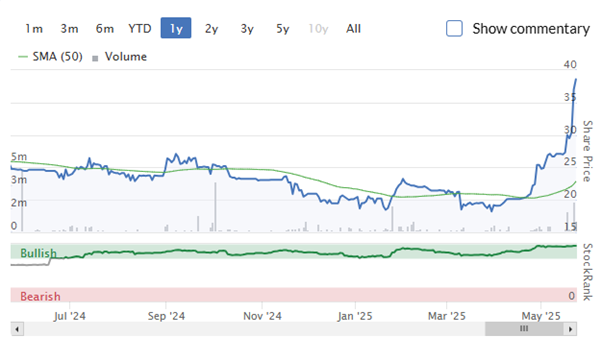
A strong recent share price aids the Momentum Rank:
In addition to the share price momentum, the company has recently demonstrated fundamental momentum by beating expectations. This is what they said last week:
Group compiled market forecasts for FY25 and FY26 are currently pre-IFRS16 Adjusted EBITDA of £8.5m and £10m respectively…
The Board expects that the positive momentum seen since Christmas will continue. This, combined with ongoing focus on product margin growth, cost management and execution of our new strategy, means we expect to offset significant cost headwinds and deliver profit growth in the year ahead. As a result, we are targeting profit growth in excess of current market expectations in FY26.
The upgrades look relatively small compared to a downgrade last year:
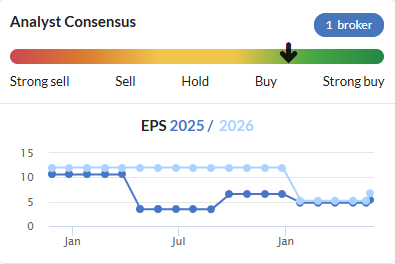
Although their broker, Singer, say:
The group's wide-ranging strategic and operational focus is starting to deliver results, with evidence being seen in Q4 in sales, margin and cost efficiencies. This leads to guidance being upgraded, and we have raised FY25/FY26 EPS forecasts 12%/30% now with a 25% CAGR.
So, this was a sizable upgrade for FY26. I think the strength of the reaction was because the market had expected them to miss expectations rather than beat them due to the general UK retail malaise. The company remains very cheap on many measures despite the recent share price moves:
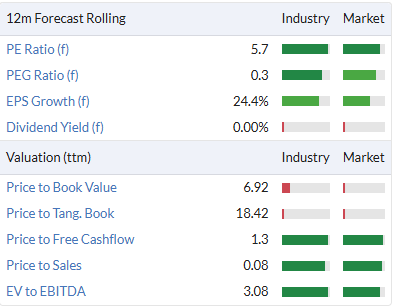
The lack of asset backing and dividend payout are the only aspects that aren't rated strongly green.
As with all "Turnarounds", the Quality Rank is relatively weak. Here, it reflects some weaker-than-usual safety measures. In this case, a low current ratio adds to the risk:
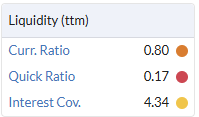
Many retailers successfully trade with negative working capital, so this isn't necessarily something to worry about as long as the sales don't decline. Forecasts for sales growth in FY26 suggest this shouldn't be a problem in the short term.
Bear Points
- When investing in Momentum stocks, investors tend to like smooth share price trajectories. Instead, here, all the rise has occurred over the past month. Over very short periods, such as this, share prices tend to mean-revert rather than continue trending, so investors may want to wait for a retracement before investing.
- The recent ahead-of-expectations statement for FY25 was based on adjusting out the cost of dealing with some online delivery issues they had in the run-up to the Christmas period. Including the impact of these would have led to them missing the EPS forecast. These costs appear to be genuinely one-off, and the company has also upgraded its FY26 expectations, which should result in a much cleaner set of numbers. However, investors should keep a watchful eye on the real underlying economics here.
- At the half year, lease liabilities exceeded right-of-use assets by £19.2m. This means that a significant number of stores must be operating at a loss. The good news is that this situation should improve with better store trading, and they have relatively short leases. However, onerous lease costs remain significant compared to their market cap.
Summary
As the recent market reaction has shown, this had simply become too cheap, with investors worried that the company might miss expectations. With an upgrade arriving instead, the price has taken off. While that helps drive the Momentum Rank higher, I would be a little wary of chasing very short-term momentum, as the academic evidence suggests that this is more likely to reverse. With a longer-term view, it seems the shares may well continue to do well from here.
Wynnstay (LON:WYN)
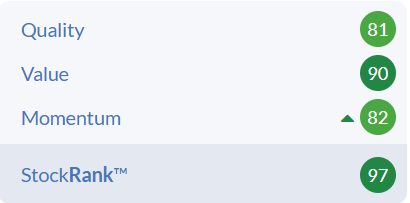
Agricultural distributor Wynnstay has a very high Stock Rank. This is because it is cheap and conservatively financed. It also has an increasing Momentum Rank, making it a potential turnaround stock:
The cheapness here is primarily on the asset and cash flow side:
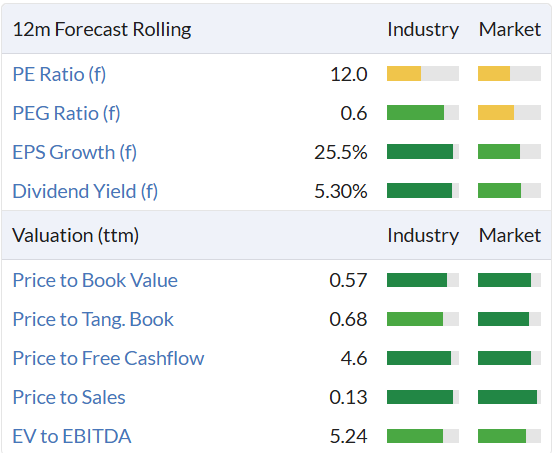
The earnings multiple isn't necessarily cheap in the current UK markets. However, this is a cyclical business, and this reflects the ups and downs of supplying the farming markets:
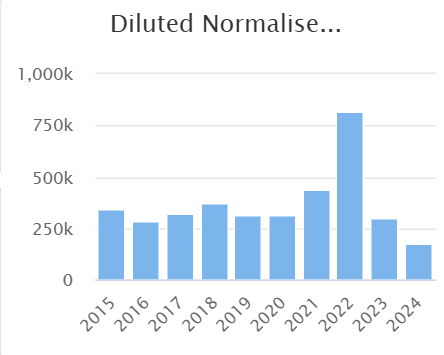
Anyone who has watched Clarkson's Farm knows the impact the weather and changes to government financial support schemes have had on farming over the last couple of years. This is reflected in the downgrades last year:
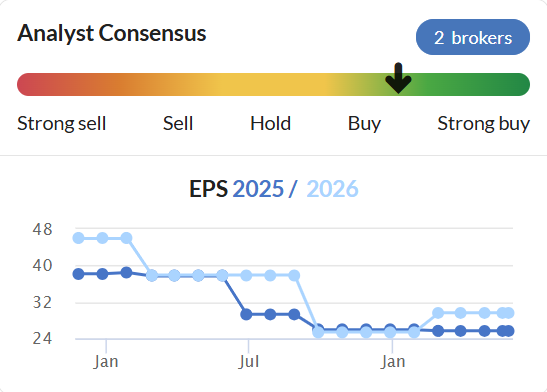
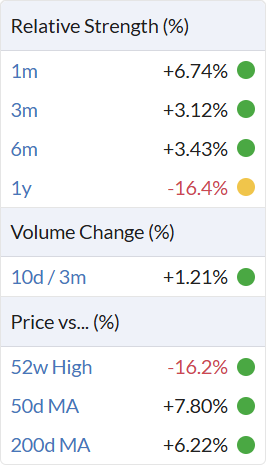
This means while many of the Momentum indicators here are green, they are not particularly strong:
Bear Points
- While the Momentum Rank is improving, and the share price is above its 200d MA, the 1-year relative strength is still negative. Turnaround investors may want to wait until there is a clearer uptrend before investing.
- While there is undoubtedly the ability for the company to generate higher returns on assets than it currently does, it has never generated particularly high levels. Indeed, the returns on capital have only been acceptable during peak trading periods. There is a risk that this means that the assets are not worth what they are valued at on the balance sheet, which may impact the discount to TBV and potential upside.
Summary
While the assets here have never been particularly productive, there is scope for earnings to continue to improve with better market conditions for farming. I don't think this will ever shoot the lights out, but the continued modest cyclical momentum should reinforce that recovery.
Phoenix group (LON:PHNX)
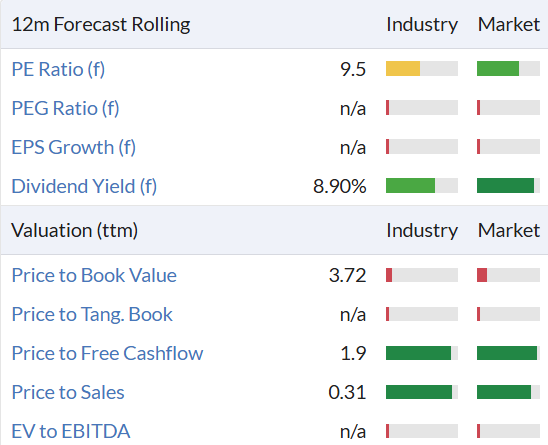
Phoenix is primarily a defined benefit pension scheme consolidator, although increasingly, it has been focusing on the asset management side of the business. This is behind the company's consideration of rebranding to Standard Life, the name of a well-known company it acquired in 2021. Consolidating pension schemes is a great business. By having bigger pools of pension scheme members, the range of possible actuarial outcomes is reduced, which frees regulatory capital. Additionally, there is a scale advantage in scheme administration. Then, with the assets managed internally, there is a scale advantage to providing investment returns. This dynamic makes Phoenix a cash machine, as is reflected by the very low P/FCF and high dividend yield:
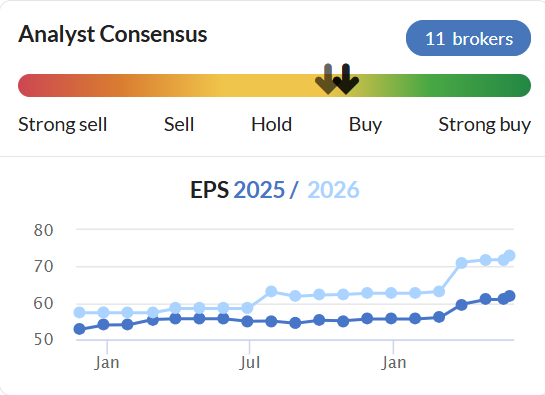
The complexity of the accounting means that EV measures and even EPS are not always a good measure of underlying value. Still, the EPS trend does reflect how the business is performing:
And it is this trend that has been reflected in the share price recently:
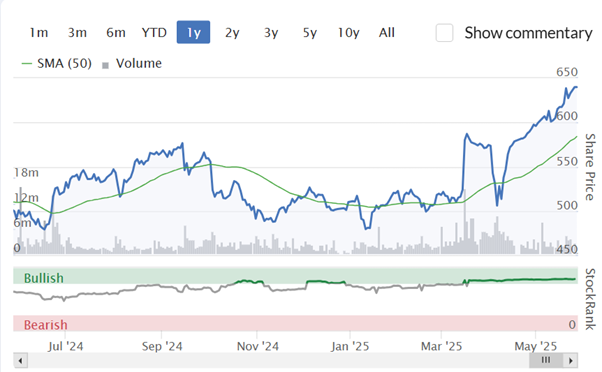
This has given the stock its strong momentum characteristics:
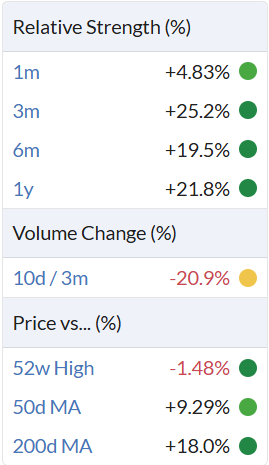
Which is reflected in the Momentum Rank of 99:
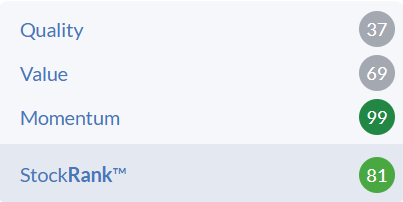
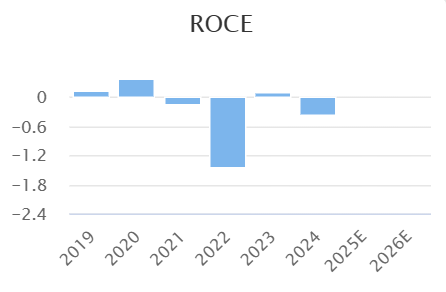
The cheapness of the stock and its quality may not be fully reflected by the ranks. Again, due to the complexity of the accounting, measures such as ROCE don't really measure the underlying quality of the business:
Bear Points
- In some ways, this is a bit of a black box. Individual investors are unlikely to be able to gain an informational or analytical edge.
- There is a more limited pool of large pension books that Phoenix can consolidate, which limits its ability to grow in this way in the future. This is behind the increasing push to be considered an asset manager.
- The share price has been quite volatile. This reflects its position as an asset manager. It is very exposed to market returns, currency and interest rate moves. If the global markets take a tumble, investors can expect those moves to be exaggerated by the share price.
Summary
It would be hard for investors to understand Phoenix better than a professional analyst. This means that investing in Phoenix is about thinking longer term than the average market participant and trusting that the great cash flow and 9% dividend yield demonstrate undervaluation. In the past, the lack of growth from pension consolidation has deterred many investors. However, with a potential rebrand to highlight the growing asset management part of the business and momentum now building, it seems that other investors may be reconsidering their stance on this.
NWF (LON:NWF)
NWF is another farming distributor. However, in this case, the bulk of the turnover comes from fuel distribution rather than feeds. This means that they have a very low operating margin:
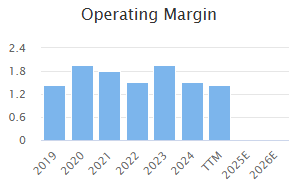
But reasonable ROCE as they turn over their inventory very quickly:
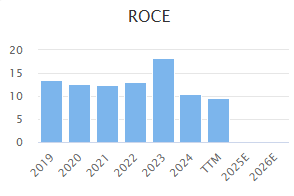
Recent ROCE figures have declined recently but will return to a reasonable figure if earnings recover as forecast:
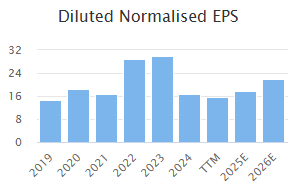
This cyclical recovery will also make the shares look very cheap:
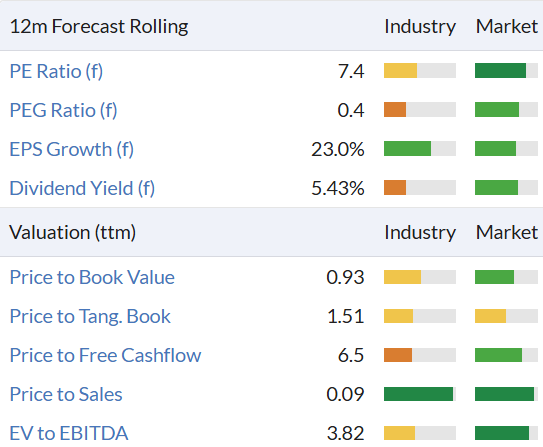
Indeed, the Value Rank may be even higher than its already strong 91 if the company were not classified as an Oil & Gas business and hence measured against oil and gas producers that have limited asset life.
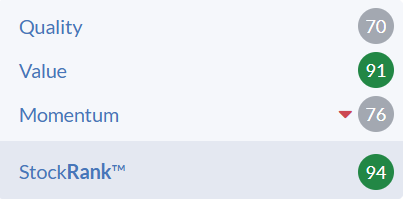
There is less good news on the Momentum front, with the Momentum Rank having fallen recently. There has been no downgrade in earnings expectations:
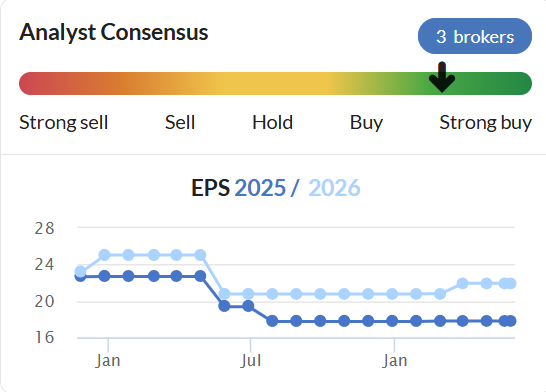
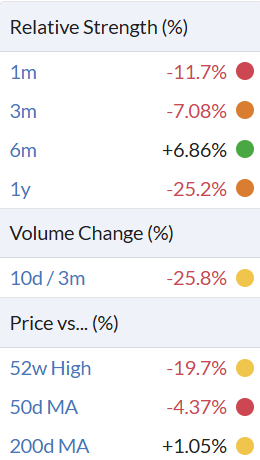
So it seems that the downgrade is caused by the slightly declining share price in a rising market, meaning the relative strength has weakened:
Bear Points
- The biggest bear point is that the company's shares have remained range-bound since listing:
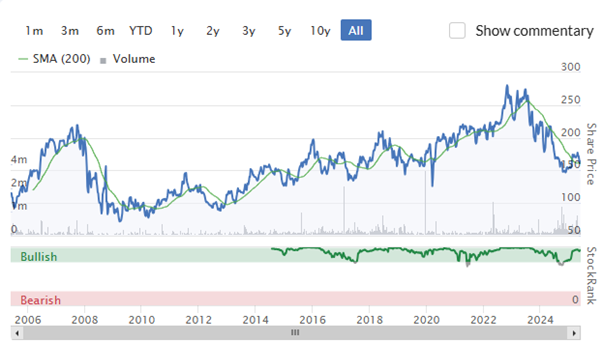
- While a volatile but range-bound share price in a cyclical business is not without opportunity, it suggests the ultimate upside here is limited.
Summary
The company trades on a rather modest forward P/E, and history suggests that there could be further growth in EPS in this cycle. However, despite modest upgrades in forecasts, the shares have declined over the past month or so. This may mean that investors who are close to the industry see increasing headwinds. However, with an £80m market cap, this may just be noise. Pure value investors will see this mismatch between the forecast and price direction as an opportunity. However, the turnaround investor may want to wait for a stronger Momentum signal, either from further forecast upgrades or more positive medium-term relative strength indicators.
Shearwater (LON:SWG)
Shearwater is a cybersecurity software specialist. Given the increasing focus on this area following recent high-profile attacks, it is a little strange to see such a company on a Value-based screen, with an above average Value Rank:
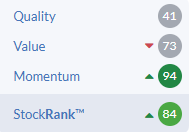
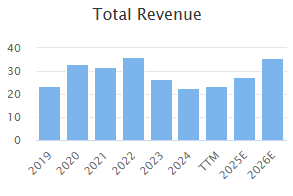
It is worth noting that this buy-and-build business is more of a distributor and implementation specialist than a software creator. There are a couple of reasons that it is not more highly rated. The first is a rather lacklustre long-term revenue trajectory:
The second is that there may have been an overhang from the largest holder selling:
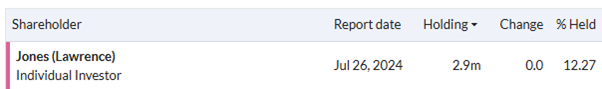
The backstory is that Jones has been jailed for historical sex offences. There have been no holding announcements, so it is possible that there has been no selling, and merely the possibility of an overhang has weighed on the shares.
The high Value Rank is dependent on the company hitting future year forecasts:
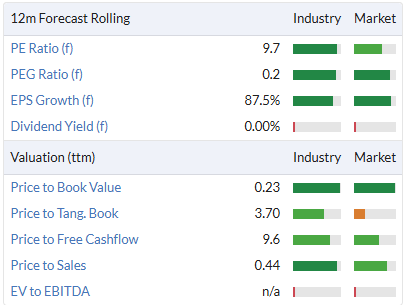
However, it is also worth noting the low P/BV. This is all goodwill related to the acquisitions made to build the business, and typically, value investors would ignore intangibles. My own view is that, in hindsight, they probably overpaid for the acquisitions, but not to the extent implied by the discount to book value.
This is another company where the market appeared to have priced in a miss, but the company reported that it would be trading ahead on revenue (and in line on EBITDA) in its latest update in January. However, they also changed their year-end to avoid what they claimed was significant volatility around contract awards close to their previous year-end. This does make comparisons more tricky, though.
One factor that may improve the valuation metrics is that their broker, Cavendish, are forecasting them to have £5.6m net cash on 30 June 2025, rising to £7.0m on 30 June 2026. Like many software companies, they receive a degree of upfront payment. However, this is forecast to remain fairly consistent, making this genuine cash flow generated by the business and a double-digit FCF yield.
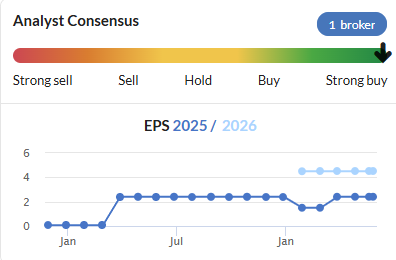
Given the recent rise in share price, the Momentum Rank is the strongest here. The fundamental momentum is rather modest:
However, the price momentum is strongly green for almost all metrics:
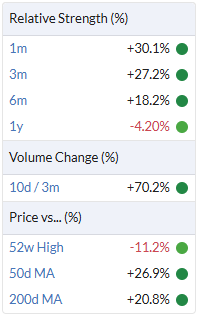
Again, this suggests that the price is simply recovering from an extremely oversold position. This is another case where shareholders may need to be wary about short-term mean reversion. However, compared to The Works, the short-term rise is more modest, so less at risk of a short-term pullback.
Bear Points
- I never like a company that moves its year-end. While it may be sensible in this case, it also makes comparison between periods much harder. Year-end changes are often done when this comparison would be unfavourable.
- Despite having a significant net cash position, the company doesn't pay a dividend. While this is normal for a growth company, this business has been listed for a long time. I suspect they want to retain cash for further acquisitions, for which they have a slightly patchy record.
Summary
Although the share price has been strong over the last month or so, this appears to me more about a correction from an extremely oversold position than excessive froth. The long-term record here is somewhat patchy, but the shares have broken into profitability, thanks in part to a year-end adjustment, with further strong growth to come. Despite this, and the company being in the cybersecurity software industry, an area in high demand, the forward multiple is very modest. This looks even better value when you consider that they are forecast to hold over 60% of their market cap in cash in a year's time.
James Fisher And Sons (LON:FSJ)
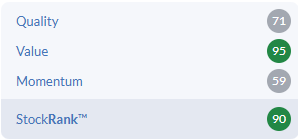
When I wrote about the turnaround screen, I had a request to look at James Fisher. This is an engineering services company supporting the Oil & Gas, Defence, and Shipping industries. I've got to say, that I am a bit mystified by the high Value Rank here:
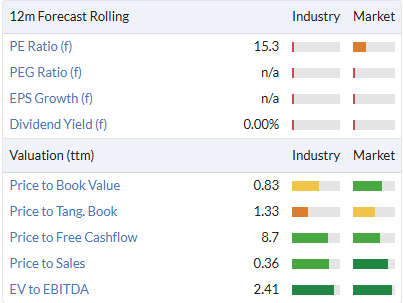
While some of the metrics are inexpensive, the P/E ratio, in particular, remains quite high:
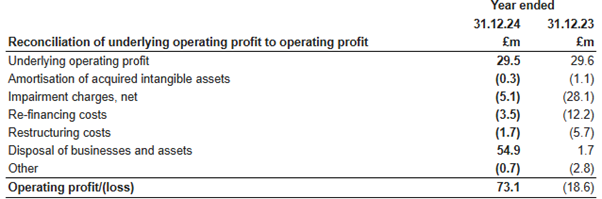
The broker coverage isn't accessible on Research Tree, which makes it hard to see what's behind these forecasts, and it is also a business in considerable flux. As the results show, there have been considerable disposals, restructuring and refinancing:
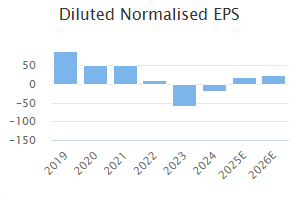
Disposals have helped rebuild the balance sheet but also will limit the recovery earnings potential, and I don't think we can assume they will return to the c.50p levels of EPS seen in 2021:
The good news is that management are specifically talking about this process as being a turnaround:
Our focus for 2025 is to deliver on the next chapter of our business turnaround, progressing on a path towards our UOP strategic target of 10% and our ROCE target of 15%, through a combination of further self-help, improved business unit performance, supply chain integration and revenue recovery for the Defence Division.
However, I can't help but feel that a 10% operating profit margin isn't particularly good. Based on current forecasts, it would be around £43.6m operating profit. This represents a notable improvement over the current level. However, that would mean they trade at around six times the target EBIT on an EV basis. This doesn't seem especially cheap, considering there is a lot of work still to do to get there, and likely to still face sizable adjustments to get to the underlying figure.
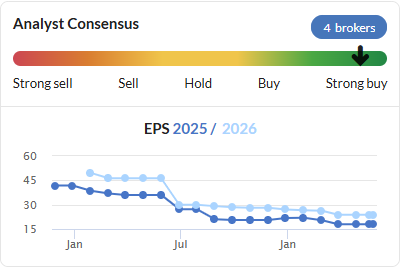
The earnings consensus isn't exactly encouraging, either:
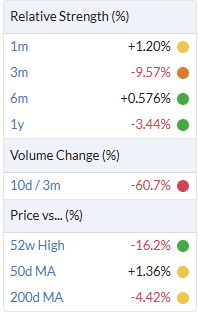
And with quite mixed price momentum, the Momentum rank of 59 seems about fair:
Bear Points
These are self-evident. It isn't particularly cheap, even if they hit their medium-term target. Nor is the Momentum Rank particularly strong. This scrapes into the turnaround category, and as such, it would seem that there are better VM-Rank plays out there.
Summary
I probably wouldn't have looked at this unless I had been prompted to and it is always useful to look at a stock I haven't covered before. While having a management team committed to the turnaround process can be half the battle, it is a very complex situation with many moving parts, including divestments and numerous adjustments. Even if medium-term management targets are met, it isn't obviously great value, despite the high Value Rank. As such, I am tempted to put this in that too-hard category. I may be missing a great turnaround stock hiding deep beneath the covers. However, so far, it is not evident to me that this is the case.
Distribution Finance Capital Holdings (LON:DFCH)
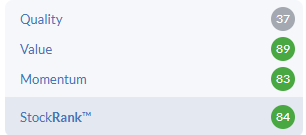
This was the second stock that was requested, and here, the Stock Ranks are more promising:
The Value RanK of 89 seems well supported by the metrics:
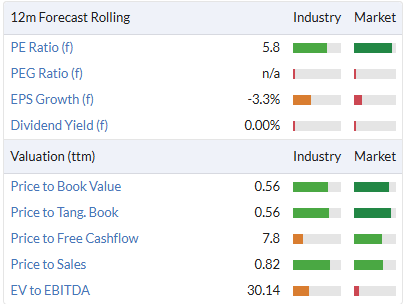
This is a supplier of finance to the leisure market, including caravans and mobile homes. Importantly, this is a bank, so it can take deposits as a (usually) cheaper and stickier form of funding. (I never really see the point of the type of finance companies that borrow from banks and then lend the money out again themselves.) So far, they lend to dealers but are hoping to expand to consumer finance in time. The good news is that this means they are not exposed to issues with motor finance redress that are currently plaguing other banks. As a bank, the key metric here is the Price to TBV, which looks too low for such a specialist lender. They are buying back their own shares, which makes sense if that discount to TBV is a true measure of the business.
Graham wrote up an interview he conducted with management here, which explained some of the nuances of running such a bespoke finance business.
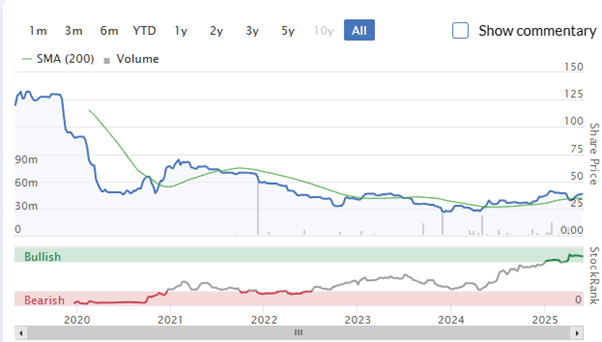
The performance since the IPO has been rather disappointing, but this is par for the course with floats – they rarely live up to initial expectations:
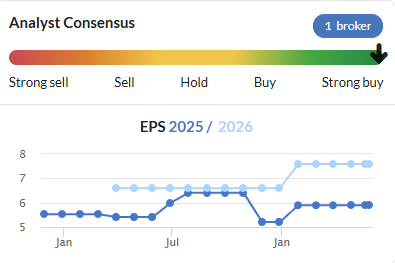
Today, we have some modest fundamental momentum, with broker upgrades in January:
In their Q1 trading statement, they said:
The strong momentum experienced by the Group continues with record quarterly new loan origination of £382m (31 March 2024: £330m), driven in part by robust demand across the motorhome and caravan sector. This has resulted in the overall loan book increasing by almost £50m since the year-end to £713m, representing a year-on-year increase of over £100m or c.17% (31 March 2024: £610m).
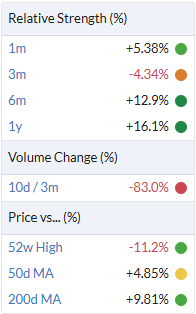
While this didn't lead to broker upgrades, it sounds like the business is performing very well. The price momentum is good but not outstanding. However, it has some positive attributes, such as the 1-year relative strength being the strongest and no short-term spike up that may reverse:
Bear Points
- As a bank, the comparisons should be with other banks. A bank like Barclays isn't too far away from the metrics we see here and is a much more diversified business. The flip side is that a smaller bank may be more nimble.
- There is no dividend paid, and the company is instead buying back shares and expanding its loan book. This means it is a growing business but is not without risk. Like all lenders, this is exposed to any deterioration in the economic climate, even if its current rate of arrears is relatively low.
Summary
I think this business has a lot going for it. While a rapidly expanding loan book is not without risk, it is the way that banks expand. In this case, they don't appear to have compromised loan quality in order to grow, so this will feed into positive fundamental momentum. Despite this, the company remains cheaply valued on earnings metrics and P/TBV. If earnings and book value continue to grow, the share price will likely follow suit.
[Disclosure: Mark owns shares in Shearwater (LON:SWG) ]
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

9 comments
Wynnstay (LON:WYN) definitely not going to shoot the lights out as a business as Mark says but the previous action shows can easily double from here...
Very useful article. Just for everyone’s information Wynnstay appear to have had a driver tragically die in what looks to be an incident at one of their depots. HSE and police involved but no outcomes yet. A quick review of HSE website will give some more information, but I imagine this could have some significant implications so just looking for details of any provisions being made.
Thank you, Mark, for this really helpful research. I have held WYN since 2021 and have attended two AGMs. I wholly agree with you. IMHO, rather frustratingly, it appears that at least one larger investor has been reducing their holding, for an unknown reason, without submitting TR1s in a timely fashion. Whether this is due to the tax treatment of AIM shares, I can only surmise. Comments welcome.
Wow, a fascinating collection of possibilities with calm considered appraisals. Thanks Mark.
Another great piece of analysis - thank you, Mark.
Under Phoenix, I think there's a 'not' missing in the sentence: The complexity of the accounting means that EV measures and even EPS are always a good measure of underlying value.
Thanks, now corrected.
NWF (LON:NWF) I wouldn't place too much emphasis on the recent slight fall in momentum rank. Momentum rank is inherently noisy compared to quality rank as can be seen in this chart. Since the results in Feb, the momentum rank has increased.
Where did you get this chart from? I personally would love to see charts showing the Momentum, Value and Quality ranks over time, as then you could assess whether you could use these to assist in stop loss placing.
I have been collecting the data myself. Unfortunately not available on Stocko, although they must have the information.