Shearwater - delivering on its upselling aim
Analyst’s view:
The initial market reaction this morning may seem excessive for a contract of this size, and a re-iteration of in-line trading. However, there are several reasons why this may be a positive development. The key point management highlights is that it provides evidence that Shearwater can generate growth by selling additional services to existing clients, not just by winning new clients. This potentially bodes well for upselling to other clients.
The current cybersecurity backdrop is highly supportive of these efforts. Which, combined with very modest forward multiples for a company forecast to generate at least mid-teens percentage CAGR EPS growth over the next few years, means that I am in no rush to reduce my position, nor our mostly positive view.
+11% to 71p (£15.3m) - Contract expansion with major UK telco
This sounds like a sizeable contract win:
...group company, Brookcourt Solutions Limited ("Brookcourt"), has secured a strategic three-year contract with a major UK telecommunications provider, with a total value of approximately £9.2 million.
However, it is worth reminding ourselves that this is largely a value-added reseller of cybersecurity software and hardware. Results released at the end of last month showed revenue of £42.3m but Adjusted EBIT of just £1.3m, for a 3% EBIT margin. This isn't out of place for this type of company. Indeed, Computacenter reported just a 2.2% EBIT margin in its recent H1 results, and still trades on a high earnings multiple. Low margin businesses are not necessarily poor quality ones. Like Computacenter, Shearwater doesn't just pass on someone else’s technology; it provides specialist engineering, systems integration, consultancy, and a complete managed security services offering. These types of resellers, however, are ones where headline sales figures matter far less.
With revenue recognition roughly over the period of the contract, this is said to support market expectations, rather than enhance them:
The agreement has a total value of approximately £9.2 million over three years, of which c.£ 3.0 million is expected to be recognised in FY27, supporting delivery of market expectations for the period with the remaining balance providing the Group with enhanced revenue visibility through to October 2029.
In light of this, it is tempting to view this morning's 10% or so rise in the share price as excessive. However, I think there are a few reasons why this may not be the case:
The strategic impact:
The company has a long history of working with UK Telcos, and although they never name clients for specific contracts, they supply to all the main UK players. The problem is that, in the past, this level of work has led them to just about break-even. Future growth depends on winning non-Telco business or expanding what they do for existing clients. This is why the CEO describes this win in those terms:
This is a strategically important award for Brookcourt and an excellent example of the model we are building across the Group. Our strategy is not simply to win individual technology contracts, but to establish trusted positions within major organisations and then expand those relationships by addressing a broader range of their cybersecurity requirements.
The good news is that with AI hacks making the headlines daily, the environment for upselling cybersecurity services is very supportive. Seeing the company do this suggests more of it to come across its established customer base.
The results hangover:
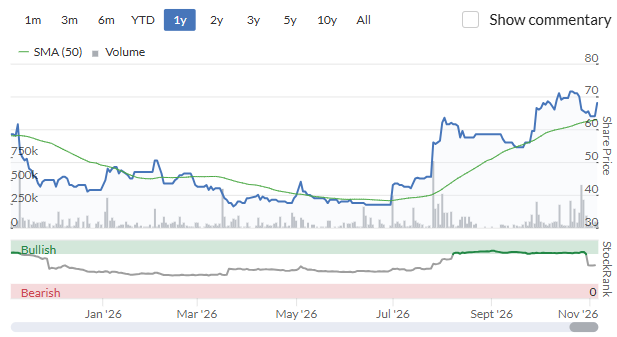
The share price had been strong into last month's results:
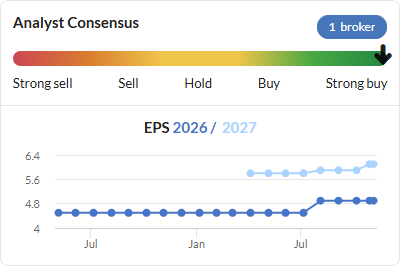
This came on the back of some small broker upgrades and the strengthening cybersecurity background:
I've noticed a trend over the past couple of months that small caps sell off on results day. "Buy on the rumour, sell on the news " has always been a market phenomenon, but the effect seems particularly noticeable recently. So while the results showed significant profit growth and were in line with consensus, perhaps they were always going to be sold into, as investors start to worry about the future rather than celebrate the past.
Some investors may also have expected a further upgrade, given the market backdrop. However, it is very early in the new financial year for this to happen, so it was always very unlikely in my opinion.
When I read the results, I was disappointed that there was no dividend or buyback announced. After all, they recently had a GM to reclassify reserves to eliminate historical losses and give them sufficient distributable reserves to make shareholder returns. So this seemed a misstep that may not have landed well with investors. However, their results presentation made it clear that they hadn't yet received High Court approval for this, so this is a function of timing, not intent.
Chequered past:
The company was formed as a roll-up of cybersecurity software and services businesses. However, it is probably fair to say that the architects of this massively overpaid for these purchases. That is why, despite recent goodwill write-downs and many years passing, the shares trade at half book value (mostly intangible).
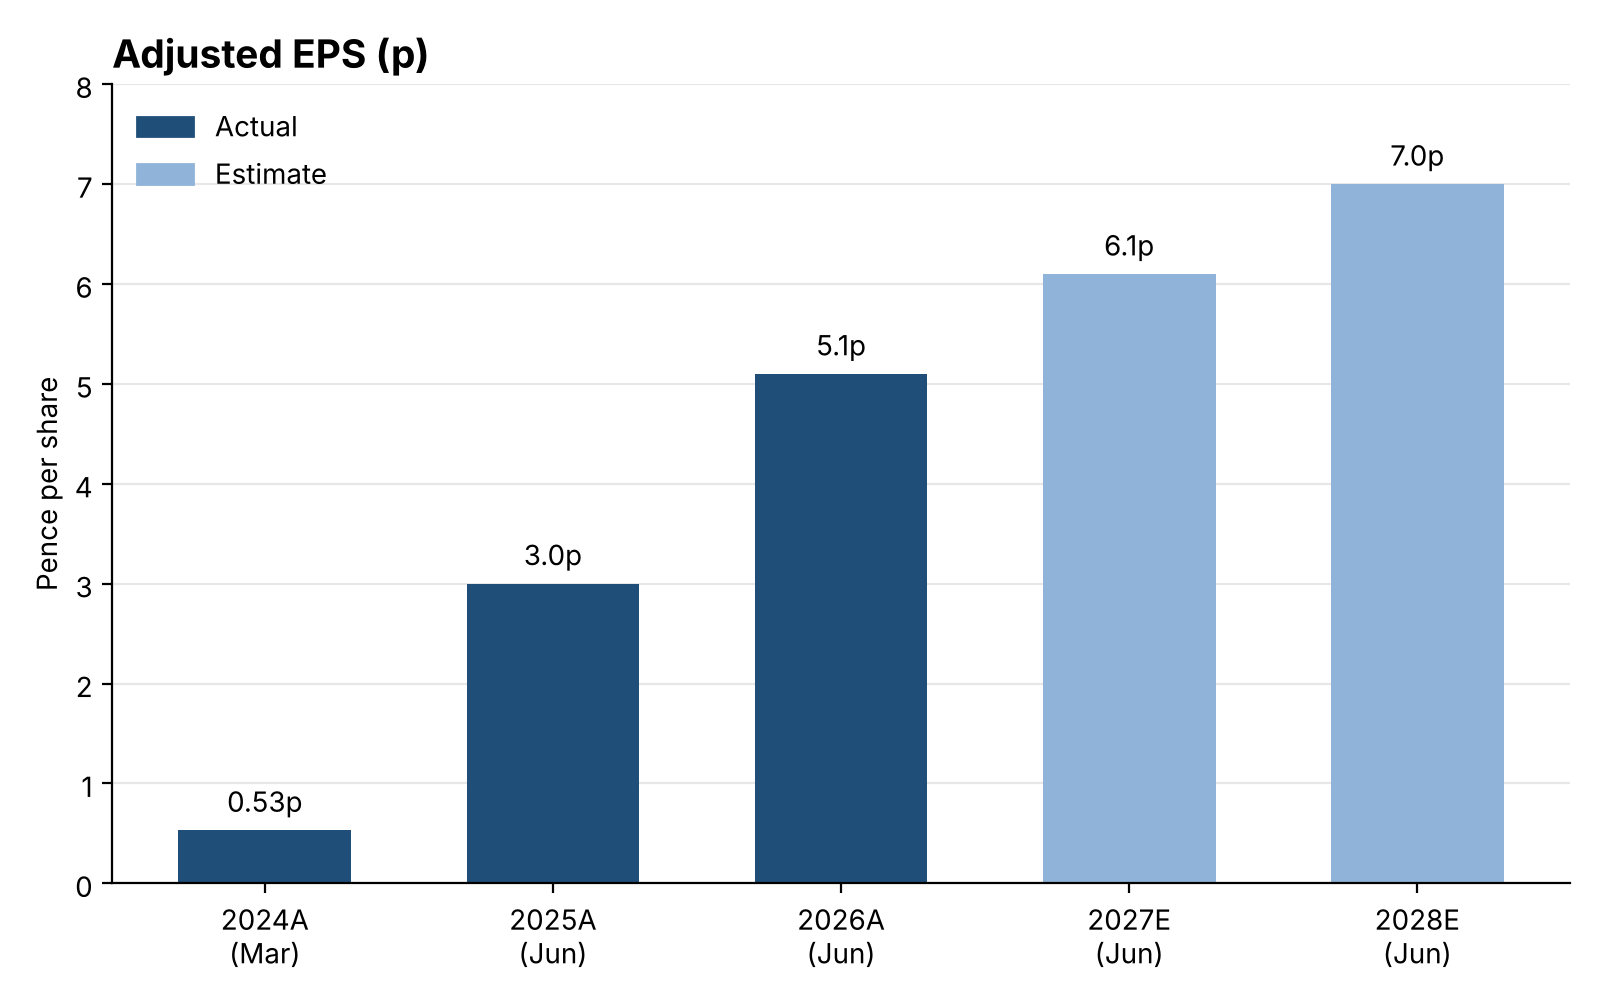
I'm not entirely sure how Refinitiv generates its normalised EPS. Still, it is these write-downs and the amortisation of acquired intangibles that are why the EPS has been negative in the recent past:
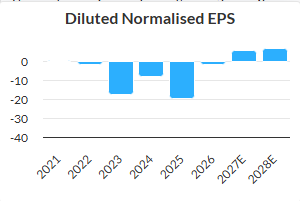
While I have some minor niggles with the adjustments made by the company (some small SBP and ongoing restructuring, for example), I think the broker's numbers are a better reflection of the underlying performance of the business:
The historical statutory loss and the large goodwill seem to be behind the low Quality Rank and moderate Value Rank.
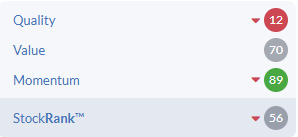
We have to be careful these aren't signs of a poor-quality business that has lucked its way into a temporarily strong market position. However, the best investment returns often come from spotting those points of inflexion where a previously written-off business comes good for several years due to macro tailwinds. Those positive trading conditions often last far longer than investors initially expect and can transform a company's finances along the way.
Acquisitions:
Given the history, the market is probably right to be wary of the company allocating further capital to acquisitions, which appear ot be back on the cards in their recent results narrative.
However, this is a different management team, with CEO Phil Higgins having come from one of the acquired businesses and CFO Jonathan Hall joining in September 2024.
Given the cybersecurity headlines, the risk of overpaying perhaps seems high. However, Shearwater management pointed out in a recent interview that many smaller players will be impacted by the UK Cyber Security and Resilience Bill. Since compliance is largely a fixed cost, smaller suppliers may not want to fund it and may be willing to sell at a reasonable multiple.
Valuation:
As a primarily Value investor, the big attraction for me isn't just the macro tailwinds, but the chance that these may lead to further upgrades. Their broker Cavendish calculates that they trade at around 7x EV/EBIT for the current year, falling to 6x in FY28. This would put the company on a single-digit P/E and with a double-digit FCF yield.
If forecasts are correct and the company is on a medium-term trajectory to grow EPS at at least mid-teens CAGR, this still looks like a low rating.
At the time of writing, Mark has a long position in Shearwater Group
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
Discussion on Shearwater (3)
Comments here are also visible in the Daily Stock Market Report
Shearwater (LON:SWG)
When I read the results, I was disappointed that there was no dividend or buyback announced
lol the thought of a business losing money for its entire existence and paying a dividend is crazy to me - perhaps its sensible to wait till they actually deliver some profit before voting dividends ! hey ho perhaps there was some available reserves from its alter ego days that might allow this.
buybacks do make sense if its not just more "broken promises" like the last 9 years have been.
Shearwater (LON:SWG) Significant contract award. At the moment this the highest riser of companies on this morning's list.
looking good ! to cheap