Shine Justice only win if their clients win

Shine Justice (ASX:SHJ) is a legal services firm that is focused on seeking compensation for those who have been wronged. Erin Brockovich, the legal researcher who was made famous when played by Julia Roberts in the film bearing her name, is an ambassador for the firm.
They have traditionally focused on damages based plaintiff litigation such as for motor vehicle or workplace accidents. Five years ago, 70% of revenue came from personal injury claims, whereas now it has fallen to 46%. In its place they have diversified into other areas, including family law, medical negligence and class actions.
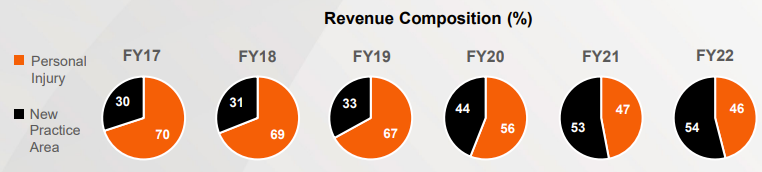
Source: FY22 Results presentation, 26/8/2022
During 2022 they were successful with a class action against Johnson & Johnson which took almost 10 years, relating to faulty prolapse mesh and tape implants affecting up to 12,000 Australian women. They were also successful in a number of other class actions which have become a significant source of revenue growth.
Shine’s revenue has been growing steadily at about 8% per annum since they listed in 2013. Revenue growth accelerated last year to 15% resulting in total revenue of $215 million.
In most cases, Shine only receives a fee if they win the case. That means Shine carries the risk of an unfavourable outcome. They manage this through their experience as to what cases are likely to succeed and therefore they should take on. In addition, some large class actions are fully or partially funded by third parties. In these cases, the funded portion of fees is not contingent on a successful outcome.
It is important to understand how revenue and consequently profits, are recognised in Shine’s books. Revenue is recognised as work is performed on a case. This means that revenue can be recognised in the accounts before the case has been resolved and well before the cash has been received. The revenue amount is determined by making assumptions about the probable success rates. So the accuracy of the revenue figure is highly dependent on the assumptions regarding success rates.
When analysing the balance sheet there is a large asset called work in progress. In 2022 this equated to $332 million. This represents revenue that has been recognised from cases that are still in progress. The revenue has not yet been invoiced. About 55% of this revenue is expected to be realised as cash in the next 12 months with the remainder not expected for more than a year.
In 2016 Shine had to recognise a large impairment against their profits when it became apparent that their success assumptions had been too optimistic and they were not going to realise the cash revenue to match that which had been previously booked in their profit and loss statements.
Since 2016 management have applied more conservative revenue assumptions, which is evidenced by the fact that total cash flow from operations over the six year period is actually a bit higher than recorded profits. In the period prior to 2016 recorded profits were well above operating cash flow. Monitoring cash flow and not just accounting profit is important when analysing any business, but especially so for Shine as there are large timing differences between when revenue is booked and the cash actually received, sometimes extending to many years.

Source: FY22 Results presentation, 26/8/2022
Having noted the good cash flow, we can be more confident when analysing profit. Profits have fluctuated more than revenue, but earnings per share have doubled since 2016. Return on equity is a solid 12%.
On the liabilities side of the balance sheet, the key components are financial debt of $45 million, disbursement creditors of $99 million and a deferred tax liability of $114 million. Disbursements refer to payments for things such as expert’s reports. These are paid for by Shine but recouped from the proceeds of case wins. A portion of disbursement creditors is funded by third parties. If funds are not received through winning the case, then Shine is responsible for ensuring that funding is paid.
Growth for Shine can come from a number of sources. One is to increase the number of fee earners in the business. Fee earners are lawyers who are able to take on cases, as opposed to support staff. This can occur through hiring or through the acquisition of existing law practices. Over the last two years, the number of fee earners has increased from 450 to 600.
Another growth source is to increase the amount of cases being pursued and also to pursue high value cases, such as some of the large class actions. To this end, Shine have marketing and media teams. Class actions have become a lot more common in Australia in recent years resulting in big increases in business insurance premiums. The previous federal government attempted to curtail the profitability of class action lawsuits for law firms and funders however the legislation was not passed.

Source: FY22 Results presentation, 26/8/2022
One measure of the revenue pipeline is the total cabinet of files. This is an estimate of the total fees that could be earned from cases currently being worked on. At June this stood at $630 million of which only 53% had been completed.

Source: FY22 Results presentation, 26/8/2022
Market analysts are forecasting revenue growth to continue over the next two years at about 7% per annum with earnings per share growth to be slightly higher. Based on these projections, the shares are trading on a very modest forecast PE ratio of 4.9. The share price tends to trade on a low PE given the concerns around earnings transparency described above, but the current valuation is well below the long-term average. This translates to a high value rank.
Another reason for the markets’ application of a discount on the stock, and the industry as a whole, is on account of a previous high profile disaster, namely Slater & Gordon (ASX:SGH). SGH was a darling of the market in the early to mid teens (2013-15) rising over 300% in two years at its peak it got to market cap of $1.8B. It had begun to aggressively engage in a rollup strategy both here and in the UK acquiring many law firms in order to add immediate case numbers to the bottom line.
But as with many rollup business strategies, they inevitably end up at a point where the business stretches a little too far. In the case of SGH that came in the name of Quindell, a UK compensation law firm that it acquired for £673m. This was done at a time of changing UK legislation and question marks around Quindell’s viability. Ultimately this acquisition was the beginning of SGH’s downfall. The resulting failure of SGH and subsequent recapitalisation in 2017 raised serious questions around due diligence within the sector and the accounting principles applied to companies within it (as discussed above). These concerns linger today.
Back to SHJ, the forecast dividend yield is 6.9%. In recent years, most tax has been deferred, rather than paid, resulting in no franking credits.The fact that dividends are currently unfranked also contributes to the valuation discount.
Shine had a large accumulated tax loss when they floated in 2013. Also, tax is paid when cash is realised, not when the revenue is booked. As revenue has exceeded cash receipts in recent years, WIP along with the deferred tax liability have been increasing. This is expected to start to reverse in the near future as case resolutions result in more cash receipts, for example the Johnson & Johnson mesh case. Also the tax losses are almost fully utilised. Once this point is reached they will start paying tax and the deferred tax liability will start reducing. They will also be able to pay franked dividends.
The manner of Shine’s business, and therefore the way accounting standards are applied, can make it a complex business to analyse. However when you dig beneath the surface, a business that ranks highly in terms of quality and value shines through.
Important Information: Stockopedia Ltd ABN 39 757 874 670 UK business registration number 0637267 (“Stockopedia”) is an Authorised Representative of Daylight Financial Group Pty Ltd ABN 77 633 984 773 (“DFGPL”) which is the holder of an Australian Financial Services Licence (AFS Licence No. 521404).
Information in this commentary is current as at date prepared unless otherwise stated. However, please bear in mind that investments can go up or down in value, and that past performance is not a reliable indicator of future performance. For more Important Information please refer to the Disclaimer section of this website.
This communication may contain general financial product advice. It has been prepared without taking into account your personal circumstances, and you should therefore consider its appropriateness in light of your objectives, financial circumstances and needs before acting on it.
If our advice relates to the acquisition or possible acquisition of a particular financial product, you should obtain a copy of and consider the Product Disclosure Statement (PDS) before making any decision.
The author holds interests in the following stocks mentioned in this article: SHJ. This position can and will change at any time without notice.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
No comments yet
No one has commented here yet! Why not be the first one?