SHJ: Shrinking to greatness

The first article I wrote in 2023 was about Shine Justice (ASX:SHJ). Almost two years later, it seems like a good time to revisit it. Below are the stock rankings then and now.
Stock Ranking 4 Jan 2023
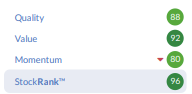
Stock Rankings 12 Sep 2024

Just looking at those two points in time it looks like a good business has just got slightly better. But that masks what has been a fairly rocky road in between.
First some background. Shine Justice is a legal services firm that is focused on seeking compensation for those who have been wronged. Erin Brockovich, the legal researcher who was made famous when played by Julia Roberts in the film bearing her name, is an ambassador for the firm. They focus on damages based plaintiff litigation such as for motor vehicle or workplace accidents as well as pursuing class actions.
Their most recent high profile case to settle was a case brought on behalf of Aboriginal and Torres Strait Islander Australians who worked in the Northern Territory between 1933 to 1971 for little or no wages. The Commonwealth Government agreed to settle the class action for up to $202 million.
Revenue grew by 8% in FY23, but profits fell by 89%. In FY24, revenue fell 12% and profits increased 82%. (depending on which measure of profit is used and the adjustments). But more so than with many companies, it is cash flow that needs to be analysed to understand how Shine is doing. Cash flow from operations increased from $5 million to $44.5 million.
Such conflicting results can make it difficult to understand what is really happening. The nature of the business means that there can be considerable fluctuations in the short term, but over the long term they should start to even out and the true underlying performance of the business should shine through. It is also essential to understand the nature of the business’s revenues and expenses and how they affect cash flow.
Revenue is recognised as work is performed on a case. This means that revenue can be recognised in the accounts before the case has been resolved and well before the cash has been received. The delay between revenue recorded and cash received is often 12 months to two years, and in the case of class actions, it can be a lot longer. Therefore the revenue amount is determined by making assumptions about the probable success rates. So the accuracy of the revenue figure is highly dependent on the assumptions regarding success rates.
If we compare cumulative revenue over the last eight years with cash receipts, they are almost equal. This gives us confidence that the revenue assumptions being used are realistic. The period of eight years has been chosen because in 2016 they had to make a large write down when it became apparent that the prior revenue assumptions had been overly optimistic and a considerable portion of the money was never going to be realised. Since then the assumptions behind revenue seem to have been a lot more accurate.
Over that same eight year period, operating cash flow has been a cumulative $198 million. Of that, $73 million has been reinvested back into the business, often in the form of small acquisitions. That leaves free cash flow of $125 million. $53 million was paid out to shareholders as dividends and $71 million was used to repay debt.
The money that has been invested back into the business has been generating a strong return. Looking at the return on invested capital it had been steadily increasing up until 2024.

As shown in the chart above, profitability fell markedly in 2024. This is based on Operating Profit (or EBIT). NPAT actually rose.

One of the main drivers of these large adjustments and volatility over the last two years is a class action case known as the Ethicon and Boston Scientific mesh class action. Shine fought this class action for over 10 years on behalf of up to 12,000 women who were left with complications after implants of faulty prolapse mesh and tape. It was one of Australia’s largest product liability class actions and a settlement of $300 million was reached in March 2023.
The case was conducted on a ‘no win no fee’ basis. This means Shine carries the risk, not only of not getting paid, but also having to cover disbursements to third parties such as medical experts and barristers. Initially they covered these costs themselves, but as the case dragged on they obtained external disbursement funding to assist with the costs, i.e. they borrowed the money.
In August 2023 the court dismissed the application to recover the full amount of the interest on the disbursement funding facility from the settlement fund. As a result the Unbilled Disbursement Asset was written down by $32.4 million as at 30 June 2023. This is money that has been spent servicing the loan and they are unable to recover.
Over approximately 10 years, $52 million had been recognised as revenue from this case. The court ordered that $36.1 million in respect of work in progress and disbursements may be deducted from the settlement. $22.6m was received in FY23 and $13.5m in FY24, impacting cash flows. Approximately $5 - $6 million of revenue was reversed in FY24.
As at Aug 2024 they are preparing an application to seek recovery of an amount of interest on the disbursement funding facilities used.
This case study highlights the complexities in analysing the business along with the inherent risks. The revenue and profits profile is very different to the cash flows.
This high profile case partially hid the other difficulties that were also encountered in FY23. Even excluding the Mesh case, profits fell. Cash flow was negative and they decided not to declare a final dividend.
Scarred by the challenges of FY23 they decide to undergo a reset in FY24 and shrink their way to greatness. The diversification strategy of prior years was ditched and replaced with a ‘back-to-basics’ strategy, focusing on core strengths (and other related buzz words). Head count fell by 9% and the number of branches declined from 54 to 51. The Family law practice of Best Wilson Buckley was discontinued.
This revised strategy is not necessarily a bad thing, but it is a reminder to be a little bit wary about businesses that are growing by acquiring other businesses in adjacent areas. The arguments supporting diversification and core focus, sometimes change with the seasons.
Turning to the shares, they are quite thinly traded as ownership is concentrated. The two co-founders own 50% of the business between them, one of whom is the CEO, Simon Morrison.

This small free float, along with the volatility of profits and cash flows results in the share price being perennially valued at a discount. With dividends having been restored this year the yield is high and the forecast PE ratio is very low at only 5.9. Price to free cash flow is also good at 3.1. Bear in mind that cash flow varies a lot as has been discussed and FY24 was a very strong year for cash flow. If we take the average over the last eight years, the price to free cash flow ratio is 8.9. Price to book value is also low at 0.53.
Since the announcement of the full year results at the end of August, the share price has rallied 15%. The market seemed generally happy with the narrowed focus, strong cash flow and the sentiment that the tough challenges were behind them. The following day a buy-back of up to 10% of issued capital was announced. This suggests that management has a high degree of confidence in the future cash flows and also that they believe the business is currently undervalued. A week later the Northern Territory Stolen Wages Class Action settlement was announced adding more icing to the cake.
This string of positivity has added 30 points to the Momentum Score and helped propel Shine Justice to an overall StockRank of 99.
Important Information: Stockopedia Ltd ABN 39 757 874 670 UK business registration number 0637267 (“Stockopedia”) is an Authorised Representative of Daylight Financial Group Pty Ltd ABN 77 633 984 773 (“DFGPL”) which is the holder of an Australian Financial Services Licence (AFS Licence No. 521404).
Information in this commentary is current as at date prepared unless otherwise stated. However, please bear in mind that investments can go up or down in value, and that past performance is not a reliable indicator of future performance. For more Important Information please refer to the Disclaimer section of this website.
This communication may contain general financial product advice. It has been prepared without taking into account your personal circumstances, and you should therefore consider its appropriateness in light of your objectives, financial circumstances and needs before acting on it.
If our advice relates to the acquisition or possible acquisition of a particular financial product, you should obtain a copy of and consider the Product Disclosure Statement (PDS) before making any decision.
The author holds interests in the following stocks mentioned in this article: SHJ. This position can and will change at any time without notice.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
No comments yet
No one has commented here yet! Why not be the first one?