Shoe Zone suffering higher container prices as it faces an uncertain 2027

Analyst’s view:
In August, I upgraded our stance on SHOE from fully negative to only moderately negative. In hindsight, that was a mistake. Even if broker forecasts suggest that the company can make a profit in FY27, I don't consider this outcome very likely, given what the company has said today about higher container prices. With ongoing losses for the foreseeable future being the most likely outcome, in my view, I think it's fair for us to go back to a fully negative stance on this share.
Down 21% at 58.2p (£26m) - Full Year Trading Update
This was a downbeat update from Shoe Zone, covering FY 2026 (ending early October) and with an outlook statement for FY 2027.
Let's briefly review FY 2026:
Revenue down 4.5% (£142m)
Product margin improves from 61% to 63.1%.
Adjusted loss before tax £1m (FY 2026: adjusted PBT £2.4m), in line with expectations.
The fall in revenue is attributed to a reduction in the number of stores (251 at the end of the financial year, compared to 269 a year ago), but also "a continued decline in consumer confidence and the general negativity in the UK economy."
As for the company falling into unprofitability, this is blamed on National insurance and the National Living Wage.
Also, the good news on product margin will be short-lived:
...at the end of the year, container prices increased due to issues at Chinese ports and the continuing geo-political issues resulting in increased fuel prices, which is expected to negatively impact product margin performance.
With the company already loss-making in FY 2026, it's difficult to see how they will be profitable in FY 2027, if product margin is about to come under pressure.
Net cash finished the year at £15m.
Dividends: none. No dividend here since 2024, which makes sense in the circumstances.
Capex is being limited to "essential expenditure only", in a sign of the company moving into cash preservation mode.
Outlook (excerpt):
Management continue to be cautious about the near-term outlook, with trading conditions expected to remain subdued. The start to the Autumn/Winter season has been slower than expected, impacting the last few weeks of the financial year FY 2026, and continuing into the new year FY 2027... We have recently seen an increase in container prices and a weakening of Sterling to Dollar exchange rate, as well as an increase in fuel prices, all of which could negatively impact trading.
This is very grim - it says to me that we should fear an outturn in FY27 that is significantly worse than FY26, with the company now needing to focus on preserving cash.
The Chairman strikes a similar tone, saying that there is "generally negative economic and consumer sentiment in the UK", with consumers showing caution in their expenditure.
Estimates
Thanks to Zeus for publishing on Shoe Zone today. The actual FY26 result is a little worse than they expected (pre-tax loss of £1m vs. £0.5m in their forecasts).
Looking ahead, they expect "broadly flat" like-for-like revenue from the company in FY27.
Surprisingly, to me at least, they see an adj. PBT of £1m in FY27, upgraded from their previous forecast of £0.5m, due to fewer asset write-offs (these write-offs cost Shoe Zone £0.5m in H1 2026). Zeus acknowledges that there are downside risks to this forecast.
Graham's view
At this stage, I'd see a very wide range of possible outcomes for FY27 but with most of them involving another loss, and probably a larger loss than FY26.
The company is doing the right thing by being forthright about the dour outlook, but there is no reason for investors to think that they are being overly pessimistic. This business has been under growing pressure for the last few years:
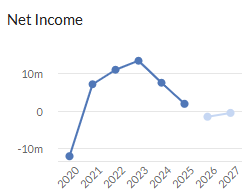
When I discuss Shoe Zone, I always try to highlight that there are zero barriers to entry in this sector, and that it has no place to hide from the economic winds.
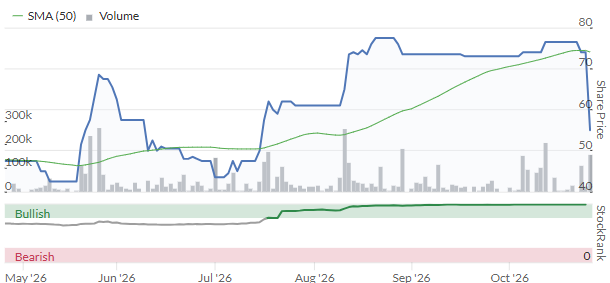
All that it can do - which it has been doing, thankfully - is to conserve cash. Its main misstep in this regard has been to buy back its own shares: it announced a buyback for up to £3.5m back in August.
In the end, it spent less than £1m buying back its own shares, and has now ended the programme. It goes without saying that it overpaid for these shares:
In August, I upgraded our stance on Shoe Zone from fully negative to only moderately negative.
In hindsight, that was a mistake. Even if broker forecasts suggest that the company can make a profit in FY27, I don't consider this outcome very likely, given what the company has said today about higher container prices.
With ongoing losses for the foreseeable future being the most likely outcome, in my view, I think it's fair for us to go back to a fully negative stance on this share.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
Discussion on Shoe Zone (3)
Comments here are also visible in the Daily Stock Market Report
I think if you look at the 10 year chart for Shoe Zone (LON:SHOE) it tells you all you want to know about the business. I recall trading in and out once and looking at it a few times across the years but never having the inclination to bother. Essentially this is a business trading at the lower end of the consumer market ( i.e quality is questionable) so heavily influenced by the ability of the consumer to spend. Not that I have done the figures nor looked that closely at the chart but my gut feel is it tends to bounce off around the mid 50p's and rally on what seems to be negligible good news ( i am unconvinced that the news today could be seen as ; unexpected' ) so it is merely a stock to trade rather than see as an 'investment'. I put this type of consumer business in the same bracket as Card Factory, both likely to have been hit by markedly higher costs on most fronts but at least the latter has moved further away from dependence on the high street through Funky Pigeon
Shoe Zone (LON:SHOE) Market has put the boot in following comments about a "slower than expected start" to the Autumn season. Recovery deferred....for a bit. Harrumph. I hold.
Re Shoe Zone
From the trading update...
"However, overall discretionary spending remains subdued as consumers exercise greater caution in their expenditure."
I think that Shoe Zone have used this discretionary spending argument before? However, the notes to the trading update state...
"During an average year Shoe Zone sells 12.4 million pairs of shoes per annum at an average retail price of c.£13.20."
I don't see how a £13.20 pair of shoes can be described as a discretionary spend. Its surely not that type of market.
A serious question for those who follow the workings of StockRanks. How does ShoeZone manage a 98 StockRank rating and a "Superstock" classification. I cant see why it is rated so highly.
No position
I think if you look at the 10 year chart for Shoe Zone (LON:SHOE) it tells you all you want to know about the business. I recall trading in and out once and looking at it a few times across the years but never having the inclination to bother. Essentially this is a business trading at the lower end of the consumer market ( i.e quality is questionable) so heavily influenced by the ability of the consumer to spend. Not that I have done the figures nor looked that closely at the chart but my gut feel is it tends to bounce off around the mid 50p's and rally on what seems to be negligible good news ( i am unconvinced that the news today could be seen as ; unexpected' ) so it is merely a stock to trade rather than see as an 'investment'. I put this type of consumer business in the same bracket as Card Factory, both likely to have been hit by markedly higher costs on most fronts but at least the latter has moved further away from dependence on the high street through Funky Pigeon