Should you be a buyer of BT shares ?

The last time I looked at BT shares in any detail was 2012, and at the time[1] I wasn’t exactly gushing with enthusiasm. I thought the company’s results were lacklustre, the valuation so-so and the yield unimpressive. I didn’t invest.
So was I right to avoid BT and, more importantly, are things looking any better today?
BT in 2012 was a slow growth company with a mediocre valuation
Here are some of the numbers from my last review:
- In September 2012, BT shares were trading at 221p
- The company hadn’t grown at all in the previous decade
- The yield was 3.8%, about the same as the FTSE 100 at the time
- The PE10 ratio (my preferred measure of value) was 12.7, slightly lower than the FTSE 100’s
The company had consistently produced profits and dividend payments, but the dividend had been cut in the financial crisis and there was no obvious growth trend.
With such uninspiring financial results it was fairly valued at best, given a valuation and yield approximately equal to the wider market.
To put icing on the cake the company had fairly substantial financial obligations in the form of both borrowings and pension liabilities.
It’s no surprise then that I declined to invest, which means I missed out on the 80% plus total returns that BT shareholders have enjoyed since then. So what happened to produce such good gains in less than 2 years?
From 2012 to 2014 the dividend grew and so did positive sentiment
Some of the gains came from the dividend. With the yield near 4% in 2012, investors have received around 8% in dividends since then, but the remaining gains of around 75% have come from the capital side of things.
Again, this has been driven to some extent by the dividend. In 2012 the dividend stood at 8.3p while today it’s some 31% higher at 10.9p. The share price would have had to go up by 31% just to keep the dividend yield at that same 3.8%.
But that’s only 31%; where did the remaining capital gains come from (another 44% to be precise)?
The answer is improving market sentiment, or if you want to put it another way, expanding valuations.
Investors are happier about BT today than they were in 2012 and so they’re willing to accept a yield of just 2.7%. To decrease the yield from approximately 3.8% to 2.7% you need to increase the share price by that missing 44%.
Overall then BT shareholders have had about 8% in dividends, 31% from dividend growth and 44% from expanding valuation multiples.
But of course there are more things to think about than just the dividend. Those dividends are paid out of profits and profits require revenues, so has the 30% dividend growth been accompanied by top and bottom line growth as well? Let’s have a look:
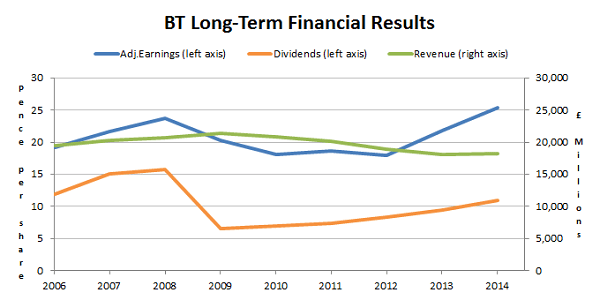
Revenue growth has been around -1.5% a year and profit growth has averaged a measly 0.1% a year, both measured over the last decade.
Even if we focus on the most recent couple of years which cover that 30% dividend growth I mentioned before, profits have gone up but revenues have not; and that’s a problem.
Revenues have been flat, in nominal terms, for a decade at least. Clearly there can be no long-term growth if a company’s top line isn’t growing.
Of course there are programs and projects underway within the company to grow and increase shareholder value, but isn’t that always the case? And if the company hasn’t managed to grow in the last 10 years how can an investor reasonably have faith that it will be able to grow in the next 10 years?
As far as I can see BT has continued its post-recession recovery, but nothing more. I don’t see any evidence yet of long-term sustainable growth, so I don’t think I was wrong in 2012 to think that BT wasn’t attractively priced at 221p.
And that begs a question: If I thought they were expensive at 221p, what do I think of them now they’re at 400p?
BT shares look expensive, propped up by optimism
In 2012 the market valued BT in line with most other large companies, despite its somewhat disappointing financial results. Things are different now and the market is definitely optimistic.
The dividend yield, at 2.7%, is well below the yield on the FTSE 100 or All-Share. I can get 5.3% from Vodafone, or 3.9% from standard chartered. The market must be expecting BT to significantly outgrow those and many other higher yielding companies, even though there is no evidence for growth in the company’s past.
In terms of earnings, BT’s PE10 ratio is 19.5, well above the FTSE 100’s 14.5. Using my stock screen[2] I can see that 40 of the dividend paying companies I track have PE10 ratios of between 18 and 22, and on average they have grown at 6% a year and have an average yield of 3.3%. So on average they’re growing faster and yielding more than BT, which is perhaps a less than subtle hint.
And those financial obligations are still there. Total borrowings currently stand at £9.8 billion compared to average earnings after tax of £1.5 billion over the last decade, and total pension scheme liabilities stand north of £20 billion. Yes, that’s 20 billion pounds.
There is also a deficit in the scheme of around £7 billion which needs to be filled from cash which will be a drain on resources, as it has already been for a long time.
BT – not for me
When I’m investing I look for a combination of five things[3]:
With BT I think the company offers mediocre growth, quality and safety at best. To be an attractive proposition it would need to be selling at a discount to the market rate, which it currently isn’t, and so it doesn’t offer good value or a decent yield either.
Unless the share price collapses from 400p back down towards 300p (and preferably 250p), I don’t think I’ll be investing in BT shares any time soon.
Disclosure: As I mentioned Vodafone I should also mention that I own Vodafone shares and Vodafone is a holding in the UKVI Defensive Value Model Portfolio.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
3 comments
Bt to offer mobiles in near future .The quad play of internet/ tv /phone /mobile which VOD are desperate to join will be on offer by BT to practically all of UK homes
Housing crisis............House building must increase as a priority all connected in the vast majority of cases by BT
Pension deficit ..........a worry.Ultimately it will reduce as people shuffle off their mortal coil
John, I think you were spot on with your analysis of the financials however I bought into BT in Jun 2012 and the below was my reasoning (from 2012):
*************************************
While this share is on my mind I though I would quickly jot down why I
would buy billions of BT (bear in mind I bought and sold for about 15%
a few years back selling around 115 they now 200)
In the last few years BT have done the following:
- Broadband - upgraded speeds to rival the best in class Virgin,
speeds are now better than Virgin.
- Wifi - the other big drawcard to tech savvy people is the almost
monopoly they have in wi-fi roaming. This means there are millions of
points around the uk you can connect to wi fi for free if you with bt
- its a massive advantage over every other provider
- TV - BskyB were going to be chopped apart for being a monopoly that
was the case until BTvision came out overtaking sales compared to sky.
Its like freeview but a bit better.
Back in the old days a home phone was a guarantee everyone had one,
now its broadband and they are best in class. Previously they were
surviving only because "muppets" had a BT line so they got a package.
Honestly they were not even in the top 5. Its a massive swing.
Downside:
They still have a massive pension pot to sort out which depressed the
price to sub 100p I think this is now being well controlled and
whoever has steered them in the last 3 years is a man to follow.
A long time ago they sold O2 - whoever thought that was a good idea is
hopefully no where near a share I own in the future.
A strong buy - and a share likely to double in the next 5 years on top
of a decent dividend payout
**************************************
At current levels the pension pot worries me and I am not sure how much higher it will go from here - maybe 20%? I think the downside outweighs the upside - so I wont be adding to my holding.
Thanks for the analysis, it was on my list to research, you saved me the job :)