SIF Folio: Another win for Miton but what’s gone wrong at Bilby?

It’s nearly the end of March, so this week I want to carry out my regular review of stocks that have been in the SIF folio for nine months or more.
I don’t normally comment on newsflow from portfolio companies during their time in the portfolio, but I do want to make an exception for building services group Bilby (LON:BILB), which has been a complete car crash of an investment so far.
Stocks for review
In June last year, I only added one stock to the SIF folio, small-cap asset manager Miton (LON:MGR). This well-regarded firm is now the portfolio’s oldest holding, and the only one that satisfies my minimum holding period of nine months.
As a result, I need to check whether these shares still pass all of my screening tests. If not, then the stock may have to be sold this week.
Miton (LON:MGR)
It’s worth noting that this is Miton’s second stint in the SIF fund. The first ended profitably with a 46% total return. The stock is showing a more modest profit this time round, but even that’s a relief after some big losses recently.
Miton’s 2018 results appear to have given investors the injection of confidence needed to buy a few more shares. The share price rose by more than 10% on the day and has maintained that gain so far.
Big inflows: It’s not hard to see why Miton’s results were well received. While big cap asset managers like Standard Life Aberdeen are suffering hefty net outflows, investors are still queuing up to deposit cash with Miton. Assets under management rose by 14% to £4,376m last year, despite a £466m negative return from the group’s investments.
Short-term dips like this are inevitable for an asset manager. You cannot deliver absolute positive returns in all circumstances. Although percentage of Miton funds in the first or second quartile for performance fell from 87% to 81% last year, I remain confident that the group’s long-term results are likely to be above average.
Miton’s business performance has certainly been strong. The group’s operating margin rose from 22.2% to 24.3% last year. Return on equity rose from 8.3% to 11.6%.
Risks? The credibility of investment boss and small-cap specialist Gervais Williams plays a big part in the appeal of this business. Although this means that there’s a degree of key person risk, Mr Williams has a shareholding of nearly 9%, so his interests should be well-aligned with those of shareholders.
A more near-term risk may be that stock market volatility will affect the profitability of the business. This is a characteristic of all fund managers. Ultimately, most need neutral or positive market conditions in order to deliver strong results.
As a long-term investment, I would continue to hold Miton. Stockopedia’s algorithms share this view, with a StockRank of 93 and Super Stock status.
However, the SIF’s focus is on shorter periods means that my screening rules include a number of momentum and growth measures. These need to remain positive to justify a continued hold.
Does Miton still pass my tests? Sadly not:

At the heart of the problem is that earnings per share are expected to fall by about 12% to 4.1p per share this year:
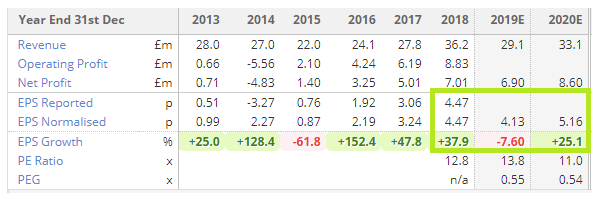
(I’ve used the company’s adjusted eps figure of 4.7p per share for 2018)
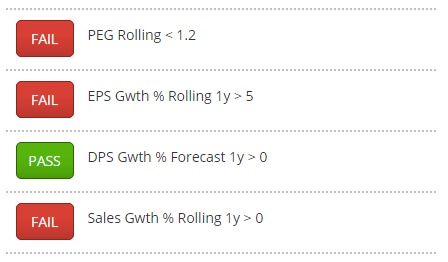
Although a return to growth is pencilled in for 2020, this year’s dip means that Miton now fails three of my screening tests:
My decision: I have no choice but to sell Miton from the SIF fund this week. Happily, the boost provided by the firm’s recent results has left the SIF’s holding in the black. A positive return of 8% or so in nine months is no disaster, given the sell off we saw at the end of last year.
Verdict: Sell
Total return: +8.1pc
Bilby - an accident waiting to happen?
It all looked so promising! When I added building services contractor Bilby to the SIF folio in August 2018, the company had delivered four years of strong revenue growth and appeared to be converting this into much-improved profits.
Fast-forward to today, and the SIF holding is showing a 78% loss. What’s gone wrong?

This firm specialises in gas, electrical and building services for social housing landlords in London and the south east. Although it had grown by acquisition, this process appeared to be working well.
Shortly after I bought the stock, things started to unravel.
Sept-18 - Founder share sale: The first clue that my timing was out was when founders Phil and Leigh Copolo sold their 31.3% holding in the firm and left the business. I should have been more suspicious, but in reality there wasn’t much I could have done. I have a policy of not selling stocks early and the shares were placed with institutions who seemed happy to buy, albeit at a discount.
Interestingly, it looks like one of the institutions who bought Mr Copolo’s shares was Miton, whose declared holding rose from 15.1% to 19.8% in the days after Mr Copolo’s share sale.
Dec-18 - Profit warning #1: Worse was to come. The shares crashed again in December when Bilby’s interim results showed a 16% fall in underlying pre-tax profit and issued a profit warning. According to management, a decision to terminate a contract with the Ministry of Defence is to blame, along with various other contract delays.
Mar-19 - Profit warning #2: A trading update at the start of March contained another profit warning. The same problems are blamed again, but it now appears that Bilby firm P&R has not made a clean break with the MoD and may be facing “dispute and resolution proceedings”. Other contract delays cited in December continue.
Underlying EBITDA for the year to 30 June is expected to be £2m-£3m, compared to £6.3m last year.
My view: Bilby appears to be suffering from the classic service sector problem of bad contracts and slim margins. It’s something we’ve seen many times in recent years, both with big caps and small caps.
The stock is now highly illiquid, with a market cap of just £11m. I suspect that’s one reason why the shares continue to fall on a daily basis - there may be a big seller who is struggling to ditch their shares.
Interestingly, Bilby’s house broker doesn’t seem to have cut its forecasts for the current year following March’s profit warning:
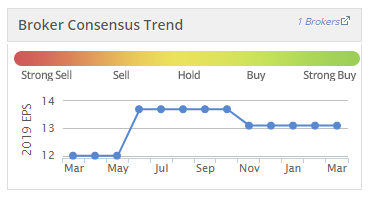
I’m not sure how credible these forecasts now are. Based on this guidance, the stock trades on just 2.2 times 2019 forecast earnings. Clearly the market doesn’t expect Bilby to deliver, and I have to say that I agree.
In this case, my policy of sitting tight has cost me dearly. I don’t hold out much hope of recovering my losses before my rules force me to sell, but I’m going to stick to the plan for now.
However, when I review the SIF fund’s performance during its third year next month, I may make some changes to my rules to try and avoid investing in such fragile businesses in the future.
As always, your comments on Bilby or Miton (or anything else) would be much appreciated.
Disclosure: At the time of writing, Roland owned shares in Miton and Bilby.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

9 comments
took a punt and up 18% since i bought yesterday - i reckon this one will recover in a year or two.
Sorry to hear of your loss, I have a number of -50% ers in my portfolio and I struggle sometimes as to what to do with them, wait and hope or cut and lose. My travails are all caused by ignoring fundentals and buying in at too high a price and I suspect others have the same issue. Spookily enough, Bilby's fundamentals now look appropriate to be taking a punt and I shall.
Hi Roland; I enjoy your reports & find them helpful. I sold my investments in fund managers when the mkt started to fall the first week of Oct on basis that investors would start to pull out. Since Feb i have been considering getting back in and MGR was one possibility but still holding off; many are still diving others in consolidation with just a few making slow progress; i consider the market will continue to be volatile for a while.
I did look at BILB at end of 2017 but concluded it was too small for me and it was a labour intensive Contract business , so put a Red note on my chart & left it. The ride up to July would have been nice but looking at it again consider i would have got out at 100p in Sept.Easy to say now but it would have been following my usual exit strategy.
I do have one portfolio where i have tried holding for the long term,,,and it hurts. For a couple of years i have listened to the Long Term arguments & appreciate the compounding of interest ( which is why that portfolio is mainly Stalwart divi stocks, so i am being paid for holding on but it has convinced me that i shall not apply the principle in future, not that it is wrong , just wrong for me. The worst example is CARD down 48% not covered by the excellent divi.
I tend to agree with your other commentators as to why you do not have an exit plan for extreme conditions; and see that you will be looking at some possibilities.
Wishing you every success with the SIF Folio,
Hi
Not a fan of stop losses but a system/philosophy that watches a share fall from 127p to 28p without doing anything seems fundamentally flawed.
I know what you're trying to do and I applaud it and find your articles very informative and useful - but surely even a quants based buy and hold system should allow for profit warnings/ disasters etc and not keep for a fixed period of time in extreme situations. I have a similar problem with the NAPS scenario.
Bilbly may recover - I've held in the past but got out when circumstances changed - there is a minor possibility Bilby (LON:BILB) is worth zero due to MoD contract reparations and its debt - I would not be holding just because it is not yet due for review even if I had little time to study my portfolio.
Phil
Hi Phil,
There's no doubt in my mind that the prudent thing to do would have been to sell Bilby (LON:BILB) at the first sign of trouble; in this case the founder share sale or else the first profit warning. Your comment about seeing such a loss without taking any action is well made. In a discretionary portfolio, I wouldn't have let things get this far without actively taking a view - i.e. selling or averaging down.
However, my policy with SIF is not to introduce ad hoc changes to the rules and to minimise manual intervention. So I've stuck to the rules - at some cost, in this case.
I should point out in some other scenarios, riding out dips has proved a more profitable strategy. So it's not a black and white situation.
I'm mulling over whether to introduce a rule to simulate the effect of a stop loss, as this facility isn't available in the Stocko Fantasy Funds. But like you, I'm not a fan of selling at an arbitrary level for no other reason than because the price has moved.
What I may do instead is give myself the option of selling immediately after a "threshold event" - such as a profit warning or perhaps a founder sale... If I do make any changes to the rules, it will be in April when the portfolio is due for its annual review.
I don't have any insight into the MoD situation, but I would tend to agree that any further bad news from this level could result in a total loss for shareholders.
Regards, Roland
Thanks Roland.
Have noticed not many stocks to choose from with the proceeds,with falling momentum will you increase cash position until such times allow or relax the rules!!,or maybe increase % holdings in those that qualify with a more concentrated portfolio.
@coniston,
Although I do have a "relaxed" version of my standard screen which adjusts my valuation criteria slightly, my general policy is to allow cash to build if no new stocks present themselves.
However, my screen is showing signs of life, so I'm hoping to be able to make another new purchase next week!
Thanks,
Roland
Hi Roland,
Thanks for your article - thought provoking as usual.
I share your pain on Bilby having bought at a similar time and sitting on a similar loss. What with that and Superdry I now consider founders selling significant holdings/all of their holdings as an absolute red flag now. So it has been a painful lesson learned.
My holding in Bilby is within my SIPP and with the value rank so high now I have mentally written the share off and will just sit tight and see if over the coming years things can be turned around sufficient to recoup some of the losses. I am in no hurry.
That said, it has been a dilemma these last few months as to whether I should have cut my losses much earlier and invested the funds elsewhere - in hindsight, I definitely should have.
I think it will be a long road back with Bilby, with no guarantees!
Richard
Hi Richard,
Thanks for your comment. I agree that Bilby (LON:BILB) looks cheap based on both past and forecast performance. I mentioned my concerns about the current broker forecasts in the article -- I'm not convinced they're reliable anymore.
As for ValueRank, the stock does look very cheap based on its historic performance. My concern is that this business may no longer be able to repeat such a performance. I don't really know how likely this is or exactly what has changed in the P&R division, where the problems seem to lie. But I am concerned.
I agree with you re. founder sales. Two founding directors sold up and walked, with no apparent notice. I'm surprised the firm found institutional buyers for the stock, especially good quality names like Miton (LON:MGR)
Perhaps they felt that soaking up the stock was the best way to prevent the share price collapsing...
Regards,
Roland