SIF Folio: D4T4 has good data but lumpy progress is a risk

As I hoped, last week’s results from SIF folio stocks Motorpoint Group and Character Group were showed decent progress at both firms.
Graham and Paul covered both sets of results in last Thursday’s SCVR report, which you can read here. I won’t repeat their excellent commentary, but one thing I would like to add is that Motorpoint continues to qualify for my stock screen based on its latest trading results. So it seems that leaving the portfolio’s holding untouched last week was the right thing to do.
SCVR to the rescue
I don’t often I come across a UK stock I have zero familiarity with. But this week my Stock in Focus screen has highlighted a company that’s completely new to me: D4T4 Solutions (LON:D4T4).
This AIM-listed software business is a specialist in data solutions. Luckily it’s been covered by Graham and Paul in the Small Cap Value Report on a number of recent occasions. Their standout work provides a fantastic pool of commentary to draw on when getting up to speed with new small-cap stocks.
What does D4T4 do?
House broker FinnCap describes this company as a “specialist provider of data collection, management and analysis solutions”.
In short, it seems that clients pay D4T4 to collect data “from all consumer touchpoints”. This data is then stored on the firm’s platform, which ensures it is compliant, complete and accurate. Technology such as artificial intelligence is used to analyse the data and create behavioural profiles, personalised offerings and other insights that might drive growth.
The company’s clients are pretty varied. According to the firm’s website, clients include Axa Insurance, major banks, the NHS, Qantas and Toyota.
Essentially this is a Software as a Service (SaaS) business. Like most small-cap software firms, it’s vulnerable to lumpy contract awards. Last year the firm had a weak H1, but bounced back surprisingly well in H2.
This year’s performance has reverted to a more typical H1 weighting. Last week’s H1 results showed revenue of £14m and adjusted pre-tax profit of £3.35m for the six-month period. This translated into earnings per share of 7.4p.
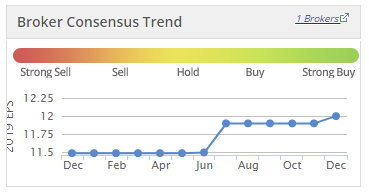
Stockopedia is showing full-year consensus revenue forecast of £23m with earnings of 12p per share. So about 60% of these forecasts were delivered in H1. Finn Cap has responded by tweaking forecasts higher for the current year:
Stockopedia’s algorithms certainly like this stock. At the time of writing D4T4 Solutions has a Style of Super Stock and a StockRank of 94.
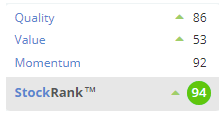
I think it’s worth drilling down into this score to take a closer look.
Value score is confusing
I wouldn’t expect a fast-growing small-cap technology stock to score highly for value. But D4T4’s ValueRank isn’t all that bad:
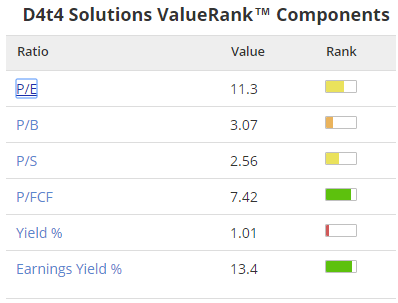
Unfortunately last year’s H2 weighting has combined with this year’s H1 weighting to provide an exaggerated boost to trailing 12-month (TTM) earnings. Let me try to explain.
P/E: Almost all of last year’s profits were generated in H2. This unusual performance was followed by a more typical H1 weighting this year.
This gives TTM earnings of about 16p per share. I don’t think this is a meaningful figure in this context. I’d prefer to use last year’s adjusted eps figure of 11p, which gives a trailing P/E of 17.5.
P/FCF: In my view, strong free cash flow is essential in a business like this. It provides evidence that sales and profits are being converted to cash, something which can’t always be relied on.
First impressions are that cash generation is good, but rather lumpy:
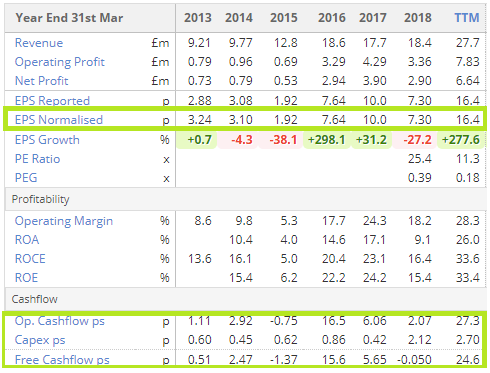
I’d prefer to see more consistent cash generation. But I am encouraged by the fact that D4T4’s net cash balance has risen from £3.4m to £12.2m since March 2016, while the share count has remained unchanged. Net cash now accounts for about 15% of the £70m market cap.
Earnings yield (EBIT/EV): An earnings yield of 13.4% represents the return available to the owner of the company before tax and financing costs. The strong half-year results have lifted this metric well above my threshold of 8%.
As with the P/E ratio, this measure of valuation has been given a boost by last year’s heavy H2 weighting. However, last year’s statutory operating profit of £4.4m gives an earnings yield of 7.6%. I’m prepared to accept this if the firm’s profits appear to be of good quality.
Quality score suggests competitive edge
One criticism often levelled at software companies is that they capitalise the cost of developing software. This reduces reported operating expenses, thus boosting profits.
The argument put forward by companies which do this is that they’re creating lasting assets. Because software can generate revenue for multiple years, the cost of developing it should also be depreciated over a number of years. This is the same approach that’s taken with machinery, for example.
Personally, I don’t share this view. I see software development as an operating expense that should be deducted from profits when it’s incurred. Software development is primarily salary costs, after all. So I’m pleased to report that D4T4 does not appear to capitalise any of its development expenses, giving us a clean view of profits.
This sets the tone for a fairly decent quality score:
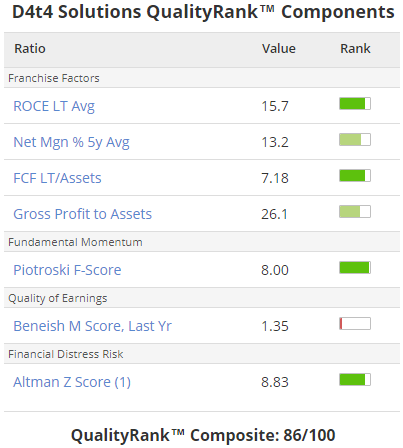
A long-term average return on capital employed of 15.7% suggests a decent quality business with some degree of competitive advantage. In this case I think this comes from the intellectual property relating to the firm’s data collection and analysis software.
Are short-selling screens a concern? D4T4 qualifies for two of Stockopedia’s short-selling Guru screens, the Montier Cooking the Books screen and the Beneish M-Score screen.
From what I can see, two likely reasons for this is last year’s unusual H2 weighting and the group’s lumpy contract wins. These factors have created big swings in receivables relative to sales, plus other statistical distortions. I’m not convinced that these short-selling screens are a good enough reason to avoid this stock.
Momentum is crucial
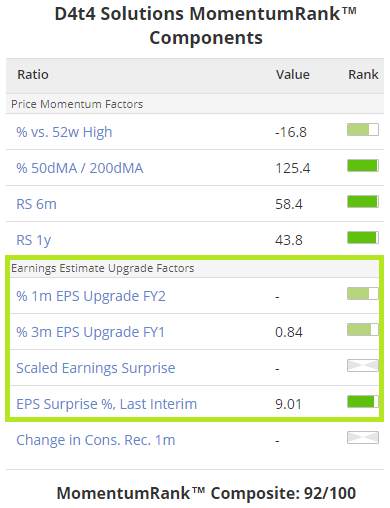
The latest note from D4T4’s house broker, Finn Cap, suggests that “our FY 19 forecasts look extremely secure even with a few more contracts to be closed in H2”.
The stock’s MomentrumRank of 92 certainly seems to suggest that a broker upgrade or earnings beat might be possible as we near the 31 March year end:
Looking ahead, forecast eps growth needs a little explanation.
Last year’s adjusted earnings of 11p per share have been restated to 8.8p in line with IFRS 15. These new rules govern revenue recognition from customer contracts, so are very relevant to SaaS firms.
Broker forecasts for the current year have been calculated to reflect IFRS 15, so the consensus figure of 12p per share indicates that earnings are expected to rise by 36% this year. This puts D4T4 Solutions on a forecast P/E of 15.5, with an expected yield of 1.5%.
This doesn’t seem an unreasonable price for a company with high profit margins and strong growth. My concern is that the SIF folio’s fairly short 9-month holding period means that if new contract wins are delayed, I could be forced to sell at a sharp loss.
My decision: Despite this risk, I think it’s fair to say that D4T4 does satisfy my screening rules. So I’ll be adding the shares to the SIF fantasy fund this week, following the publication of this article.
Disclosure: Roland owns shares of Motorpoint and Character
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

9 comments
not quite at ATH - that was 295p on 1/9/2000 though you may be excluding that exuberant time ( I don't as I took a few hits though not many thankfully)
Doesn't look to be too big an overhang from the volume profile back then but we've had fair share of double top reversals over the past 6 months and d4t4 has quadrupled in just over 2 years
price tends to be lumpy given low liquidity, some days volume is as low as 10-20K. D4T4 are also buyng-back shares and bought 10,000 today at 240p so its probably a combination of the RNS and buy-back. I am long and have been for while so don't mind the lumpiness: its a slow burn but getting there
RNS out just now £D4T4 the AIM-listed data solutions provider, is pleased to report a number of new significant global contract wins and extensions in key vertical sectors for its Data Management and Data Collection business areas.
I hold
Not a number in sight though, so why the price jumped 11% is a mystery to me
Shares are at all time highs (post dot com) therefore there is no overhead resistance. Any positive news is going to take this higher. The April trading update will hopefully give the figures you are looking for
Great report, Roland.
Worth mentioning, on a trailing basis, operation margin =28% and ROCE =34%. These are impressive and I'll be keen to see if they stick come the FY results. Now that would be impressive.
Hi Ramridge,
I think that £D4T4 TTM operating margin and ROCE are likely to fall back to historic levels when the full-year results come through. These ratios will have been boosted by last year's H2-weighted profit being added this year's H1-weighted figure.
Having said that, ROCE has generally been impressive in recent years, averaging nearly 16% since 2013.
Regards,
Roland
The Celebrus platform ties together all customer/customer touch points across all digital channels including voice, email, web, social media etc and integrates these to allow much deeper management and development of prospects. Apart from the obvious e-commerce/abandoned carts scenarios, this is particularly useful (and used) by call centres and B2B applications. Their IP is patented and I see enormous growth opportunities for them especially in an increasingly more fragmented multi-channel world: they are actively going after the elusive "omnichannel" conundrums
Some good case studies on their sites to give a better insight of what they do
https://www.d4t4solutions.com/...
Worth noting they have partnerships with big houses like teradata, sas, microsoft
Blue Prism (LON:PRSM) really took-off when they partnered with Accenture on roll-out .
Clearly I am long .....
finnCap has published a recent note following the interims : it is worth a read
from finnCap
New segmental analysis: The Interims present a revised segmental analysis
breaking down the previously rather opaque and lumpy ‘Projects Work’ revenue. It
reveals the high level (46%) of high-margin own-IP product in the H1 sales mix, as
well as suggesting c.£5.5m annually of recurring support & maintenance revenue (in
addition to the growing SaaS revenue, which has yet to reach material levels).
Great write up Roland - D4T4 are my No 1 holding having owned them since they were IS Solutions back in 2011. Lumpiness may continue to some degree but mgt are very focussed on mitigating this and recurring revenue streams are ramping up. You forgot to mention they have freehold property assets (their Sunbury HQ) and the mgt team with Peter Simmonds as Chairman are high quality.
Lots to like.