SIF November review: A 37% gain from Plus500 + should I keep NWF & Motorpoint?

We still don’t know whether Theresa May’s Brexit deal will be supported by MPs, but I have a strong feeling that a cliff-edge Brexit is increasingly unlikely. I feel this could be good news for our stock portfolios.
Markets hate uncertainty and according to this article in the FT (paywall), $1tn $20bn (the article has been corrected) has been withdrawn from UK equity funds since the referendum in 2016. Data provider EPFR says that money has been pulled from UK equity funds “every week since the UK voted to leave the EU”.
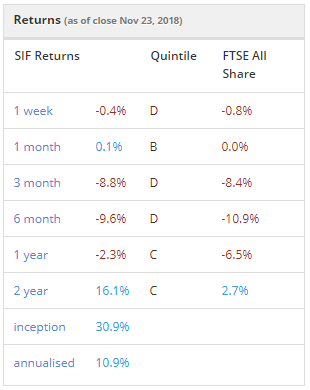
If this uncertainty can be resolved, then perhaps 2019 will be a better year for stock market returns. In any case, I’m pleased to see that after a difficult couple of months, the SIF folio has stabilised and remains ahead of the wider market:
Three stocks up for review
It’s the end of another month, so it’s time to review stocks that have been in SIF for nine months or more. Three companies are in the spotlight this week:
Used car supermarket Motorpoint (LON:MOTR)
Spread-betting and CFD firm Plus500 (LON:PLUS)
Farm feed, fuel and distribution group NWF (LON:NWF)
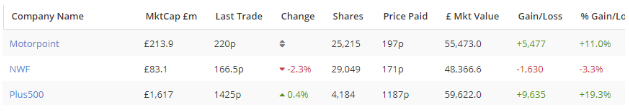
Here’s how each stock has performed so far during its time in the portfolio (excluding dividends):
Motorpoint (LON:MOTR)
This used car supermarket group has become the folio’s longest-serving stock. I’ve become a reluctant fan of this business, which generates outstandingly high returns on capital:
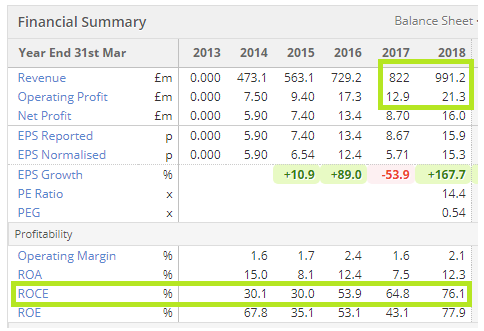
Having said that, I’m not blind to the high level of operating leverage on display here. Last year, a 20% increase in sales resulted in a 65% increase in operating profit.
Although this seems to be an exceptional result, I guess such leveraged gains are to be expected when most used car stock is purchased with a credit facility. The group’s main fixed costs are its sites and staff, neither of which changes significantly when sales rise.
Of course, the downside of high operating leverage is that it works both ways. If sales fall or consumer credit availability tightens, profit could fall fast.
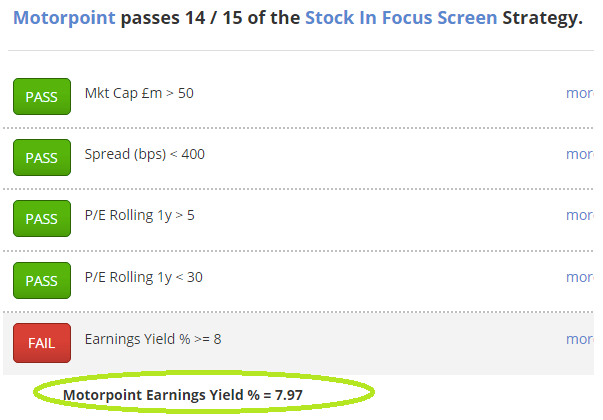
My decision: I’ve run Motorpoint through my screening tests to see whether I can keep the shares for another month. On paper, Motorpoint fails to qualify for my screen because its earnings yield (EBIT/EV) has fallen below my 8% minimum.
However, on closer inspection it’s still very close indeed:
Motorpoint is due to publish its half-year results on Thursday (29/11). Broker forecasts suggest profits are expected to rise this year. This view was backed by the firm’s half-year trading update, which reported a 9% increase in revenue and operating margins at “a similar level” to last year.
I’ve decided to hold onto Motorpoint for another month, so I can see whether the stock still qualifies for SIF after a fresh set of accounts have been loaded into Stockopedia’s database.
This decision isn’t without risk. If this week’s half-year results are worse than expected or contain a negative outlook, the shares are likely to suffer.
As always, this is only my opinion. Please do your own research before making any decisions about your own investments.
Verdict: Hold
Total return to date: +14pc
Plus500 (LON:PLUS)
This Israeli financial trading firm tends to attract strong views. There’s no doubt that its free cash flow and profits are real. But it’s always been hard to understand why it’s so much more profitable than rivals such as IG Group (in which I own shares).
Understanding the operating model: Whatever your view on Plus500, I would strongly recommend Graham Neary’s detailed analysis of the group’s risk management process. This was published after the firm’s July trading update. Graham’s report prompted a strong reader response and the comment thread is well worth a look.
I continue to feel that this is a business with an uncertain long-term future. But I’ve given up trying to guess when things might go wrong. Plus500 has certainly delivered fantastic shareholder returns so far.
A volatile year: Back in August, the SIF holding was up by about 70%. Shortly after, the group’s interim results warned that “it is unlikely that the exceptional performance of H1 2018 will be repeated”. Management also cautioned over the impact of new EU rules limiting leverage for retail traders.
This news was followed by a £145m share sale by three of the firm’s founders. Understandably, many investors saw this insider sale as a sign that profits may have peaked. It’s only recently that the stock to regain some of its previous momentum:
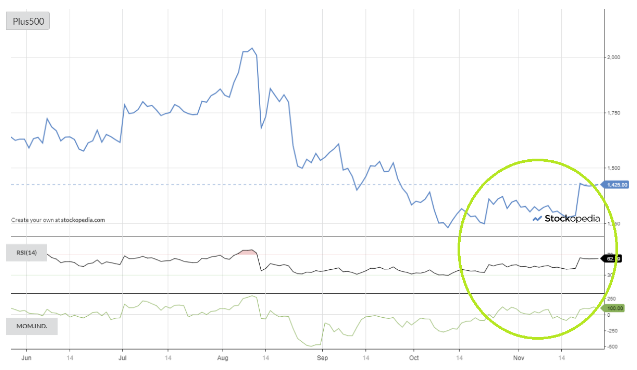
My view: Although this firm’s results have a track record of beating expectations, it does seem likely to me that the new leverage limits and the likely end of the cryptocurrency boom will hit profits from the group’s fairly inexperienced client base.
In any case, forecasts for falling earnings mean that the shares no longer pass all of my screening tests and must be sold from the SIF folio.
An 18% dividend return: Although Stockopedia’s Fantasy Funds don’t include dividends, I run a mirror Folio in Stockopedia which does include dividends.
My timing with Plus500 has been good in terms of income. I’ve circled the payouts I’ve received in the picture below, taken from Stocko’s dividend report:
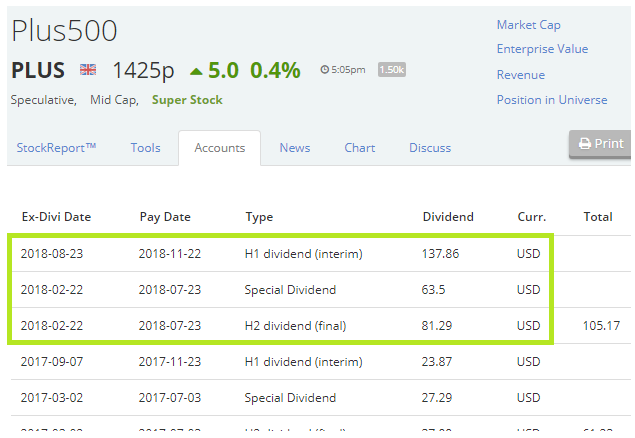
These payouts totalled about 217p per share, assuming a rate of $1.30:£1. This works out as a dividend return of 18pc. Not bad for nine months.
When added to the stock’s 19% gain, this gives me a healthy total return of 37%.
Verdict: Sell
Total return: +37pc
NWF Group (LON:NWF)
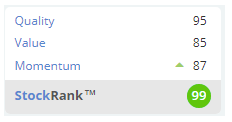
Selling fuel oils, agricultural feed and running a logistics business are all activities characterised by low margins and low investor interest. Despite this, NWF is a profitable and successful business that scores very highly with Stockpedia’s algorithms:
The firm delivered bumper profits last year, as the long, cold winter boosted heating oil sales. Thanks to some poor planning I had to order oil for my home boiler during the cold spell in March. It was clear to me that suppliers took advantage of the cold weather to hike prices.
NWF admitted as much in its full-year results, noting an increase in pence per litre profit:
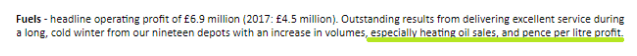
The company expects “a return to more normal trading conditions in Fuels” this year. This is expected to translate into lower profits. Analysts are currently forecasting a 14% reduction in earnings per share to 14.3p: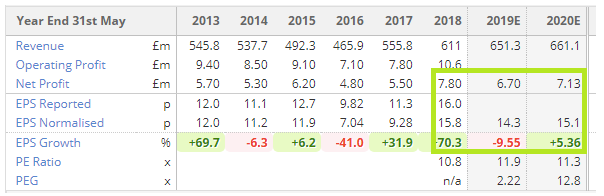
(The company’s own adjusted eps figure for 2018 was 16.7p, giving a slightly larger decline than shown above.)
My decision: I like NWF. It has a strong balance sheet and appears to be well run. I’d see it as a dividend stock to buy on the dips and hold long term. But that’s not my aim with the SIF folio, which requires companies to demonstrate continued earnings growth.
Falling earnings forecasts mean that NWF no longer passes all of my screening tests. As a result, it will be sold from SIF this month.
A lacklustre share price performance means that the holding has broken even after receiving a dividend return of 3.7%.
Verdict: Sell
Total return: +0.4pc
Next week
My SIF stock screen is showing just nine shares at the time of writing.
Most of these are already in the folio or are duplicates of stock which are. This means that I may not be able to add a new stock next week. If this happens, I will take a look at results from recent buy Character Group and Motorpoint, both of which are due on 29 November.
Disclosure: Roland owns shares of IG Group, NWF, Plus500, Character & Motorpoint.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

13 comments
Hi Roland,
I could not find the screening rules for stock selection your site.Could you tell me where to find them.
Best Regards
Martin
Roland interesting to note that you hold both Plus500 (LON:PLUS) and IG Group (LON:IGG) . Doesn't this break any of your personal rules on diversification? Given that many of us will also already hold other financials as well I wouldn't have the stomach for both. If you had to choose one which of these would you plump for? I think PLUS Is up 50% YTD while IGG is slightly down....
Re Motorpoint (LON:MOTR) . It is a shame that Stockopedia can't use the data that would have been in the floatation document - I would be uncomfortable investing with only 5 years of data particularly given that the 5 years has been a period of particularly cheap credit. Having said that I have used them to buy a couple of cars and was impressed.
Thanks
Hi Merlotman,
Thanks for your comment. My holding in Plus500 (LON:PLUS) (which I've now sold) and IG Group (LON:IGG) fall into two different parts of my portfolio.
I held Plus500 in the section of my personal portfolio which mirrors the SIF.
My IG Group holding is a long-term holding in a different part of my portfolio, unconnected with SIF. I would certainly choose IG over PLUS as a quality/long-term buy.
Re. Motorpoint (LON:MOTR), I agree that profits could fall sharply when the economic climate changes. I tried to emphasise this risk in my comments.
Regards,
Roland
Disclosure: I own shares of Motorpoint and IG Group.
Hi Roland,
I also agree with Neary`s analysis of Plus 500 risk management process. However a lengthy conversation with one of the executives of a rival company after a seminar and after a few bevies it was revealed to me that a high proportion of their income came from a client base of new and inexperienced investors and they were considerably dependent on a steady flow of similar investors through advertising and seminars. Only about 7% of these actually made profits.
Plus 500 is a particularly difficult share to manage for the purely fundamental investor. As a techno-fundamentalist I had this share on my watchlist for some time and finally bought on the price breakthrough on 9/8/17. This was a good starting point from a technical point of view as the share had tried to break through from the 800p level in Apr/May 2015 and then again in Oct 2016.
Finally the breakthrough came with massive volume that was confirmed by all my volume indicators.
Such an increase in volume invariably indicates buying by the big boys and this was followed through
until their commencement of distribution with the selloff on 13/8/2018 with a pullback of 16% in just one day.The distribution continued in clearly defined steps until about 17/10/18.
The recovery in volumes started in late Oct 2018 and has progressed steadily ever since and currently we have a divergence between price and volume action.
The volume action is the key for this share`s progress but in view of the current overall market situation, I will wait till this is resolved before considering a long position.
Regards,
Bill.
Hi Bill,
Thanks for your comment re. Plus500 (LON:PLUS). I think Plus500 is fairly open about its dependence on new customers. For example in the H1 2018 results, new customers of 94,148 accounted for nearly 40% of total active customers (248,564). In H1 2017 the proportion of new customers was even higher.
(New customers and active customers aren't defined in exactly the same way, but they should be comparable.)
By definition I guess many new customers are inexperienced and likely to lose money. I know I did when I first had a spread-betting account.
I don't monitor the technical aspects in the way that I know you do, but I do agree that the situation at present isn't clear cut. At this point, I'm happy to be out with a reasonable profit.
Regards,
Roland
Hi. I have held NWF and noted how cold weather boosted profits. The warning of lower levels may be affected by the met forecast of a relatively severe winter.
Hi AMD55,
You're right re. NWF (LON:NWF), we could easily have another severe cold spell. Presumably this would give the Fuels division a boost similar to that seen earlier this year. Speculating on the weather is a risky business, though :-)
Regards,
Roland
Yes, I'm puzzled too, with the DUP, SNP, Labour and not a few Tories against the deal it seems unlikely to be passed by Parliament. There also seems to be even stronger opposition to a 'no deal' Brexit which Mrs May sees as the inevitable alternative to her plan. On the face of it this is even less likely. Is this what you mean by the 'cliff edge'?
what do you mean by a cliff edge Brexit is increasingly unlikely? I am not being ironic here. Do you mean that May's deal will go through? Sorry to be so stupid.
Hi Marilyn
You're not being stupid! I'm speculating wildly!
My personal view is that at the last minute, some kind of arrangement will be agreed that will enable the UK to continue trading with the EU, flying aircraft, etc.
Markets hate uncertainty and politicians don't like to lose control. This combination suggests to me that a deal will be done. It probably won't seem great to Joe Public, but UK plc will be relieved.
I could be horribly wrong. This is just my opinion, based on guesswork and my observation of how the EU has dealt with other difficult situations in recent years. Please DYOR!
Regards,
Roland
Hello Roland
One often hears it being said that markets hate uncertainty. But markets are a function of uncertainty. It's because we all have different views of an intrinsically uncertain future that we have buyers and sellers. If everything was certain how can you have buyers and sellers. The reality is markets love uncertainty and can not exist without it.
Best regards
Graham
Hi Graham,
Good point re. uncertainty. I agree that both sides of the market must taking opposing views on a future that's intrinsically uncertain.
What I should have said is that markets often apply a discount where there is a giant unknown involved, as with Brexit. Where individual companies face such an uncertainty, it's quite common to see their shares rise when it is resolved. Sometimes this seems to happen even when the solution isn't especially favourable.
Best regards,
Roland
Mmm. I understand your sentiments MT and it is an appalling deal but I cannot help feeling that at the end of the day - which may be after a second voting attempt (???) - it will pass with a number of Labour rebels. It would be nice to imagine our politicians with some backbone but unrealistic to imagine that they would suddenly find some.
As regards the 'catastrophe' of a no deal Brexit, it will indeed be pretty bad but I think most commentators underestimate the resilience of UK business in finding solutions.
Just a thought ...