Small Cap Value Report (Tue 20 Nov 2018) - KCOM, AO., TUNE, PLUS

Good morning, it's Paul here.
To get you started today, I've belatedly written last Thursday's report, which is here. It covers 3 interesting shares;
Norcros (LON:NXR)
Card Factory (LON:CARD)
Swallowfield (LON:SWL)
Mello London - next week - 26-27 November
It's almost time for the next Mello investor show, run by my friend, renowned investor, David Stredder. Click on the blue title above to visit Mello's website, where tickets are available.
** STOP PRESS!!! ** - David has just messaged me with a £25 discount code for Stockopedia readers: MLStocko25
Many readers here will have been to previous Mello events, and experienced what positive, friendly, and informative events these are. David is highly selective in choosing which companies and speakers are allowed in to present to investors. So think decent quality companies, not scammers trying to get the gullible to part with their money, as is sometimes the case at some other investor shows.
The schedule of presentations has just been published, here - with some really excellent speakers.
The Stockopedia team will be there - Ed's talk at 2pm on Monday will, I'm sure be a highlight.
I shall be doing the Small Cap Value Report live, at 1pm on Monday. Graham will be doing the SCVR live on Tuesday morning at 9:20 - I refused to do the morning slot! Then at 4pm on Tuesday I'll be doing a talk on small caps - themes & ideas.
We have socialising & poker in the evenings too, so I wonder if Graham and I can make it a SCVR clean sweep again?! (I won the poker tournament at Mello Derby on day 1, and Graham won it on day 2!)
I'm very much looking forward to catching up with many of you at this event. I'm not interested in, and won't be appearing at any other investor shows - to be honest I hate doing talks, as it's incredibly stressful. But the atmosphere at Mello is so warm & supportive, that it's a pleasure to meet up with many investor friends who attend Mello events, and chat about small caps for 2 days!
KCOM (LON:KCOM)
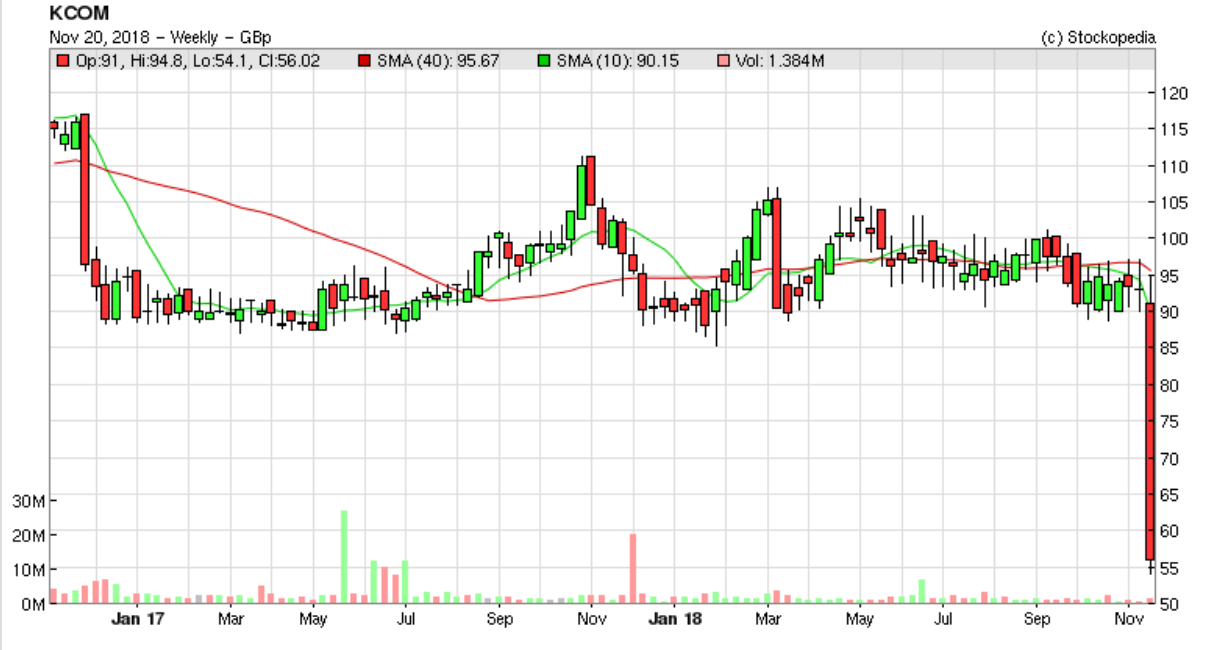
Share price: 56.2p (down 39% today, at 08:54)
No. shares: 516.6m
Market cap: £290.3m
Trading update & revised dividend commitment (profit warning)
This is an IT and communications services group.
I last looked at it here, in June 2013, so can't really remember anything about it. As usual in such a situation, my first port of call are the Stockopedia graphical history, below;
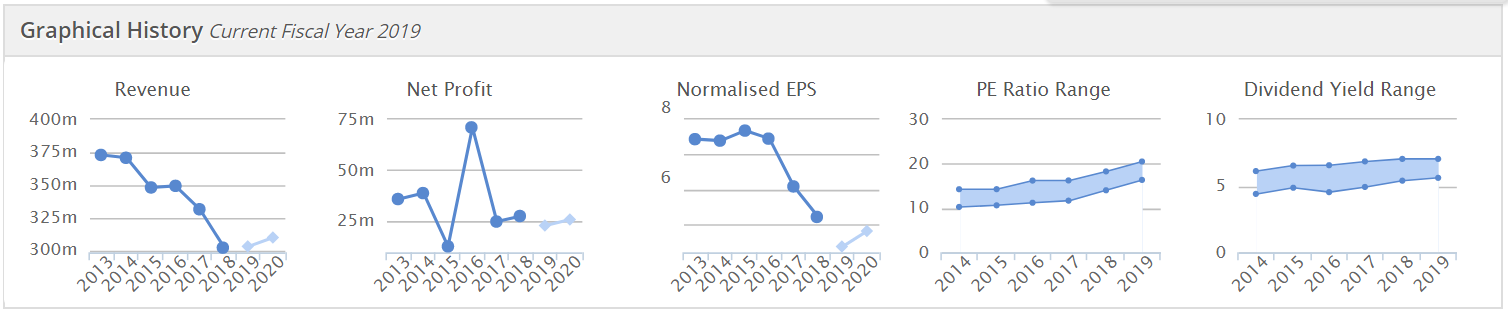
Declining revenues & EPS paints a picture of a mature, or declining business. So why has the PER steadily gone up in the last 5 years (graph 4 above)? Graph 5 suggests that the generous divis attracted investors. Although I note from the StockReport that divis were not covered by earnings - the dividend cover being only 0.73 (forecast, before today's profit warning).
So it didn't look very appetising even before the profit warning.
What's gone wrong?
The Board now believes that the Group's trading performance for the current financial year ending 31 March 2019, on a pre-IFRS 15 basis, will be weaker than originally expected. This is principally the result of flat revenue (driven by lower than expected order intake) in the Group's Enterprise segment and continued customer churn in the Group's National Network Services segment ("NNS").
It is the Board's view that these trends will continue into the following financial year.
Impaired goodwill - a £32.2m exceptional, non-cash charge will be booked.
The most profitable segment (Hull & E Yorks) of the business is still performing well, with a positive outlook due to new product launch.
Quantifying the damage - not too bad this year, but sounds worse for next year;
As a result, the Board now expects EBITDA (pre-IFRS 15) for the current financial year ending 31 March 2019 to be c.5% below current market expectations.
However, as a result of the factors outlined above, it is also the Board's expectation that EBITDA (pre-IFRS 15) for the financial year ending 31 March 2020 will be significantly below current market expectations.
It's a question of getting hold of updated broker forecasts, and then seeing if the share looks attractive.
Net debt - has shot up to £108.5m at 30 Sep 2018, which is £40.7m up on a year earlier.
Year end (31 Mar 2019) net debt is expected to be 10% higher than market expectations.
Dividends - sensibly the Board has decided that paying uncovered divis does not make sense. So the expected 6.0p divis for this year will now be halved to 3.0p.
Uncovered divis, at companies with a pile of debt, are rarely sustainable. So income seekers clearly made a mistake buying this share.
Balance sheet - I've had a quick look at the most recent balance sheet, dated 31 Mar 2018. It's not very good. Only £13m NTAV. Quite a lot of debt (as mentioned above).
My opinion - not my sort of thing at all. I have no interest in the telecoms/IT services sector, as it's very difficult to pick the winners.
This share is however a good lesson in making sure that big divis are (a) well covered, and (b) sustainable, in terms of both cashflow, but also balance sheet strength. The big divis here were not covered by earnings, and the balance sheet was weak - so an accident waiting to happen really. I'm not tempted to catch this falling knife.
AO World (LON:AO.)
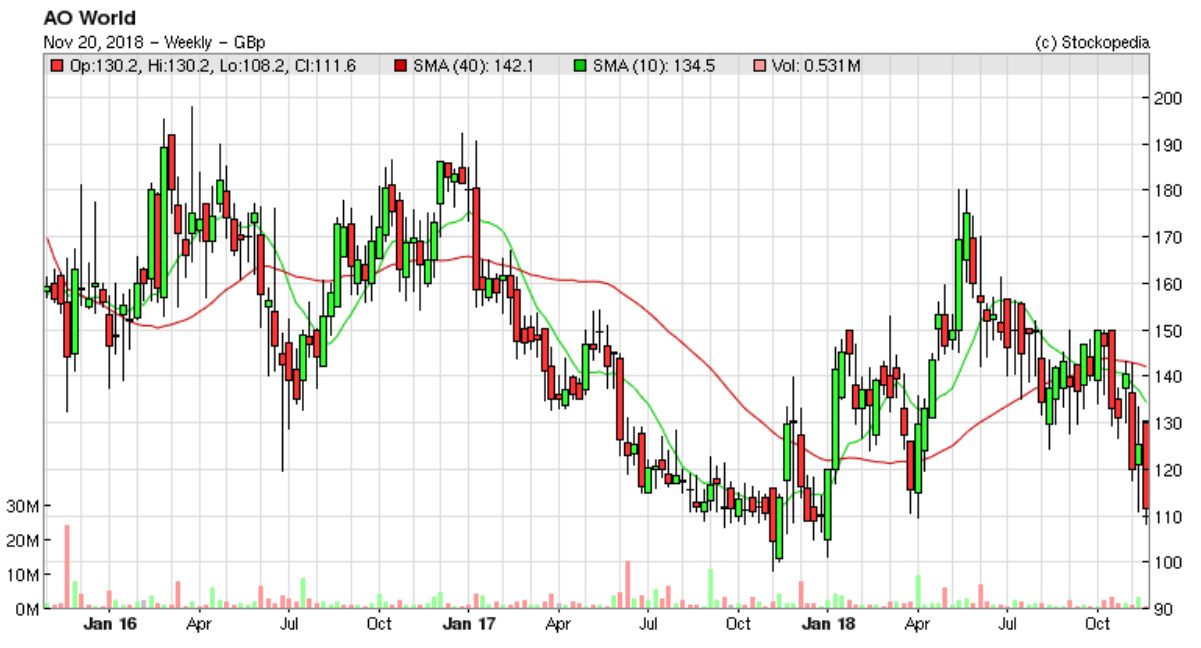
Share price: 112.2p (down 10.4% today, at 09:20)
No. shares: 458.8m
Market cap: £514.8m
AO World calls itself "a leading European online electrical retailer", but it's really a UK company, with a struggling, loss-making, sub-scale European operation too. Looking at these numbers, I think it's probably only a matter of time before they have to face reality and close down the European operations.
Revenue growth in H1 is only +9.9% - that's not enough to justify the sky-high rating.
It's loss-making at the adjusted EBITDA level - due to heavy losses in mainland Europe of -£12.3m on £69.4m revenues - an awful result. UK is EBITDA profitable at £6.9m.
Outlook - the dreaded H2-wighting;
Our peak trading period began on 9 November with the launch of our biggest ever Black Friday and I remain confident of achieving long-term sustainable growth across the Group.
We expect full year results to fall within the range of Board expectations, albeit more second half weighted than previously anticipated."
My opinion - I think this share is worth 20p, tops. Why it is still over 100p, I have no idea.
It's just not a very good business model - low margin box-shifting, in a highly competitive market. Do customers really care about service levels, for one-off purchases? I think most people just shop around for the best price.
Bottom line is, it doesn't make any money, and isn't growing very fast. So what's the point? This looks a good potential shorting opportunity, in my view. It amazes me how the valuation of this company has remained so high, given lacklustre performance, for so long. We're now in much more sceptical market conditions, so perhaps that might be about to change?
Plus500 (LON:PLUS)
Trading update - just a quick mention, as it's not a small cap.
Another positive update today from this CFD provider;
... the strong momentum reported in its Q3 Trading Update issued on 23 October has continued into November to date. Accordingly, the Board believes that the Group's results for the financial year ended 31 December 2018 will be ahead of previous market expectations.
Outlook comments are also positive.
I've long ago given up trying to work out what the prospects are for this company!
It would be interesting to find out how much of its growth & profit has come from crypto-currency punters? It looks as if that bubble is blowing up at last, with Bitcoin now at "only" $4,400, compared with its peak just under a year ago of about $20,000. Of course, the actual value of bitcoins & other crypto-currencies, is nil. It's just been a giant speculative bubble.
Where will that leave Plus 500, once its punters have run out of cash?
The profits & cashflows at Plus 500 are real, it's whether they're sustainable that is the crucial question? It will be fascinating to see how this pans out in the long-term. Today though, the market loves it, and PLUS shares are up 8.7% to 1397p.
Focusrite (LON:TUNE)
Share price: 427.5p (up 1.4% today, at 10:46)
No. shares: 58.1m
Market cap: £248.4m
Focusrite plc (AIM: TUNE), the global music and audio products company, announces Final Results for the year ended 31 August 2018.
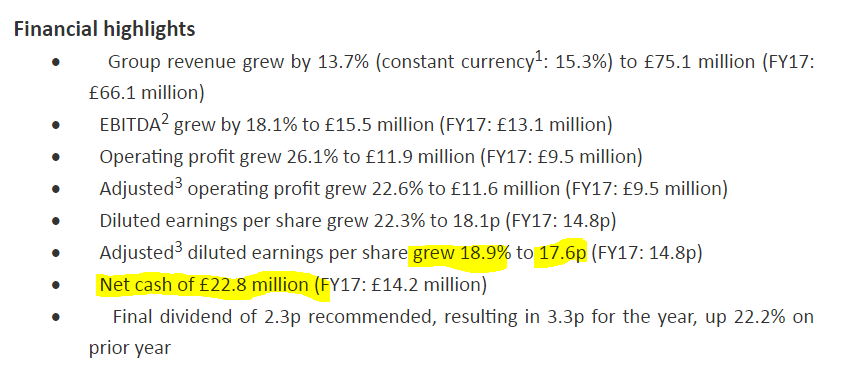
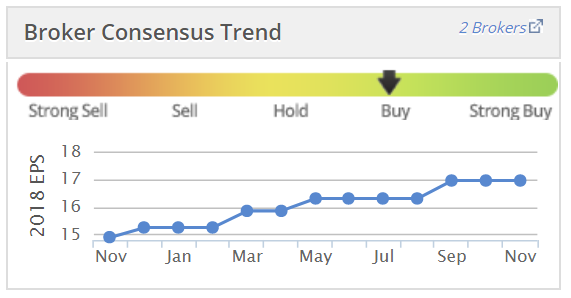
The financial highlights look really good. This looks like a modest earnings beat - Stockopedia shows consensus of 17.0p normalised EPS expected, versus 17.6p achieved;
Balance sheet - is terrific, very strong, with plenty of cash.
Cashflow statement - also excellent, but worth noting that it capitalises a fair bit into intangibles for development costs presumably. That was £3.9m this year (£1.1m higher than the amortisation charge), and up from £3.1m last year. So profits are being slightly flattered through this accounting treatment, but it's not a big issue. I'm just mentioning it for completeness.
Valuation - is quite high, at a PER of 24.3. That looks deserved, on the historic performance, but obviously that doesn't leave any room for future disappointments.
Outlook - on first reading this, earlier today, I thought it sounded slightly wobbly. However, the market seems comfortable with it, as the share price is up at the time of writing;
Last year, we had a record period pre-Christmas driven by a burst of demand for the Group's more consumer-oriented products such as Launchpad, resulting in a weighting in favour of the first half.
As anticipated, trading in the first few months of this financial year has been broadly similar to the results achieved in the same period last year.
The Board expects the current year to follow the Group's more usual seasonal pattern and, at this early stage, believes that Focusrite is well placed to deliver further growth for shareholders.
That seems to be saying that performance in the current year-to-date is slightly down on last year. To me, that's not a strong enough outlook statement for a stock on a PER of 24 times.
I don't have any updated forecasts for the new financial year, but have found 17.0p and 17.2p as (possibly out of date) estimates - barely changed from what has just been reported for the past year.
My opinion - this is an excellent company, which has performed very well in recent years.
However, as alluded to above, I question if the PER of 24 is justified, given that forecasts seem to assume negligible earnings growth. That is reinforced by a not particularly strong outlook statement.
Investors need to be very comfortable that the company will out-perform again this year, to justify the toppy valuation. It's done very well in the past, so many continue to do so.
The trend over the last year has been for steady increases in broker consensus, so that's reassuring. Maybe the same pattern might once again play out this year too?
All done for today. I'll add some brief additional company comments into tomorrow's article, so that everyone sees them.
Regards, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

42 comments
I sold out of TUNE over the course of last week. Whilst my valuation model still suggests they are fair value, I see more downside than upside potential at present.
The risk for me comes from the potential lack of top line growth that is needed to justify the PE rating. The fact that constant FX revenue growth for 2018 FY was 15.3%, compared to 26.0% for 2018 H1, tells a story about 2018 H2. The culprit was the Novation segment, where constant FX revenue in H2 was actually down 6.6% on the prior period.
The results state that the first few months of this year have been "broadly similar" to last year. Broadly similar actually means slightly behind, and so a significant improvement is needed over the balance of the year just to deliver Edison's projected 3.9% growth, which is hardly inspiring in itself.
On balance, although I still like the business, I prefer to sit on the sidelines for the time being.
EC,
RE: Focusrite (LON:TUNE) I came to exactly the same conclusion and sold last week too. The one thing to hang on to that made me a little reluctant was that EV/EBITDA is only around 15 and they could yet use the growing cashpile to make an earnings enhancing acquisition that could make the current rating look reasonable value. And their record with acquisitions to date (Novation) is pretty good although none since flotation IIRC.
All the best, Si
Hi Wave Warrior
The NTAV already takes account of the debt ...so comparing it to EV would in effect be double counting the debt
HTH
Hello Paul
With KCOM you wrote ""It's not very good. Only £13m NTAV.""
Do you always compare the NTAV with the Mkt Cap (here £474m) or would it be the Enterprise Value (here £537m) ?
And if so, do you have as a rule of thumb an acceptable minimum percentage?
Thanks
With today's 26% fall Scapa (LON:SCPA) , which I hold, is now (unfortunately) within the scope of an SCVR market cap.
I am not sure it really should have been hit this hard but it is a salutary lesson in the damage that current twitchy markets inflict on good companies with even a modest trading slow down.
Scapa's share price had a long, good, run up to 18 months ago, since when it has stalled but there are still strong underlying improvements in the business. A notable item in the six months to 30 Sept is the reduction in the pension deficit from a slightly uncomfortable £21mm to a easily manageable £9.8mm.
Recent acquisitions should add substantially to the top line over the next 12 months and the company continues to cut back overheads. Trading profits continue to increase and cash generation is strong. I am not increasing my holding yet but this could be a stock where the price slash has been overdone.
In the "jam tomorrow" stocks Falanx (LON:FLX) jumped 23% as Amati disclosed a 11% holding following Miton's 8% and Octopus's 12.5% both disclosed last week. The equity issue of last week has therefore had exactly the institutional support that suggests that Falanx has a serious future.(I hold).
The other "jam" stock Kromek (LON:KMK) (I hold) had a very strong contract win announced that appears to underscore a growing future business. This sort of announcement can sometimes be management smoke and mirrors (see SRT !) but in this case both their broker notes on Research Tree are persuasive that this contract is a major step forward. Yes I know, these are friendly brokers, but worth reading for the argument.
As it's now outside trading hours, I'd be grateful for any ideas/answers on how to buy paper certificate shares, if it's at all possible.
I know nearly everything is online nowdays, but I'm looking to buy a very small amount of shares for someone as an xmas present. I know charges etc. will eat into this, but it's not an investment as such (although that would be nice), but something I'd want to put in a frame for them.
Thanks in advance and sorry to clutter up the SCVR, but you readers do seem so knowledgeable :o)
Edit: I should add that the company is currently trading on the AIM.
From memory the question came up on Unilever to vote on the domicile - they were going to enforce certificates to vote.
I thought you just had to contact your nominee broker and request (for a fee) - may be wrong.
There should be no problem in buying - most brokers have a fee to transfer out into certificated form (e.g. Selftrade £20 ii £50) or you could try Saga - £25 dealing fee for less than £1k value:
https://www.saga.co.uk/money/saga-share-direct-fees-and-charges
However your main problem would be if you want it to be the recipient's name on the framed novelty gift. You would probably only get it in your name from a broker and would then have to get a form from the registrar to transfer it to the recipient (to whom they would send it and not in your frame!).
Good luck
@alihaouas (#32) and @leoleo73 (#33)
Only this weekend I decided to look back into accesso Technology (LON:ACSO) to see what's been happening in the past few months. It's always been a share I wished I had bought (many years ago, from back in the Lo-Q days), but stopped by the assumption that I'd missed the boat on each occasion. Dohh !
Quite scary to see the halving from near 3000p to 1500p in the last six weeks, and a drop today to 1330p !
Have put on my watchlist to DYOR at some stage soon, as this drop does, at first glance, seem excessive even compared to the general falls.
One consolation, is that the market cap. (£380m) means it qualifies for inclusion in a SCVR now ! (sorry to all holders for that reminder !)
what about accesso-anyone knows why it hasn 't stopped falling?
accesso Technology (LON:ACSO) . I keep getting price alerts about this. There is some shorting activity but I suspect today's move is to do with movements in US tech stocks. Here are my notes about why I haven't started buying:
Large earnings adjustments (possible manipulation).
Some growth by acquisition.
No dividends - cashflow?
Some time until next meaningful results (H2 weighted). Potential accident waiting happen.
"Falling star". Recent estimate trend slightly down.
Poor cashflow - price to free cashflow about 70.
Poor balance sheet - negative tangible assets.
There is a good thread here: https://www.stockopedia.com/content/accesso-coming-to-a-theme-park-near-you-87220/
I think Burford Capital (LON:BUR) could benefit from giving a short quarterly update. The period between July and March without any news makes it difficult to have an orderly market, even when results are supplemented by capital markets events. The sad thing is that it actually discourages long term holders.
Yet another positive trading update from PLUS.
There are a couple of key reasons which people don’t necessarily understand why I think they are likely to be the enduring dominating company in their markets.
1. They own the IP and code for their trading platform as opposed to paying a license to a third party. Whilst this delivers obvious bottom line help (licenses are not cheap for their competitors and enables PLUS to compete on price) that’s not the main benefit. Because they own the IP and hence don’t have to pay a per-account fee, when trial accounts are opened, they can leave them open forever instead of restricting them to a month or 3 months which is what others do. PLUS then use push notifications to remind the trial users of opportunities (e.g. during the crypto instability earlier this year) which prompts trial users to deposit funds and become active users. This often happens 10 - 12 months after the initial account was opened and long after competitors would have closed trial accounts due to the costs. Perpetual trial accounts enable free marketing, directly into the hands of customers, at the point when they are most likely to act.
2. They are ultra-conservative about how they calculate customer retention and new customer numbers. I won’t go into the specific details but give an example that a returning customer (let’s say one who traded for a bit then empties their account and didn’t trade for 18 months) is not counted as a new customer (again different to competitors) so their customer numbers and retention are always better than the headline numbers suggest.
I have a long position which I have used the recent weakness to continue to add to.
JDW72
Spectris (LON:SXS) have put out good results, up 10% this morning, reporting sales growth particularly in Asia - backing up the claims that I read somewhere yesterday that Trump's tariffs on China are having little effect in Asia, but Chinese tariffs on US goods are hurting American exports.
Does anyone here have any insight into the fall in Burford Capital (LON:BUR) since the recent placing and capital markets event (both of which seemed to me to be very positive)?
Apart from the general market sell off maybe there is some concern about additional competition to Burford Capital (LON:BUR) coming along?
Story in yesterday's D. Telegraph about an Australian based litigation funding house (LCM) preparing to float in London next month. Additional London-based litigation funders apparently also considering potential London listings.
Personally I was impressed by the Capital Markets event webcast (why can't all companies do these?), I like that they are geographically widespread, and becoming more so, and, as explained in the presentation, what's generally bad for the markets is good for Burford Capital (LON:BUR).
I was impressed and took advantage of the drop in SP to add on Friday and again today (but what do I know?)
Burford Capital (LON:BUR) is essentially a black box that spits out results every six months . Given the confidentiality of the legal cases, there is very little way to gain any insight into how the business is performing in the interim, which perhaps encourages nervousness amongst investors during turbulent markets like this. A number of reasons to be optimistic that this is nothing more than noise: an IRR of 31%, a history of beating market expectations, an institutional placing at 1850p that suggests a wealth of opportunities , no single case being more than 4% of the portfolio.
I topped up recently too, because the medium term profit at Burford Capital (LON:BUR) should be unaffected by Brexit, Greece or other political turmoil. It surprises me that BUR has a beta as high as 0.88.
I agree that a principal reason for Burford Capital (LON:BUR) regularly drifting down between results (particularly between August and March) is the six-monthly reporting. If they had been able to come out in the last couple of weeks and give an update (presuming it would be ok to good), then I think this would have supported the price somewhat. As they don't do that, then I think people become nervous and just ditch holdings. This appears to have happened previously in benign market conditions, so my guess is the effect is exaggerated in current conditions.
Equally, it's worth considering that I think a lot of institutions who were in Burford early and made a lot of money (an obvious example being Investec but there are many others), have been selling over the last six-nine months, and that has possibly accelerated in the recent sell-off. It appears to be in a Minervini-type distribution phase now, and how long that lasts is anyone's guess.
If we believe that the recent placing was "well oversubscribed", as Burford Capital (LON:BUR) said it was, then there should be plenty of institutions waiting to buy out the current sellers. If that is correct, then the question is when do those institutions start doing that. Probably not in earnest just yet.
Just my twopenneth.
Chris
I would highly recommend the recent Capital Markets presentation that is currently available through their website:
http://www.burfordcapital.com/investors/
I've got through half the 2+ hours and it gives an insight into the business, the market and the competition; they address common investor questions and take you through how the progress of a case looks in the Income Statement and Balance Sheet.
There are a number of presenters from the business.
Be aware, that it is only available for another few days.
Thanks, yes I read the slides, but haven't heard the presentation of them. The slides re-confirmed everything I like about Burford Capital (LON:BUR) (disc: I'm long), but then it would as both me and the slides are bullish on the prospects.
But as the slides don't comment on current trading (although they do imply certain consequences as a result of the massively increased investment in the last few years), if you are a nervous investor (professional or retail) you might still decide to ditch what appears to be a sinking share.
Thanks
Chris
I just wanted to add that if any readers here would like to have a Stockopedia discount for tickets to the #MelloLondon event there is a discount code you can use.... MLStocko25 If you enter that code in the box when buying tickets then you will automatically get £25 off both one and two day ticket prices.
Hope to see lots of you there. David
Morning Paul,
Are you going to be looking at Game Digital still, or has that one dropped off the radar for good?
Brief look at CML Microsystems (LON:CML) would be good. HY results completely in line with trading update issued on 22nd October when share price remained pretty much unchanged (though had fallen back in previous weeks) yet this morning shares down c. 8%. No logic in that as far as I can see - perhaps down to semi conductor pull back in US Tech stocks?
CML Microsystems (LON:CML)
HY results completely in line with trading update issued on 22nd October when share price remained pretty much unchanged (though had fallen back in previous weeks) yet this morning shares down c. 8%. No logic in that as far as I can see.
I would say outlook is wishy washy at best - ok they expect to be on track this year but the following isn't going to result in broker upgrades after that i would imagine.
per outlook
With a growing number of customer products reaching production, the Board is confident that meaningful advances will be made as end market dynamics normalise and remains excited about the Group's future prospects.
One other item that is always relevant is the amount of capitalised costs - they mention higher r&d. Looking at the balance sheet development costs have increased by £1.2 mill net and that total is now nearly 6 months turnover and the increase is nearly 50% of profit made H1. One needs faith in the company to presume this isn't a mini red flag warning. in that respect.
So as someone who knows nowt about this stock these results in isolation don't look great on an initial inspection. This may mean a better entry point though if the r&d/development they are making pays of mid term though and at that net stage the increased capitalised amounts cease What are EPS forecasts for next year ?
Focusrite (LON:TUNE) results looked okay to me, maybe just enough to support it's lofty valuation? (In my view they would be great results from a less highly valued company)
I can't help thinking that any company not being cautious in it's outlook right now might get criticized for burying it's head in the sand. There's a lot going on right now and if I was a CEO I doubt I'd be sticking my neck out. There's no upside to being cocky right now, better just to be cautious and over deliver IMO.
I thought the Focusrite (LON:TUNE) results looked good - organic revenue growth across both segments and in all geographies, and costs were controlled.
The improvement in gross margin was a result of the strengthening EUR:GBP FX rate and closer management of customer discounts. There's very little the company can do with FX volatility but if they are able to sell more products without discounting, then this suggests they have good quality products and an economic moat.
They spend approximately 6% of turnover on R&D. Not all of this will be capitalised but this is where judgement enters into the frame. It may be better to look at operating profit v operating cash less investment spend:
Operating profit £11.9m (2017: £9.5m)
Operating cash - investment spend £10.8m (2017: £10.1m)
This shows 91% of operating profit was converted into cash compared to 106% in 2017.
Similar to what Paul mentioned, the outlook statement did not fulfill me with confidence and implied the first two months have not shown growth in revenue. However, it then goes on to state the company is "well placed to deliver further growth".
Morning Paul,
Solid but unspectacular interims from Solid State (LON:SOLI) this morning could be worth a look if you have time.
An April TA, saw the shares hit. But there has been no repeat warnings and a recovery seems to be underway.
SR 95 and superstock status also appeals.
Disc: I hold. Caught the knife in May!
Regards,
Mark
Bonmarche Holdings (LON:BON) - As MrContrarian noted, the outlook is iffy. On the plus side, online growth is running at 30%pa, and, if anything, accelerating. At end of H1 it accounted for 12% of sales and so should give significant protection from store LFL falls.
A few things caught my attention, all of which may be interesting to shareholders of other retailers:
* They have estimated how their accounts would look under IFRS 16 (the lease thing) and committed to making a full declaration for the FY. This is the first retailer I have seen to do this.
* They have taken an impairment charge under IAS36. It seems that when retailers say things like "99% of our stores are profitable" this excludes central costs. A new interpretation of IAS36 means that central costs must be allocated amongst stores, thus producing many more (they don't say how many) loss-making stores and an asset impairment charge. It seems to me that the reality of the situation is that while central costs do not rise linearly with the size of a company (due to various economies of scale), for each extra store, employee etc. there is some incremental increase in central costs. Could it be that this accounting change could trigger a more realistic measurement of which stores are profitable, accelerating the closing of shops throughout the sector?
* They are attempting to "gain a better understanding of the increasingly complex relationship between store sales and online sales". This is a concern I have had for a while about multi-channel retailers - if they closed all their shops, what would happen to their online sales? Clearly they would lose the exposure of a high-street presence and would have to increase other marketing to some degree, but also, how many of their online sales follow a trip to a physical store? How many rely on being able to collect and/or return to a store? How many of the orders reported as online are actually made within the store?
Leoleo73,
Thanks for bringing this up. The online-store and fixed cost interaction is indeed very interesting.
Personally, I think the best placed are i) the pure online shops (eg Boohoo (LON:BOO), Sosandar (LON:SOS) ) and ii) big, national store chains with strong online (eg Next (LON:NXT) which is roughly 50:50%) which have positive 2 way externalities from both a brand recognition and an operations point of view eg click & instore collect is both a benefit AND a cost saving.
In my view, the toughest place is to have a small, sub-scale shop or online operations - I would argue like Bonmarche Holdings (LON:BON) - which cannot afford the systems and specialists, not just in warehousing and dispatch but also in digital planning both internal (think ERP) and external (think marketing). This is true even if they outsource since they need someone to interact with the outsourcer. N Brown (LON:BWNG) tried to add dual fascia SimplyBe/Jacomo stores and initially claimed sales up where they had both online and stores but stores were too small to get focus and withered away.
In the case of Bonmarche Holdings (LON:BON) ,their underlying consumer base remains lower income walk-in old ladies, I think a very cold winter (as is forecast) will really hit them hard - especially as high street store sales are holding up better in destination shopping centres rather than the tier 2 places Bonmarche Holdings (LON:BON) tends to have. Even old ladies can shop at home now. Bonmarche Holdings (LON:BON) has been much improved under the current MD, Helen Connolly but I see a better future for her than Bonmarche on a mid-term basis.
DIsc. long Sosandar (LON:SOS), Next (LON:NXT), £BWNG
I'd be interested in EI (LON:EIG) please Paul (which I think you've covered before) on their results today; NAV is over £3, PER about 11.
I'd be interested in Electrocomponents (LON:ECM) too whose results looks pretty good to me... but maybe they are too big for you to cover.
There's also a short ahead-of-expectations update from Plus500 (LON:PLUS)
Focusrite finals were out this morning. Very good results again across the board. Your view please Paul.
Morning Michael,
My initial notes on Focusrite (LON:TUNE) results this morning say: good figures, but slightly tentative outlook comments. High valuation, so might wobble a bit today.
I'll look into it in more detail later.
Regards, Paul.
Eckoh (LON:ECK) Half Year results today worth a look Paul? I hold but may reduce trying to work out which way to go any comment appreciated...
Also Halma (LON:HLMA) and Easyjet (LON:EZJ) reporting
Morning John,
My initial reaction on Eckoh (LON:ECK) figures is that they look lacklustre. BUT there's talk of strong outlook, contract wins, etc. I'm not interested at the current high valuation. This stock has looked too expensive for a long time, in my view. Maybe investors are happy to pay up for the growth potential in USA?
Regards, Paul.
Thanks Paul
I wasn't overly excited either but I hold since 16p - I think its time to think about relocating for better growth prospects...
Would be good if you could cover Telecom Plus (LON:TEP) please Paul.
Results comment includes "it's been a number of years since the overall outlook has appeared as positive."
They are a muli utility Company with emphasis on providing "exceptional levels of customer service."
Their business model is so different to many other Utility suppliers and Insurance Companies with the focus on rewarding (and so keeping) their existing customers with fair premiums. The others often do the opposite with their best offers only for potential new customers. Result? TEP has a much lower churn rate. There is a lot in their statement about the quality of their offering and the reasoning behind that. And they were again "Which" Utility Provider of the Year.. They don't advertise and rely on word of mouth to attract new business.,
They claim their balance sheet is robust. Outlook sounds very positive after several difficult years.,
Small increase in the useful dividend. Share was quite strong ahead of these results rising from just over £10 to £12 and perhaps a good bit more to come?
I hold and am tempted to add, but keen to know Paul's thoughts on the figures before doing so.
KCOM (LON:KCOM) will probably crash this morning, following a dividend cut. I am disappointed MrC did not unleash his caustic wit here! Could it be an indicator of wider trends in the telecomms sector? Is it worth a look?
My morning smallcap tweet:
ClearStar Inc (LON:CLSU), SRT Marine Systems (LON:SRT), Bonmarche Holdings (LON:BON), Ilika (LON:IKA)
ClearStar (CLSU) wins contracts worth $1m PA from 2019.
SRT Marine Systems (SRT) H1 broadly in line with rev up 10%, pretax -£1.3 million (-£1.8m [pre-exceptional]). That's slightly better than the H1 trading RNS in Oct. Jam tomorrow: "expect the second half to see significant systems deliverables from multiple contracts and associated revenues as well as a solid contribution from our transceivers business."
Bonmarche (BON) H1 in line. Outlook iffy: online good but "store LFLs have remained weak, and traditional autumn/winter categories have had a slow start to the season. Providing that sales during the key Black Friday through to Christmas trading period meet expectations, the Board maintains the [FY] guidance."
Ilika (IKA) finds supplier that can make its Stereax thin film solid-state cells. In PR-flannel, it's a "manufacturing partnership".
Would be great if you could look at IMImobile (LON:IMO) Paul. I think the revenue is slightly above expectations but the organic revenue is not super strong and they might need to issue more shares in the near future to do any more acquisitions. So I think this is priced about right for now in the current market turmoil (below 300p before market open). That said, I think this whole sector is ripe for consolidation at some point so I wonder if IMImobile (LON:IMO) may become a takeover target itself? I was a bit confused by reference to one of their clients affecting their revenue but they then don't explain what the issue was (maybe it was high profile news and I missed it).
We're really looking forward to Mello too, there is a fantastic line up of speakers and companies.
Back to today, Entertainment One (LON:ETO) results overview by Darren Throop, CEO:
https://www.piworld.co.uk/2018/11/20/entertainment-one-eto-h1-results-interview-november-2018/
We'll be posting this morning's analyst presentation later today. I'll add here, and of course on piworld.co.uk.