Small Cap Value Report (Thur 29 November 2018) - Markets, RFX/HAT, CCT, MOTR, PAM

Good morning!
I got home at about 1am last night, after a delayed flight. But am feeling surprisingly chirpy, all the same.
The overall level of the market remains on my mind. I might have underestimated the extent to which the air coming out of US equities could be a headwind for UK shares. And I do think there is a lot of air that needs to be extracted from the US markets.
That being said, President Trump is not going to want a stock market crash to be the backdrop for his 2020 re-election campaign. He regrets hiring Fed Chairman Jerome Powell, who bears the ultimately responsibility for rising interest rates:
"So far, I'm not even a little bit happy with my selection of Jay," Trump told the Post. "Not even a little bit. And I'm not blaming anybody, but I'm just telling you I think that the Fed is way off-base with what they're doing."
If the Fed slows down its rate hikes under pressure from the President, that will certainly be good news for equity prices.
The market has started to price that in: after yesterday's rally, the Dow Jones Industrial Average is only about 6% off its recent all-time high. That still sounds rather optimistic to me!
Like most of you, I continue to spend most of my time looking at individual companies. But it's nice to have a sense of history and of overall valuation levels, to give the context for what we're doing. I remain bullish for UK shares, while acknowledging that the road higher will be a rocky one.
Today we are looking at:
- Ramsdens Holdings (LON:RFX)
- Character (LON:CCT)
- Motorpoint (LON:MOTR) (by Paul Scott)
- Premier Asset Management (LON:PAM)
Ramsdens Holdings (LON:RFX)
- Share price: 163p (unchanged today)
- No. of shares: 31 million
- Market cap: £50 million
Interim Results - Six Months ended 30 September 2018
What a crazy range this one had yesterday: a high of 167.5p, a low of 147.5p. Results had been reported in line with expectations.
It ended the day 2p higher than the previous day, at 163p.
Ramsdens is a pawnbroking/financial services chain based in the North of England.
It tends not to compete head-on with H & T (LON:HAT) (in which I have a long position). H&T is more concentrated in the South.
Let's take a look at some key points from these H1 results:
- FX income down marginally due to "staycations" in the UK and Easter falling outside the period
- steady progress in pawnbroking pledge book and income
- jewellery retail revenue up 27%. H&T has also made a lot of retailing progress in recent years.
- gold and silver purchasing profit up moderately.
Overall, the four divisions seem to have done well.
Perhaps some holders were surprised by this:
A small and expected decline in EBITDA year on year, reflecting the absence of peak Easter holiday FX trading, the opening costs associated with new stores, and investment in the infrastructure and team to support growth, in part compensated by improved retail jewellery and pawnbroking trading.
Despite that small decline, the cash position remains large relative to the size of the business, at £12.4 million, and the interim dividend is increased.
Why did the share price fluctuate?
This can't be answered authoritatively without interviewing the buyers and sellers. Possible causes would be:
- an unexpected reduction in profits, as holders didn't know what management's expectations were
- disappointment that FX declined, even with the excuses given for it. Last year, currency exchanged was up 22%. This year, it fell 3%. So this segment has arguably lost its momentum.
I would have a question mark about the excuse that people stayed at home due to the hot UK weather. Don't most people book holidays well in advance of knowing what the weather is going to be like at home? Are people really waiting to see what the weather is like in spring and early summer, before deciding to book? If anyone knows, please let me know!
- the outlook statement not being sufficiently rosy. H2 is said to have made a "solid" start:
Despite a backdrop of Brexit uncertainty impacting consumer confidence and struggling high streets, the Board believes that our outstanding value proposition for customers will enable the Group to continue to grow and prosper.
Why are the pawnbrokers so cheap?
This is a great question.
Ramsdens has a StockRank of 91 while H&T is rated 87.
Ramsdens value metrics:
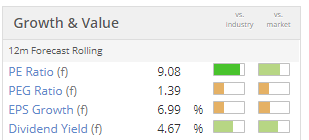
H&T value metrics:

I suppose the first way to tackle the question would be to ask: why should they be more expensive than this?
After all: they are unlikely to be long-term compounders. They are essentially like small banks with retail services and some retailer characteristics. Does that really deserve an above-average P/E ratio?
My view is that they do not deserve above-average P/E ratios. But I still like them, and find them attractive at single-digit earnings multiples.
What I like about them is that if they are managed well, they can be very dependable businesses (if they are mismanaged, they can of course blow up).
On top of that, they have some counter-cyclical characteristics and provide me with some positive correlation to the gold price.
H&T's 7.4x P/E ratio stands out to me as possibly deserving of a purchase, while Ramsdens at 9x is also quite interesting.
The recent share price weakness for both of them look to me as if it could be related to:
a) generalised High Street fears around declining footfall. Ramsdens mentioned in its results yesterday that it is relocating multiple stores - maybe this is due to the decline of certain traditional shopping streets?
b) fears around financial mis-selling claims. This doesn't affect Ramsdens so much because it doesn't have a personal loan product. It does threaten H&T. I am quite certain that any loan mis-selling claims against H&T would be frivolous, but it remains a threat.
Conclusion
Ramsdens is a cheap and cheerful stock which could be worthy of further research and purchasing at current levels.
One of my few concerns would be its growth strategy. It is pushing the boat out by seeking to open 12 new stores per annum over the medium term.
H&T's store count, by contrast, is basically flat. I prefer the strategy of sweating its existing estate. That makes sense to me in a mature industry. H&T can always swoop in and buy up failed rivals whenever the sector goes through another rough patch.
So I wonder if 12 new stores from Ramsdens each year is perhaps a little bit too ambitious. Time will tell. I do like both of these shares.
Character (LON:CCT)
- Share price: 513p (+4%)
- No. of shares: 21 million
- Market cap: £109 million
This toy company (it designs, develops and distributes them) looks to have had a good H2. It says it comfortably achieved market expectations.
Let's break down the progress in each half-year period.
FY 2017 sales:
- H1 £61.5 million, H2 £53.8 million
FY 2018 sales:
- H1 £50.5 million, H2 £55.7 million
The £50.5 million figure for H1 2018 was the truly disappointing one. We've covered the Toys R Us bankruptcy which created the mess - see the Stockopedia discussion archives for CCT.
£55.7 million of revenue in H2 2018 says that CCT has returned to its previous strength, outstripping the previous H2 figure by 3.5%.
The recovery is attributed to:
"our collaborative culture (both within the Group as well as in partnerships with customers and suppliers), the agility of our business model in addressing changes and challenges within our market and the proven skills of our central management team"
Dividend
Reflecting management confidence, we also see a 20% increase in the final dividend.
Buybacks
Character has the authority to keep buying back its own shares. Makes sense to do this in my view, given the net cash position (£15.6 million) and the excellent cash-generating ability of the business (at least historically).
Acquisition
The small acquisition of a Danish toy distributor seems to be going well so far - good news. I don't mind small acquisitions when there is a clear reason given. This acquisition gives Character a toehold in the EU for a post-Brexit environment.
Outlook - in line with expectations.
My view - all very encouraging.
Note that this share is usually cheap versus earnings, since design and distribution aren't rated as highly as ownership of the underlying IP (Peppa Pig, etc.).
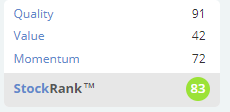
That being said, I maintain a positive impression of the group. StockRanks like it too:
(This section by Paul Scott)
Motorpoint (LON:MOTR)
- Share price: 216.5p
- No. shares: 97.2m
- Market cap: £210.4m
"Motorpoint, the largest independent vehicle retailer in the UK, today announces its unaudited interim results for the six months ended 30 September 2018 (FY19 H1)."
The KPIs table below looks pretty good, at a time when many other car dealers are reporting reduced profits. That's because Motorpoint has a different business model. It's not a franchised dealer of new cars, but instead sells nearly new secondhand cars, at keen prices.
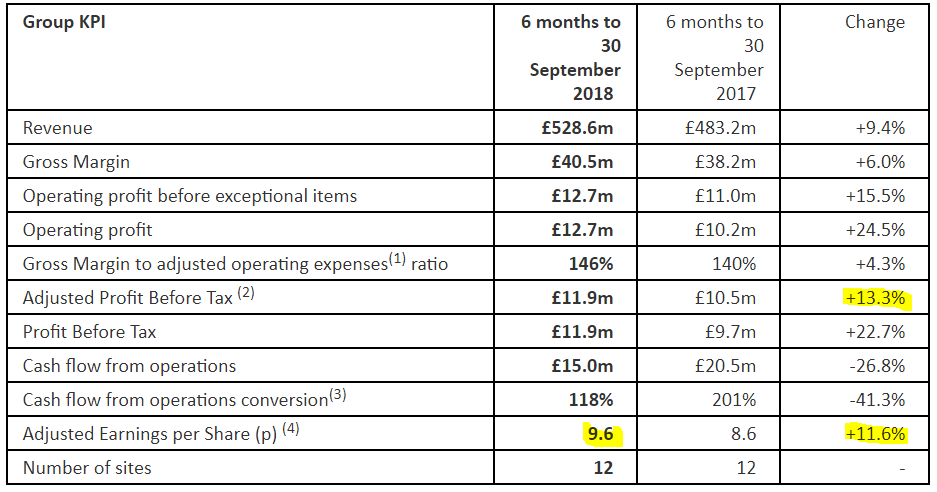
There's not really a great deal to say about this.
There doesn't seem to be much H1/H2 seasonality, therefore the broker consensus of 19.4p for the full year ending 31 Mar 2019 looks reasonable. That gives a PER of 11.2 . This is a good bit higher than bombed out shares of more conventional car dealers, which are typically on a rating of about 6-8 times. The premium for Motorpoint makes sense to me, as it has a better & lower risk business model.
Outlook comments - the key bit says they're in line, but with loads of disclaimers for possible unknown Brexit-related upheaval;
Current trading is consistent with market expectations for the full year. However, we remain mindful of the current political uncertainty, and that the potential outcomes from the Government's Brexit negotiations could influence our future performance in unpredictable ways. We are particularly mindful of the potential impacts on stock supply and general customer confidence, resulting from, inter alia, exchange rate volatility, new import tariffs or other supply chain friction, employment and inflation or interest rate changes. As per Motorpoint's normal seasonal trends, our fourth financial quarter is the most material of our full year's performance, and is therefore a key focus to ensure we remain on track.
We believe our unrivalled choice of nearly new vehicles and ongoing dedication to Choice, Value and Service positions us strongly to take advantage of any market disruption, and to continue to deliver as the Car Buyers' Champion.
Balance sheet - looks fine, no issues there. Note that inventories of vehicles are quite modest, as they're shifted fast, and there are borrowing facilities to part-finance inventories.
Also note that fixed assets are very modest. This is another advantage of the car supermarket business model - there's no need for fancy premises to promote brands for the manufacturers.
My opinion - this is an excellent business model, which I like a lot. Growth comes from new site openings, so it should be a good roll-out over time.
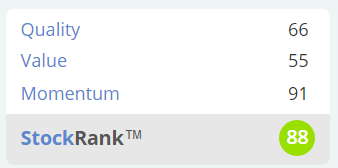
Stockopedia likes it too;
(This section by Graham.)
Premier Asset Management (LON:PAM)
- Share price: 203p (+0.5%)
- No. of shares: 106 million
- Market cap: £215 million
The last time we looked at this was in July.
Premier is a fund manager that serves a retail audience and specialises in multi-asset and income funds.
I've been impressed by its AuM growth. Exellent long-term performance must have helped. I'm not sure how Premier has done so well. All i can say is that it has caught my eye!
AuM grew another £0.8 billion to £6.9 billion by end-September 2018. It has since reduced to £6.6 billion.
Let's look at the market cap/AuM metric again: it is now 3.25%.
That feels cheap to me. When I looked at the same metric in July, it was 4.2%. The share price is down by a third from its high!
It's true that the relative performance of its funds has weakened: over five years, 83% of AuM is now beating the median return. It was 96% last time I checked. 83% is still excellent in my book.
Net inflows remained positive: 22 consecutive quarters of net inflows.
Financial results:
- adjusted PBT +29% to £19 million
- actual PBT +38% to £16 million
- EPS 12.1p
- Full-year dividend +28%, 70% payout ratio versus adjusted net income.
Outlook
The outlook sounds very challenging in the short-term:
Trading during the early part of the current financial year has been more difficult. The combination of more volatile investment markets and the ongoing uncertainty around Brexit have impacted on both the level of assets under management and the rate of fund flows. Anecdotal evidence suggests that retail investors are taking a wait-and-see approach and, as a result, fund flows have been slower in the first few weeks of the current year than they have been in recent months.
My view
I am going to research Premier in more detail. It looks to me as if the market may have over-reacted to some short-term difficulties and discounted the valuation too much. Stockopedia estimates the forecast P/E ratio at 12.4x (using last night's close) and the forecast dividend yield at 5.4%.
If I knew more about its underlying approach and how it has generated such good returns in its funds in recent years, I could easily be tempted to open a position in it!
That's all for today, thanks for dropping by and for your comments!
Best,
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

65 comments
Thanks for the update Simoan
Much appreciated & squares with what I was told too...i’ll raise with Somero too
+1 for Charles Stanley. Not the cheapest but runs smoothly for me, including prompt Somero dividends, and ability to buy uncommon stocks (eg Doric Nimrod series) by phone as not available online. I sense they don't get the keenest dealing prices which, say, Barclays achieve and this typically makes more difference than whether the commission is £6 or £12. There were wobbles a couple of years ago when a Charles Stanley strategic review suggested they were looking to dispose of Charles Stanley Direct but they seem to have decided to keep and grow it now, even though it's not a big proportion of their business.
My Charles Stanley account is the dealing end of a James Hay SIPP. I don't have many dealings with James Hay but don't understand the negativity to them in a recent post. Is it just charges or something more? I'm considering consolidating several pension funds into JH soon but ought to look at the main competitors first.
for xfers, HL are offering cash back (to £500). Certainly not the main consideration, I know, but would cover an awful lot of dealing costs, or maybe a small extra fund, as I did.
Paul,
Mention of Ramsdens characteristics makes me think of Paypoint - results out today - Stocko 80. High divi has been ongoing for a number of years. Can you comment on PAY?
Hi
I am with Barclays Smart investor and have never been happy since the move from Barclays Stockbrokers
I was just about to move to A J Bell when an unconnected smaller broker went bust and the administrator used clients funds to sort it out so I have stayed with Barclays
I appreciate A J Bell is much larger and may be shortly floated on the stock market but It is still much smaller than Barclays
If anything happens to A J Bell could my assets be used by an Administrator
I have a holding in Premier Asset Management (LON:PAM) . It is worth noting that PAM are almost exclusively retail via IFAs. Their net revenue margin is about 73bps. Comparing mcap/aum needs to account for the differing rates between institutional fund managers (about half the rate) and retail or a blend.
PAM as an investment is anchored in the attractions of the multi-asset category which has been very popular. The other day I looked at Investment Association monthly net flows data. Number of months of negative net retail sales since Jul-16 (through Sep-18): Property (11), Equity (10), Fixed Income (6), Money Market (5), Other (3), Mixed Asset (0). My spreadsheet also says that the multi-asset category at PAM grew 21.6% in the year to Sept despite Aug and Sept being very weak. There's a Liberum note on Research Tree where they have the monthly AuM by fund. All of this is despite the fact that the vast majority of their retail fundholders hold income class shares. This is part of the reason why their AuM growth over the last several years comes almost exclusively from net inflows.
I think they could have an interesting future as managers of annuity replacement products.
My only exposure to HL has been through dealing with the estate of my late father and whilst not inefficient I found them to be the most bureaucratic of all the (15+) financial institutions I had to deal with.
As a customer of A J Bell I find them to be a dynamic and agile institution and I was always impressed with the way Andy Bell responded to questions (not just those specific to his organisation) on the fool. (anyone else remember Snooper66?) I see that level of helpfulness and C/S in my interactions with Youinvest and will hence probably take part in the IPO, any reasons this could not become the next HL?
I have only invested in Somero at the recent fire sale prices so can’t comment on the delays.
Just my 2p's worth
I transferred my then cash ISA's to a Halifax share dealing account several years ago, after reading an overview of what was cost effective etc. Been very good,generally, though perhaps I am not the most demanding Customer.
Then opened a non-ISA Share dealing share accounts, and similarly generally good experience of their platform. I seem to have had good service on the few occasions I have called their helpline..
i use Hargreaves Lansdown. and though dealing charges are higher than some others. if you deal more often prices decrease.. also customer service is very good as used few times.. Deals previous month Dealing charge
0 - 9 deals £11.95
10 -19 deals £8.95
20 or more deals £5.95
Hi skinner66
Yes but surely this is a negative rather than a positive? Surely very few PI's should be making 9 trades a month let alone 20!!?
Leon Boros has only made 409 trades in 25 years. See minute 32:05 at https://www.piworld.co.uk/2018...
I am ashamed to say that I have made 300 buys and 145 sells in 10 years. Though my discipline is increasing with 27 buys this year and 13 sells this year.
Kind regards
Michael
French Connection (LON:FCCN) is up sharply today on low volume it appears. No news on ADVFN - has anyone seen anything that explains the rise?
A couple of brief points from today’s commentary/comments...
1. Anecdotally for Graham, wifey and I decided not to go abroad this summer because the weather was so good here. Typically, we book our holidays at 4-5 weeks notice. I doubt we are “normal” though as we have no kids, no pets, no old people to care for and a lot of flexibility on dates/locations.
2. AJ Bell - I agree with all that simoan says about the Somero Enterprises Inc (LON:SOM) dividend. It is not only ridiculously poor from a systems perspective but also a rip off from a customer perspective. I have concluded that I will not be participating in the IPO, although closing my account is more challenging because of trading costs (but certainly no new money will be going their way). When trust is damaged etc.
Cheers
Simon
Just out of interest, because I've had these problems myself, does anyone know if a cheque is actually involved or is this just a porky?
I just find it very strange in these days of electronic registrars and electronic payments that a cheque is actually written/printed out.
Phil
Hi,
Re Somero Enterprises Inc (LON:SOM)
I would guess that the cheque line is just a fob off. The reason being, if the holding is dematerialised then the payment usually comes through Crest. The unusual factor here is the US element, which might make it real. However, if other brokers are processing it quickly then it suggests that it is a fob off. Working it through, the company will make the payment to the regristrar in advance of payment date. The registrar will then make the payment so that it arrives by whatever means on payment date. Most of the large registrars no longer deal with cheques as it is a total hassle for them too. Assuming a cheque is paid to AJ Bell it will be in GBP as there is an adjustment factor for GBP on the payment details.
This prompts another thought, if AJ Bell charge an FX fee that is incorrect as it will almost certainly be received in GBP.
I have asked AJ Bell for details of the registrar. Some registrars are helpful and will tell you that the cheque line is true/false but others will pull the can't talk to you as you're not the holder line. I'm going to do some digging and see what I can find out. I intend to email the company too as this is an issue that they need to know about if recurring.
Whilst I saw someone had a complaint with them, this really is the best way forward as if we are all complaining and the FCA sees it then they will be all over them on the issue.
Regards
Paul
I would guess that the cheque line is just a fob off. The reason being, if the holding is dematerialised then the payment usually comes through Crest. The unusual factor here is the US element, which might make it real.
No, I don't believe it is a fob off. I had a problem several years ago with a euro dividend from Charter International that had a long delay between the payment date and the money reaching my account. Again it was paid by cheque and related to my AJ Bell SIPP (or Sippdeal as it was then). I rang the registrar Computershare to discuss why the dividend was being paid by a euro cheque and IIRC it turned out the reason was because AJ Bell had not taken up the option to have it transferred electronically. When I questioned AJ Bell about it the response was basically (if you removed all the BS) that they couldn't be bothered. I would imagine it is the same case with receiving the US dollar cheque for the Somero Enterprises Inc (LON:SOM) dividend.
So the bottom line is that AJ Bell can't be arsed to pre-credit dividends in accounts on receipt of a foreign currency cheque like other brokers, and what's more, and possibly worse, they also can't be arsed to take simple steps with the registrar to expedite the payments electronically.
I think at the end of the day it just shows that beneath the fancy website and nice clean dealing interface, the back office function is a total mess and great customer service is not their primary concern. As my other half would say AJ Bell are "fur coat and no knickers"!
All the best, Si
Hi,
Sorry to reply to my own post but I have been in contact with AJ Bell this morning by secure message and told them to respond in writing to my complaint. This is a necessary first step before referring the matter to the Financial Ombudsman Service. If any other AJ Bell customers feel like minded about the 8 week delay in paying their Somero Enterprises Inc (LON:SOM) dividend, they might want to do the same. The more weight we have behind this, the more likely we will be able to get something done about it for all AJ Bell customers going forwards.
All the best, Si
OK. My last word on this.
I have now spoken with Computershare (the registrar for Somero). It seems the root cause of the delay is actually Somero themselves who only send Bank of America US Dollar cheques to UK brokers - there is no electronic transfer option. Other brokers pre-credit dividends to accounts but AJ Bell do not (probably to avoid currency risk), so any problems processing the cheque will cause additional delays to payment. I have heard from AJ Bell that the problem is specifically with delays at Bank of America and have no reason to doubt this.
Therefore, I'm taking no further action other than contacting Somero Enterprises Inc (LON:SOM) to suggest they maybe use electronic transfers in future to prevent these delays. Hopefully, anyone else similarly effected will do likewise.
All the best, SI
For dividend lovers PayPoint (LON:PAY) announced its interim results this morning. Revenues up, profits marginally up. Cash generation very good. A small tickle on the interim dividend (+2%) plus a special interim announced. Making total interim dividend of 27.8p per share, which is circa 3.2% yield on today's share price, which is up by about 6% at the moment.
This is a business which is in transition to some extent, and is making new markets for its services in Romania. The perception is that UK energy cash payment changes will affects some of its payment services in the UK, and is causing it to look down the line to other add-on services for small stores, and expand its market reach. So, quite a lot of moving parts to this business. But the market has I guess got a query over how it will adapt fully from some of the changing service requirements of this market as a highly profitable presence in the small convenience store arena.
I am a holder
Hi Graham.
Ramsdens Holdings (LON:RFX)
Here is the data on when people book holidays acccording to the website www.statista.com
Cheers,
Ben
Thanks Ben! Very handy. The hive mind wins again. G
very helpful, thanks
Morning all! I've done a deal with Graham, whereby he's agreed to look at reader requested Ramsdens Holdings (LON:RFX) from yesterday, and in return I'll do a review of a stock I mentioned at Mello as looking potentially interesting, the car supermarket Motorpoint. So here goes;
Motorpoint (LON:MOTR)
Share price: 216.5p
No. shares: 97.2m
Market cap: £210.4m
Interim results
"Motorpoint, the largest independent vehicle retailer in the UK, today announces its unaudited interim results for the six months ended 30 September 2018 (FY19 H1)."
The KPIs table below looks pretty good, at a time when many other car dealers are reporting reduced profits. That's because Motorpoint has a different business model. It's not a franchised dealer of new cars, but instead sells nearly new secondhand cars, at keen prices.
There's not really a great deal to say about this.
There doesn't seem to be much H1/H2 seasonality, therefore the broker consensus of 19.4p for the full year ending 31 Mar 2019 looks reasonable. That gives a PER of 11.2 . This is a good bit higher than bombed out shares of more conventional car dealers, which are typically on a rating of about 6-8 times. The premium for Motorpoint makes sense to me, as it has a better & lower risk business model.
Outlook comments - the key bit says they're in line, but with loads of disclaimers for possible unknown Brexit-related upheaval;
Balance sheet - looks fine, no issues there. Note that inventories of vehicles are quite modest, as they're shifted fast, and there are borrowing facilities to part-finance inventories.
Also note that fixed assets are very modest. This is another advantage of the car supermarket business model - there's no need for fancy premises to promote brands for the manufacturers.
My opinion - this is an excellent business model, which I like a lot. Growth comes from new site openings, so it should be a good roll-out over time.
Stockopedia likes it too;
Having ST of the IC tip Ramsdens Holdings (LON:RFX) yesterday lunch time will have also helped them bounce back up in the afternoon.
re: RFX, good point! I hadn't realised. G
Good Morning Graham,
It appears the CEO of Ramsdens Holdings (LON:RFX) Peter Kenyon agrees with you - He has just bought £80k worth of shares!
Thanks,
IG
Hi Graham
I refer to your comment about "staycations" and holidays being booked in advance in your analysis of Ramsdens Holdings (LON:RFX)
I agree there is a high percentage of people that do book their summer holidays during the preceding winter months. However, there is a proportion of holidays which are booked late, or almost last minute. On The Beach (LON:OTB) referred to the heatwave impacting bookings in the "lates" market and this resulted in a YoY decrease in Summer 2018 bookings made in May (although there was a pick up in June). Thomas Cook (LON:TCG) also referred to the heatwave impacting "lates" bookings.
https://www.onthebeachgroupplc.com/~/media/Files/O/On-The-Beach/investor-docs/results-and-presentations/preliminary-results-presentation-2018.pdf
See p.4/26
There may be a case to be made about the competition in this space not only from high street retailers that offer travel money, but also growing online competition.
Its an interesting point you make make. Looking at the stats on the CAA website, its seems that traveller numbers through UK airports is up (although with will include visitors to the UK too).
Like you say, I suspect part of this reduction in FX is down to companies like FairFX (LON:FFX) shifting the FX products online with improved benefits and convenience. That said there maybe a demographic argument in favour of Ramsdens Holdings (LON:RFX) here.
Re: AJ Bell
I ran some research on Trading Platforms amongst this SCVR community a year ago. Investors considering their IPO might find this interesting. Have a look here to see how they rated vs other platforms
https://www.stockopedia.com/content/quick-n-dirty-report-trading-platform-relative-satisfaction-249308/
Cheers
Francis
Thanks all, I'm on the case with RFX. G
another call for Ramsdens
I'm also interested in Ramsdens Holdings (LON:RFX) too, as a holder.
How about your take on Mycelx Technologies (LON:MYX) too please (which I don't hold)? A positive update, though perhaps rather speculative and subject to lumpy orders...
Scisys (LON:SSY) changed its name yesterday from Scisys plc to Scisys Group plc with the same ticker. following the legal relocation of its HQ to Ireland to avoid any Brexit problems. This seems to have caused A J Bell to declare that the shares are not tradable (which is a pity as I wanted to buy some more). Is this a general problem or limited to A J Bell?
This seems to have caused A J Bell to declare that the shares are not tradable (which is a pity as I wanted to buy some more). Is this a general problem or limited to A J Bell?
As you have found, AJ Bell are useless for anything slightly out of the ordinary. I've had more problems with them over the years than all the other brokers I've used put together. They have just lost a FOS complaint I made against them and have not met any of the compensation payment deadlines imposed by the Ombudsman. In addition I am still waiting for my Somero Enterprises Inc (LON:SOM) dividend in my SIPP (payment date 17/10) and was told yesterday it will not be in my account until around 8 weeks after the payment date. They have blamed their bank for not processing the USD cheque they (supposedly) sent to them. Sorry if I sound pissed off with them, it's because I am!
Good luck to long-term investors in their IPO. I am going to stag it :-)
All the best, Si
This seems to have caused A J Bell to declare that the shares are not tradable (which is a pity as I wanted to buy some more). Is this a general problem or limited to A J Bell?
Interesting (to me) as just this week I contacted AJ Bell about a missing Taptica International (LON:TAP) dividend. They replied two days later that the dividend had been received but it would take 2 to 3 weeks to process the cheque and credit to my account.
Strange as iDealing managed to credit dividends from same company a week ago.
Not sure that this inspires confidence in forthcoming AJ Bell IPO.
Genuine business concern, professionally put and worth a thumbs up
Interesting (to me) as just this week I contacted AJ Bell about a missing Taptica International (LON:TAP) dividend. They replied two days later that the dividend had been received but it would take 2 to 3 weeks to process the cheque and credit to my account.
Strange as iDealing managed to credit dividends from same company a week ago.
Hi Laughton,
I've complained about late payment of Somero Enterprises Inc (LON:SOM) dividends to AJ Bell for a few years now, including berating them on the phone, but this is a new low. 8 weeks is plainly ridiculous to cash a cheque and credit a dividend to an account. I'm sorry to hear that you have had the same problem. You'll also notice that when they eventually add the dividend to your account they back date it to make it look like it was paid in good time to cover their tracks. Shysters!!
I also hold Somero Enterprises Inc (LON:SOM) with HL and they always pay within 5 or 6 days. The problem with AJ Bell is that they do not credit accounts with the dividend as other brokers do. When you consider how much cash they have sitting in the bank according to the IPO prospectus, it's pretty clear they don't give a stuff about their customers or bother fixing problems that have been highlighted to them.
All the best, Si
Hi Si,
Thanks for the heads-up on AJ Bell. I think I will stick with Hargreaves Lansdown, who, despite causing some minor frustrations (mainly on their Iphone App, not the main site) seem to be continuously improving and despite not being the cheapest, the slight premium seems to be worth it for the better quality of the system and back-office processes (or a least this is what I have found).
Cheers.
Hi mmarkkj777
I have accounts with Hargreaves Lansdown (LON:HL.) and II (II use AJ Bell to adminster the SIPP facility and my Somero Enterprises Inc (LON:SOM) divi was credited on 17th October).
I trink that their are issues with all the online stockbrokers. I personally don't like the Hargreaves Lansdown (LON:HL.) web site, app, the adminsitration or the charges (to me they are not transparent) and when I can find time will transfer to II or A N Other.
My other problem with Hargreaves Lansdown (LON:HL.) is that with an Operating Margin of 60.5% and a net margin of 52% they are profiting at the expense of their clients or am I being naive?
Regards
Hi Purpleski
I take your point about the slightly higher costs, but I find them very transparent, with a PDF Transaction Note giving the dealing fee and any FX fee. I topped up on Amazon in my pension and for £2.5K in shares, it only cost me 30 odd quid including the FX and spread, which I think is reasonable (and I'm gradually reinvesting after pulling out in October with about 20% in the US).
I would counter your negative experience with some very positive views of AJ Bell. Their service has been excellent - particularly when transferring the trading account of an external pension from Alliance Trust Savings (acquirors of Stocktrade) who were incredibly incompetent at everything! The Youinvest platform is easy to use, the charges are very competitive for decent sized portfolios and there is plenty of choice in terms of investments available. The dealing desk personal are efficient and always as are the support staff when you need to contact them.
However, you are right about the situation with Somero Enterprises Inc (LON:SOM) as I have queried the delay and received much the same response. Apparently it is a combination of it being a $ cheque and the banks having a a significant backlog at the moment (probably down to retail investors getting out of the market before disaster really strikes!). It is worth noting that the previous dividend was pretty much paid within a week of the declared pay date. Knowing how bad banks are these days I can believe AJ Bell's 'excuse' but I have suggested to them via the web chat that they should look to sorting out the bank!
From an Investment perspective as I suggested in a new post yesterday the IPO looks to be set at a reasonable price relative to Hargreaves Lansdown (LON:HL.) and there is always an opportunity for a high growth, smaller business to take market share from the dominant player. I will be participating in the IPO in a relatively small way given the current market conditions. I hope you resolve your issues and don't need the Somero dividend monies for anything urgent!
I would counter your negative experience with some very positive views of AJ Bell. Their service has been excellent - particularly when transferring the trading account of an external pension from Alliance Trust Savings
Oh yes, they're very good at taking money in, just very reluctant to pay it out! :-)
But once AJ Bell have got you they have no problem changing their charging structure to their customers detriment knowing they are unable to escape without incurring their exorbitant exit charges. They even had the cheek to declare the changes to account charges were "revenue neutral". Talk about insulting peoples intelligence!!
Anyway, they lost a FOS case following a FCA enquiry into brokers not treating customers fairly. The Ombudsman told them to pay up within 21 days after they admitted they had lost, which took 2 years of them kicking and screaming, and they have still not made payment. I guess they will likely blame the bank again...
All the best, Si
Si,
If AJ Bell owe you more than £750, I suggest that you write to the company secretary telling them that if they do not pay within a week, you will consider that they cannot pay their debts as they fall due, and you will issue a winding up petition.
I would be very surprised if they do not pay you instantly.
Good luck!
Ricardo
However, you are right about the situation with Somero Enterprises Inc (LON:SOM) as I have queried the delay and received much the same response. Apparently it is a combination of it being a $ cheque and the banks having a a significant backlog at the moment (probably down to retail investors getting out of the market before disaster really strikes!).
I think this is a nonsense explanation. Selftrade managed to credit my dividend within 2-3 days of the payment date, and I know from discussions elsewhere that many other brokers have managed it too. I have not heard of any other broker taking anything like so long. They are being grossly inefficient and using maximum clearance times for non sterling cheques, which just about anyone can beat by a large margin, as an excuse.
Si, Thanks for the reply about A J Bell. I'm hoping for better, having finally managed to move my ISA from Barclays "Smart Investor" (where's the Advertising Standards Authority when you need them?) and agreed my second financial compensation from them for all the delays and incompetence.
The gem was their excuse for the excessive delay in getting the capital from a liquidation into my account - "we can't do things as quickly as other [stockbrokers] because we are a bank, not a broker".
If A J Bell prove a disappointment, where should I move next?
If A J Bell prove a disappointment, where should I move next?
Without any hesitation I would say Hargreaves Lansdown. There are some things I don't like about their platform, especially if you are looking to deal at the open, but sometimes paying that little bit more is really worth it for the excellent customer service.
All the best, Si
I have been very happy with Halifax Share Dealing - very cheap, and very user friendly.
Ricardo
IWEB (halifax) seem fine so far .
I am not sure if Interactive Investor are better/worse. But they have no exit fees so if you try them and don't like them you can always move for no cost. How financially sound Interactive is I am not sure.
Hello Andrew L. You make a good point in questioning how financially sound ii is as, being a private company, it is more difficult to monitor their financial state and they have been making acquisitions at a rapid rate. I only use brokers/platforms which are quoted as it is easier to tell if something significant is going wrong with their finances.
As I understand Interactive are loss making. You can look at the accounts at Companies House. Just do a search for them. AJ Bell publish their accounts on their website and have been robustly profitable for ages. Selftrade is owned by Equiniti which is profitable but has some debt.
it may be of concern to some that cash and assets held by II are covered, in the event of a claim against them, to no more than the cover provided by the Financial Services Compensation Scheme which is £50,000 per individual. II do not accept responsibility for any additional amounts over and above the cover provided by the FSCS.
My ii accounts were run by TD Waterhouse until they sold the operation off to ii.
So despite careful planning, the ownership of your broker can change very quickly.
What I would like to see is:
1 Direct electronic ownership of shares, just like in Singapore, where the system operates at very low cost. Nominee shareholdings are highly unsatisfactory, as ring fencing can be respected for years, then disregarded once the company is going under.
OR
2 The FCA should take action to ensure stocks can be moved in specie within ~24 hours. Then competition can become effective. This should be a priority for them.
Several years ago I was only using Halifax (ISA & trading), but then decided to spread my risk by using TD Direct (now ii) for new ISA contributions and AJ Bell for a SIPP. I've also opened an account in Singapore.
"If A J Bell prove a disappointment, where should I move next?"
Not James Hay. Anywhere except James Hay.
On the subject of broker platforms, I’ve used Charles Stanley, Charles Stanley (LON:CAY) , for several years and have been happy with the service although recognise there are cheaper deals out there. Pretty good on dividend payments handling (I hold Somero Enterprises Inc (LON:SOM) in an ISA and payments appear to go through pretty efficiently), corporate actions promptly dealt with and any other problems/issues readily tackled either by phone or a secure email message link. They also did quite a large “bed and ISA” transfer last year for me at negligible cost and with little fuss. Interested in other people’s experiences.
Gus.
Scisys (LON:SSY). Scisys. Everything OK with IWeb Share dealing.
On another front. Does anyone have a view whether Scisys will now be eligble for BPR and therefore OK for a IHT portfolio?
Thankyou.
KB.
I hold and like Scisys and added recently. No problem buying on Barclays or Charles Stanley. I find it is a good idea to have more than one broker in case of this type of situation or a problem so I use 3.
Looks OK to purchase on my AJ Bell platform - maybe sorted by today?
Good morning Graham,
It was great to finally meet you at Mello.
And another request for Ramsdens Holdings (LON:RFX) please.
Cheers
Francis
Great to meet you too, Francis. I hope my RFX comments will prove helpful. Cheers!
Morning Graham,
I know its not today's news, but if you do get chance it would be great to get your thoughts on Ramsdens Holdings (LON:RFX) results yesterday. A few of us were scratching our heads as to why it was down over 8% during the morning. By the close it was actually up. I think Liberum hosted an investor day and the Investors Chronicle chap Simon Thompson wrote on it also so the mood music coming after the RNS must have been positive I guess.
Cheers,
Paul
BCA interim.. INTERIM HIGHLIGHTS
· Revenue of £1,429.7m (2017: £1,171.6m)
· Adjusted EBITDA of £85.4m (2017: £75.8m), up 12.7%
· Operating profit of £50.6m (2017: £40.9m), stated after;
amortisation of acquired intangibles of £20.1m (2017: £20.0m); and
other non-recurring items of £0.7m (2017: £2.1m);
giving an adjusted operating profit of £71.4m (2017: £63.0m), up 13.3%
· Net debt of £264.0m (2017: £287.4m)
· Final dividend for the year ended 1 April 2018 of £47.5m paid in the period (2017: £35.5m) representing 5.95p per share (2017: 4.55p per share)
· Diluted earnings per share of 4.4p (2017: 3.2p). Adjusted diluted earnings per share of 6.4p (2017: 5.4p), up 18.5%
· Interim dividend increased 15.4% to 3.0p per share (2017: 2.6p) to be paid on 30 January 2019 for shares on the register on 14 December 2018
James Latham (LON:LTHM)
Good results this morning from this family run business. Operating profits up 10% and EPS up 32%, the latter increased by a £1m profit on property sales. Outlook positive but uncertainties with Brexit. Rock solid balance sheet.
The SP has drifted down quite considerably recently so hoping this will now change for this SNAPS selection.
Phil
My morning smallcap tweet:
Dignity (LON:DTY), Synectics (LON:SNX), Coral Products (LON:CRU), Realm Therapeutics (LON:RLM), Character (LON:CCT)
Dignity (DTY) CMA interim report on funeral mkt concludes mkt not working well enough. Will conduct a full Market Investigation. "Its initial work indicates problems with the market that have led to above inflation price rises for well over a decade - both for funeral director services and crematoria services. The scale of these price rises does not currently appear to be justified by cost increases or quality improvements."
Synectics (SNX) guides FY U/L pretax broadly in line with market expectations. A weak performance in the UK on-vehicle security sector has been offset by strong results from global Gaming security. Will make a £2m write-off, most of which will be non-cash.The pipeline of expected (note) new business is somewhat stronger than originally expected, so "increasingly confident of solid progress in the Group's results in the coming year."
Coral Products (CRU) H1 rev up 10%, U/L EPS 0.87p (0.23p). Div 0.25p (0.0p). 'Delighted' but don't know if it's a beat.
Realm Therapeutics (RLM) update on formal sale process. "From among the several non-binding proposals, the Company has selected a short list of potential transactions and has advanced these to deal negotiation and due diligence." More news in Q1 2019
Character Group (CCT) FY looks like a beat with rev £106.2m and U/L EPS 45p (52p) vs F/C 39p. FY div 23p (19p).
Morning All!
Just to let you know that I've updated yesterday's report further with new material on On The Beach (LON:OTB) .
This was because our reader called "Reacher" very helpfully posted a link in the comments section, to results presentation slides which OTB had published. These slides were a mine of useful additional detail, and answered my 2 main queries on the company.
Therefore I have incorporated this additional info into yesterday's report.
It's incredibly helpful when readers flag up results presentation material to me & Graham, so many thanks to Reacher. Also, I encourage all readers to flag up any future results presentation slides on any relevant company, in the comments to our articles.
Incidentally, I've emailed Rob at Research Tree, to suggest that RT includes links to results presentation slides on their platform, which would make it easier for us to pick up on this useful material when it's available.
Huge rally in the US last night. It seems to be because of comments about interest rates, that they're not going to rise much. I think it seems to be interest rates & bond yields that have been the main factor in driving the recent (global) market correction.
Best wishes, Paul.