SIF October review: Small wins and big losses leave me lagging the market (BON, MOTR, KLR, NXR, EZJ & BNC)

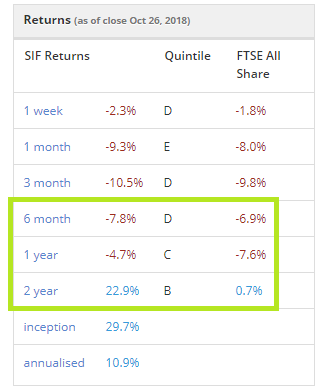
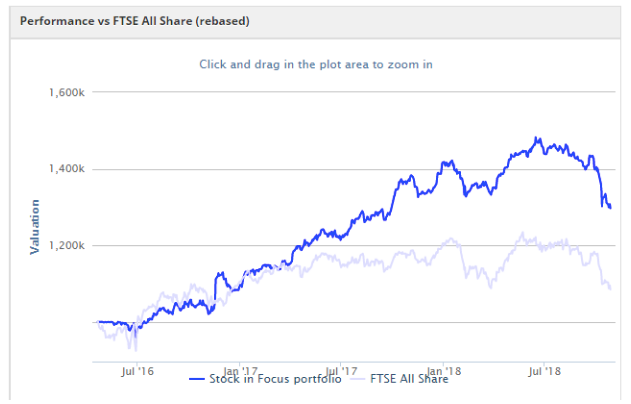
The recent market sell-off has hit by rules-based Stock in Focus (SIF) fantasy fund hard. Although SIF is still ahead of the market on a one and two-year view, over the last six months it’s fallen behind index-following rivals.
Unsurprisingly, this month’s correction has accounted for the majority of the portfolio’s losses.
What’s gone wrong? I think it’s fair to say that this sharp drop has highlighted the risk of investing in stocks whose valuations have been lifted by strong momentum. When momentum goes into reverse, the same businesses are suddenly given lower valuations.
Did I overpay for some stocks? Perhaps a few.
Are they bad companies? I don’t think so. In most cases I’d be happy to hold the stocks for a medium-term recovery if my trading rules allowed me to do so (they don’t - see here for an explanation).
I’ve bought more easyJet: A portion of my own real-money portfolio mirrors the SIF. By and large, I follow the same rules. But I do allow myself the occasional exception, and in October I bought more easyJet shares.
easyJet shares have fallen by about 25% over the last three months:
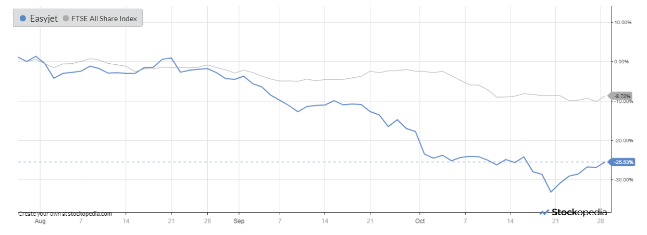
This decline appears to have been driven by three factors:
Fears of Brexit armageddon;
the possibility of a Ryanair-style profit warning;
the risk that sector profits will be hit by overcapacity and rising fuel prices.
Personally, I see easyJet as a leading operator that’s avoiding Ryanair’s largely self-inflicted problems. So I’ve bought more. Please note I haven’t averaged down the SIF fund’s holding. I’ve only increased my personal shareholding.
Averaging down: I’m aware that for momentum investors, averaging down is seen as the ultimate folly. You’re buying more shares when you’ve already been proved wrong.
On the other hand, for value investing I think it’s perfectly logical. You’re buying more when something good just got cheaper. That’s what I think is happening with easyJet, although obviously I could be wrong.
5 stocks under review
I’ve touched on the portfolio’s disappointing half-year performance already. In the remainder of this piece I’m going to look at some of the individual stocks behind this slump. No fewer than five stocks are up for review this month, after having been in SIF for nine months or more:
Ladieswear retailer Bonmarche Holdings (LSE: BON)
Used car supermarket Motorpoint (LSE: MOTR)
Spanish banking group Banco Santander (LSE: BNC)
Geotechnical engineering specialist Keller Group (LSE: KLR)
Bathroom products group Norcros (LSE: NXR)
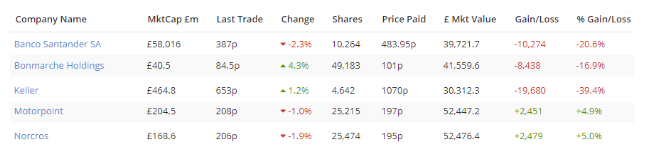
Here’s how each stock has performed so far during its time in the portfolio:
Bonmarche Holdings (LSE: BON)
Last month I decided to keep Bonmarche in the folio for another month, as it still passed my screening criteria. Unfortunately the firm issued a sales warning two days later, sending the shares down by 18% in one day.
Graham Neary covered the problems in his small-cap report that day, which you can read here. I share Graham’s view that management are in danger of appearing complacent, and may need a more proactive strategy to cut store costs and numbers.
The stock no longer pases my screening rules on several counts, so will be sold this week. A chunky 7.7% dividend yield has saved SIF from a bigger loss, but the outcome remains disappointing.
Verdict: Sell
Total return: -9.2pc
Motorpoint (LSE: MOTR)
For the second consecutive month, the UK’s largest retailer of used cars continues to qualify for the SIF screen. So it will remain in the portfolio for at least one more month.
Verdict: Hold
Total return to date: +8.2pc
Banco Santander (LSE: BNC)
The UK banking sector has suffered a big sell off this year. Despite a diverse international footprint, Spain’s Banco Santander has been hit hard. The shares are down by 25% so far in 2018.
Stockopedia’s algorithms have also turned hostile on the stock, awarding it a StockRank of 38 and a StockRank Style of Value Trap. This has left the Spanish bank as one of the worst-ranked stocks in its sector.
The bank’s latest results suggest to me that its performance hasn’t been all bad. An underlying return on tangible equity of 12.2% compares well to most of the big London-listed banks. A cost-to-income ratio of 47.5% is also better than most.
However, a Common Equity Tier 1 ratio (CET1) of 10.8% is lower than that of most rivals. This measure of surplus capital is also fairly close to the regulatory minimum, which I understand to be 9.5%.
Another concern is that bad debts are relatively high, at 3.92% of outstanding loans. Although this figure is falling, Lloyds only reported an impairment rate of 1.8% at the end of June 2018.
Santander’s falling share price has given the stock a negative relative strength value, so it no longer qualifies for my screen.
Verdict: Sell
Total return: -17.3pc
Keller (LSE: KLR)
I covered Keller’s profit warning in my piece two weeks ago (you can read it here). So I won’t spend much time on this today, except to admit that this is a big disappointment.
I think the lessons learned here are that even though this specialist groundworks contractor is a market leader, it’s still prone to the classic construction sector problems of slim margins and lumpy revenues.
A second point is that this month’s profit warning isn’t the first time Keller’s Asian business has fallen short of expectations. So I should probably have been more sceptical about management guidance for a return to profit in this region.
A trading update is due later in November. This may contain better news. But rising debt, falling profits and a share price slump mean that the stock no longer passes my screening tests and must leave the folio.
Verdict: Sell
Total return: -36.6pc
Norcros (LSE: NXR)
This maker of bathroom and kitchen fittings always seems cheap and always appears to be on the cusp of stronger growth. The firm’s recent H1 trading update was a good example. Reported revenue was +12.1%, but constant currency like-for-like revenue was -0.3%.
It seems that much of the firm’s growth in recent years has come from acquisitions. Improvements in margins and return on capital employed seen in 2016 haven’t been sustained:
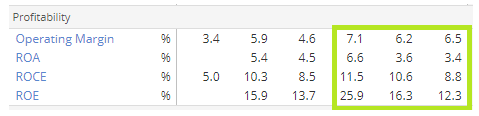
This still looks a good cheap business to me, if a little lacking in quality and competitive advantages. Stockopedia is cautiously optimistic, with a StockRank of 84 and a Neutral style.
However, rising debt, dilution from a recent share placing and falling margins are all concerns. They are also among the reasons why the stock’s Piotroski F-Score has fallen below my minimum of 6/9.
As a result, Norcros no longer qualifies for my screen and must be sold.
Verdict: Sell
Total return: +6.2pc
What next?
After this article has been published, I’ll sell both the fund’s virtual holdings and my personal holdings in the stocks I’ve marked as a sell.
I freely admit that the SIF folio is now in uncharted territory, as the market momentum we’ve enjoyed in recent years appears to be fading. Despite this, I won’t be making any changes to my trading rules or screening criteria just yet.
Next week, I hope to return to the acquisition trail with an affordable growth stock that isn’t about to issue a profit warning!
As always, I really appreciate your feedback and comments, which help to shape my thinking and coverage of the SIF fund.
Disclosure: Roland owns shares of Bonmarche Holdings, Banco Santander, Keller, Motorpoint, easyJet and Norcros.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

5 comments
Hi Roland.
More testing times for sure with the markets,a lot of variables to consider,with the onset of expected interest rate rises following in US lead.Cyclical s generally don't like rate rises apart from Banks!!. Easy to see with hindsight though!!.
Roland
We all know that investment is a long term exercise so I personally would remain phlegmatic about an underperformance on a 6 month basis
I would be interested to learn how much of the recent decline in SIF value is down to a general market re rating and how much is falling earnings if this statistic can be extracted. Probably mainly the former.
I do get the feel that the market is now moving away from momentum and towards value. The interesting question this raises for all of us is should we adapt our investment style to suit the conditions or stick with our chosen strategy. I personal wouldn't mix momentum and value factors in the same screen or strategy
Regards
There is a Guru screen for that. Very low drawdowns, so far. https://www.stockopedia.com/sc...
Hi merlotman,
Thanks for your comment. As it happens, we can see how the folio's earnings growth has deteriorated versus the wider market. In one of my articles in June, I asked whether the portfolio had too much cyclical risk. I used Stockopedia's Folio analysis tool to provide a snapshot of certain valuation metrics:
June 2018
Here's how the same ratios look today:
October 2018
It seems that the folio has seen larger fall in forecast eps growth than the wider market. Also SIF's average P/E of 9.4 is 27% lower than in June. The market P/E of 12.2 is only about 17% lower than in June.
So my question in June -- does SIF carry too much cyclical risk -- is perhaps now being answered!
However, I think it's too soon to draw any meaningful conclusions.
Regarding value and momentum, my view is that including elements of both in a strategy can make sense. Essentially, you're looking for stocks that are cheap and expected to improve.
Regards,
Roland
Hi Roland,
The results are disappointing but as you say the Sif portfolio is in uncharted territory and you have allways told us you didn’t know how it would respond to a downturn.
I am sure you will adjust the Sif when you have time to study how it has been effected.
I recently copied the screen for the Sif P so that I could watch what was being added on a daily basis.
I also set up the same screen to include an Altman Z score of no less than 2.8 this appears to of reduced potential losses by approximately 30 to 40%it it also reduced the number of equity’s available from 11 to 8.
Hope this may be of some use.
Best Wishes