SIF Portfolio: Hogg Robinson and Banco Santander pass my tests

My first day back at work after Christmas finds me faced with another kind of temptation that could be bad for my (financial) health.
Corporate services group Hogg Robinson is currently the top-ranked eligible stock in my Stock in Focus screen. But after selling this £270m stock from the SIF portfolio last year, I ruled out further investments in companies with giant-sized pension deficits.
My reasoning was that these outsized liabilities seem likely to lead to an unpredictable outcome for shareholders. For example, in Hogg Robinson’s latest interim results, the firm reported a £21.7m reduction in its pension deficit, to £243.5m. This was the result of a 0.1% increase in the discount rate used to calculate future liabilities and “and update of membership data” following the latest triennial valuation.
This valuation is ongoing and will include a discussion of “the appropriateness of the existing recovery plan”. The firm is currently making an extra cash contribution of around £7.5m each year. As Paul Scott pointed out, that’s similar to the amount paid out in dividends. It also represents around 17% of operating profit.
The bullish argument is that interest rates are now likely to rise, erasing the deficit and potentially triggering a re-rating of the stock. On the other hand, the pension trustees could decide that the company must increase its deficit reduction payments. This chart from last year’s results has made me more concerned about this risk:
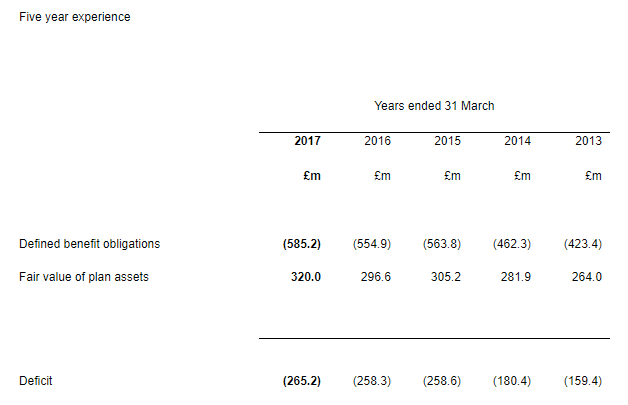
This shows that the fair value of the plan’s assets rose by 21% to £320m over the five-year period (a strong bull market for almost all asset classes).
However, high bond yields and ultra-low interest rates caused the value of the firm’s obligations to rise by 38% to £585m over the same period. As a result, the deficit increased by 66% to £265.2m.
---
*This section updated 8 Jan 2018. I had mistakenly compared asset value data for the group's pension schemes with those of the UK-only scheme.
The situation improved somewhat during H1 of the current year. Group-wide deficits fell by £21.7m to £243.5m. The main factor behind this was an improvement in the condition of the UK scheme, where obligations fell and asset values rose slightly:
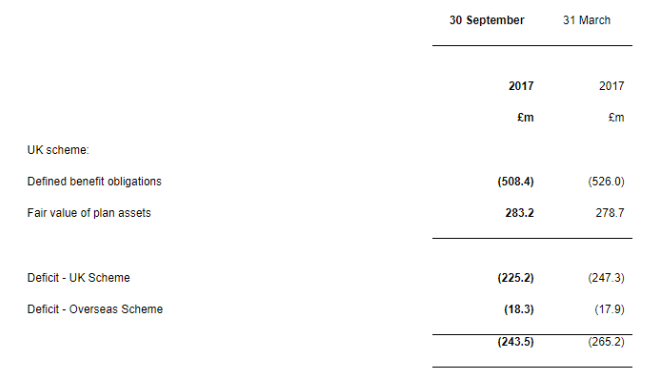
This improvement is encouraging. But it still seems concerning to me that the UK scheme's obligations of £508m are nearly twice as large as its assets. These obligations are also nearly twice the size of Hogg Robinson’s £270m market cap.
The gap between assets and obligations may continue to close. Or it may not. I can't see any reliable way of judging how likely it is that the deficit will disappear, without Hogg Robinson needing to inject funds above and beyond its existing deficit reduction payments.
---
It seems to me that the firm’s shares could become a leveraged play on its changing pension deficit. Given this, I view this as a special situation and thus outside the scope of the SIF portfolio.
Some genuine overseas exposure
My experiment last year with dual-listed Russian stocks delivered mixed results. For now I’m inclined to stay away from this market, but I’ve not ruled out further investments in dual-listed firms.
This week I’m considering a Western European stock with a long-standing London listing and a strong reputation. Banco Santander is the eurozone’s largest bank, with a market cap of €95bn. If it was a FTSE 100 stock, it would be the sixth largest in the index, after Shell, HSBC, Unilever, BAT and BP.
Like Lloyds, this Spanish group focuses on traditional retail banking. Santander is a familiar name on UK high streets, but the Spanish bank offers much greater geographical diversity than its domestic rival.
The group reported an underlying attributable profit of €5.1bn for the first nine months of 2017. UK operations were responsible for 16% of this figure, while Santander’s Spanish home market accounted for a further 15%. But it’s Central and South America that really move the needle, accounting for 43% of profit:
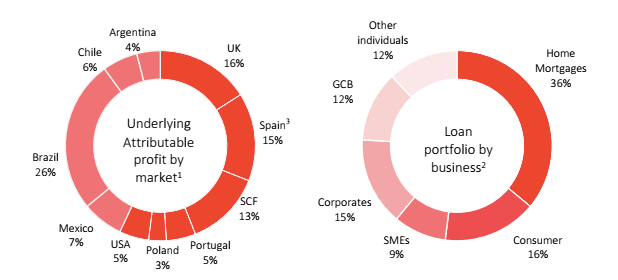
Banco Santander’s underlying profit and business segments for the first nine months of 2017
Sizeable businesses in the USA and Portugal are also worth noting. Overall, I believe Santander’s overseas banking businesses have the potential to provide genuine diversification for the SIF portfolio.
What do the StockRanks say?
My screening results are sorted by StockRank, but this ranking isn’t used in the screening rules. Santander is one of a minority of qualifying stocks which don’t have a particularly high StockRank:
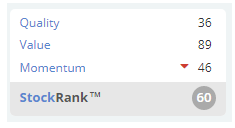
However, my reading of the group’s style ratings is more favourable:
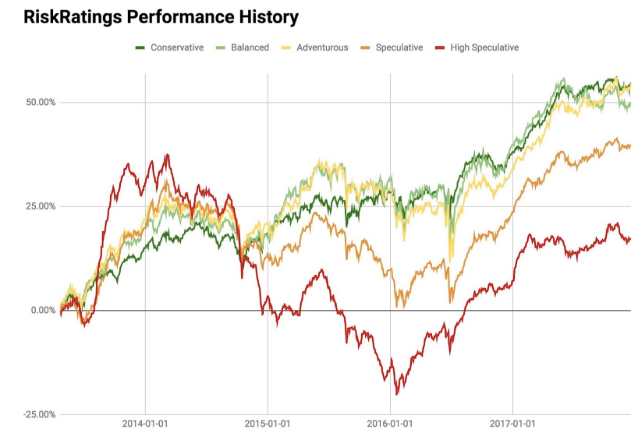
The StockRank Style of Neutral sits midway between last year’s winning and losing styles. But the RiskRating of Adventurous is more positive. I’ve borrowed this chart from Ben Hobson’s article last week. It shows how stocks with an Adventurous level of volatility have collectively performed strongly over the last few years:
Are bad debts a risk?
One thing I should point out is that despite its diversity, Santander does have a relatively high level of bad debts. The bank’s non-performing loan ratio fell by 1.13% to 4.24% during the third quarter of last year. In contrast, Lloyds said that 1.7% of its outstanding loan book was impaired at the end of September.
Santander’s progress would have been stronger had it not been for last year’s acquisition of Spain’s Banco Popular. Prior to this, the NPL was 3.74%. The bank says that excluding Popular, NPL would have been 3.51% at the end of Q3 2017.
This impairment level may seem high, but it hasn’t prevented the group maintaining a respectable level of profitability. Return on tangible equity was 11.8% over the 12 months to 30 September, compared to a Q3 figure of 10.8% for UK rival Lloyds.
Given this strong underlying profitability, I’m comfortable with Santander’s bad debt levels.
Fair value, improving outlook
The group’s shares trade on 12 times trailing earnings, with a trailing yield of around 3.3%. Measured against assets, the current share price of 485p represents a 30% premium to Santander’s tangible book value of €4.20 (c. 373p).
This valuation seems fair to me, given that consensus forecasts suggest eps growth of 5.5% for 2017 and of 12.6% for 2018. Dividend growth is expected to be stronger still, with an increase of 26% pencilled in for 2017, and of 8% for 2018.
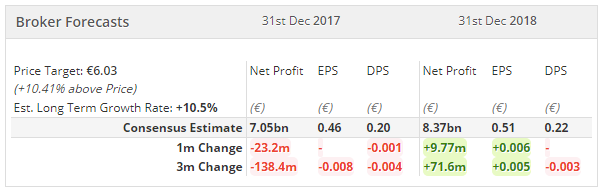
Broker consensus is fairly neutral on this stock, but my view is that the group’s current valuation and geographical diversity could prove a good starting point for a profitable investment.
My decision
I plan to add Banco Santander’s London-listed shares to the SIF Portfolio this week. I’ll also buy them for my own portfolio, after this article has been published.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

8 comments
"November’s interims showed a slight fall in the deficit, but also revealed a substantial drop in the fair value of the plan assets". The fair value of the UK scheme assets rose from 278.7mio to 283.2mio as your table immediately below this statement shows. Am I missing something?
Hi dealtn,
Thank you for pointing this out. You're not missing anything, it's my error.
I mistakenly compared the value of the global schemes' assets with those of the UK scheme only.
You are correct to say that the UK deficit fell during H1 as a result of an increase in the UK scheme's asset values.
I've amended the article to indicate the error and correct my commentary.
Regards,
Roland
On pensions, I am confused in general about accounting treatment (and I'm an accountant)
Basically pension fund has liabilities with average life of say 40 years (retiree life span), but assets typically only have a life of 30 years (Eg 30yr treasury).
To that end, in simple Math, should the asset cash flow not be 1.25, as you would reinvest maturity proceeds?
I am sure people much smarter than me have looked at this, but would love an actuary to explain how a mismatch between maturity of assets and liabilities is dealt with for the actuarial valuation.
When I say simple Math, I mean my simple brain!
@sharmvr
An average retiree lifespan of 40 years seems high. Obviously I'm hoping to get to 100+, but assuming most people will get there or beyond seems excessive?
Average UK life expectancy is around 80 for males and 83 for females. Assuming retirement at 65 that would give 15 to 18 years of collecting the pension. Some people do retire earlier, but usually the benefits are reduced pro-rata. I might add a few of years of life expectancy to the averages as I have read that having a decent pension helps prolong lifespan.
Perhaps your bank scheme is more generous than most.
Of all the banks this one seems best. People have been depositing £20k at 1.5% interest. The bank must be able to do a lot better than that. The rate was previously 3%. Lending rates have not dropped much since. High lending risk seems to pay off. Higher rates seem to outweigh defaults. Banks are pretty opaque though. Some are run pretty badly.
Hi Khris,
I agree that banks' finances can be opaque. That's one reason why I didn't try to delve too deeply into the detail of the Banco Santander SA (LON:BNC) numbers.
But I think it's notable that Santander has largely stayed out of trouble (regulatory and financial) throughout the period since the financial crisis. That's an endorsement of management quality and operational discipline, in my opinion.
Regards,
Roland
My view having worked in banking (not a banker) for most of my working life is that banks are not well managed, especially the investment variety.
To that end, I consider if p/b on or around 1 (pcf might be an exception - still looking at it).
Santander is interesting though.
My view (which I expect is someone smarter's view as well):
Banks are effectively a leveraged bet on the economy and Santander is a leveraged bet on South America.
Personally, I ruled out as I am not comfortable with the risk of South America.
Argentina defaults every 20 years, yet they issued a 100 yr bond @ sub 8%.
That said, if UK investor wants a levered bet on the emeging/emerged economy would do well to hold Standard Chartered (LON:STAN), HSBC Holdings (LON:HSBA) and Banco Santander SA (LON:BNC).
Probably Stan if you want emerging/frontier exposure.
Please note this is not based on detailed analysis but rather anecdotal from conversations with colleagues/friends at various banks