Small Cap Value Report (24 May 2017) - SAL, TRAK, KWS, LRM, HRG, ACT, BOWL, HSS

Note: Paul updated Tuesday's report to include Topps Tiles (LON:TPT), Epwin (LON:EPWN) and eg Solutions (LON:EGS) (in addition to accesso Technology (LON:ACSO), Indigovision (LON:IND) and £CALL). You can read it here.
First section - by Paul Scott.
Thanks to Graham for taking the strain today. I should be getting the keys to my new flat today, then the removal men are shifting all my stuff on Friday. Therefore I’m being considerably distracted from the markets this week.
It’s a fairly modest place on the south coast. These days I like to keep living costs low, as experience has taught me that relying on the markets for income is too precarious. It’s best to build up some other forms of income, to cover all household outgoings. That takes the pressure off, allowing an investor to even sit on the sidelines in cash, if a bear market starts.
I tend to look at portfolio gains as being a bonus. Obviously the last 2 years have been remarkably good, but it won’t be like that forever. So it’s always best to plan for a downturn.
Anyway, on to today’s news. Here are a few very brief comments;
Spaceandpeople (LON:SAL) – contract win announced. I see that, as usual, the share price moved the day before the announcement. So our insider dealer at SAL is alive & well. Whilst I had a historic attachment to this business, I now think it lacks the potential to really scale up. Therefore the upside is probably quite limited. As the CEO always points out, contract wins are a matter of “snakes & ladders”. So the company tends to RNS contract wins, but is less keen to announce contract losses! That’s true of many companies. It’s got momentum for now, so that might provide some liquidity for long-suffering shareholders to exit, if they wish to.
Trakm8 Holdings (LON:TRAK) (in which I hold a long position) – has also announced a contract win, which sounds potentially significant. “Additional visibility for our expectations for this financial year & beyond”. The company seems to be gradually recovering from previous mishaps. Although we’ll have to wait and see what the next set of numbers look like.
Keywords Studios (LON:KWS) – Note that Directors have taken advantage of the stellar share price gains to bank £37m from selling a sizeable chunk of their holdings. Make of that what you will, I’m just flagging it up.
Lombard Risk Management (LON:LRM) – results for the year ended 31 Mar 2017 are out today. This share has been heavily promoted recently, on the back on contract wins. Revenues are up strongly – a 45% increase to £34.3m. However, if you take a closer look at the cashflow statement in particular, things are far from rosy. The company capitalised a staggering £7.5m into intangibles. That must be a hefty chunk of its total payroll. Stripping out capitalisation, the company made a £5.6m loss for the year.
Based on results to date, I seriously question whether this is a viable business. From the numbers to date, I think not. It’s always jam tomorrow. Also, bear in mind that a lot of its impressive-sounding contracts are actually quite small. I don’t rate this share at all.
Hogg Robinson (LON:HRG) – good results are out today. However, the elephant in the room is the £265m pension deficit. This is up £6.9m. However, there’s been some clever accounting involved in massaging the pension deficit down. Liabilities rose by a staggering £96.7m, due to the impact of lower interest rates. However, the company then agreed with the trustees, to jiggle around the demographic assumptions, in order to bring the deficit down again.
Note from the cashflow statement that the company is making £7.3m p.a. over-payments into the pension fund. That is similar to the amount paid to shareholders in divis, of £8.3m (giving a yield of 4%). So this is a good example of how pension deficits consume real cash, and restrict the divis that can be paid.
It looks quite a nice business, but I wouldn’t be interested in a company with such a problem pension deficit, and therefore overall a car crash balance sheet.
Actual Experience (LON:ACT) – interim results from this jam tomorrow tech company. £135m market cap. Revenues fell by more than half to £193k in H1. So practically nothing, basically. It incurred a loss in the 6m of £3.8m. The cash position is healthy, at £22.6m. A shrewd friend tells me that this company is the business, in terms of its services (which help diagnose problems in IT systems, or websites, something like that). However, there is absolutely no financial performance to back that up, yet.
I steer clear of jam tomorrow shares, as they nearly all go wrong in one way or another. So why take the risk that you can find the needle in the haystack?
Second section - by Graham Neary
Paul's prodigious output continues, even when he's moving house!
But I'll add a few more comments now:
Hollywood Bowl (LON:BOWL)
- Share price: 175p (+5%)
- No. shares: 150 million
- Market cap: £262 million
A reader has previously suggested I covered this, and today is the perfect opportunity with the H1 results.
Hollywood Bowl is a bowling operator with 56 venues, claiming to be the larger ten-pin bowling operator in the UK.
This announcement strikes a very upbeat tone: revenues are up 8%, operating profit up 18.5%, and there is a pledge to review shareholder returns given the strong balance sheet and cash generation.
Two new openings are due each year for the next three years, all six "legally committed" with their respective landlords. The O2 in London is among the venues set to open later this year.
Like-for-like
LfL sales were up by a much more modest 1.2% over the period, although the company claims 2% of growth was lost due to missing out on this Easter break (so H2 should logically benefit by a similar amount).
The operating margin increases from 20% to 22%, implying some operating leverage from opening new stores, even if LfL growth was unspectacular.
I note that the company refers to "challenging weather" in H1, due to "unprecedented record dry months" - the exact opposite situation for most public-facing companies!
But that being the case, perhaps there is a case to be made that LfL sales were held back, and next winter could see a much stronger result.
Cash flow
Hollywood Bowl provides an incredibly useful breakdown: it gives both maintenance and expansionary capex! It would be great if many more companies did this. This way, we can see how much capex was unavoidable to stand still, and how much of it should lead to future growth.
It's still worth taking the time to verify this as much as possible, but the company reckons that adjusted operating cash flow was £14.6 million, which was then reduced by expansionary capex of £3.3 million, exceptionals of £3.2 million, and interest and dividends.
Expansionary capex includes refurbishment costs, so a sceptic might wonder if some of that was really expansionary, or if it was necessary to stand still.
Some of the exceptionals might be questionable, too, in terms of how exceptional they really are.
So I'm glad the company has made an effort to show us what the underlying operational cash flow is, but of course I'd still want to put it under the microscope!
My opinion
Overall, looks an interesting proposition to me, and perhaps not too expensive.
It has only been listed since September, so might still be flying under the radar for some private investors.
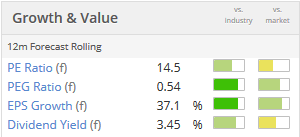
The StockRank only gives it a score of 40, so nothing spectacular on that front.
It has a decent dividend yield which usually doesn't hurt, and management are strongly hinting that it could increase, or rewards could be improved in some other way:
HSS Hire (LON:HSS)
- Share price: 61.5p (-1%)
- No. shares: 170 million
- Market cap: £105 million
Not a lot to shout about from this equipment hire group, where I am probably not alone in continuing to sound the alarm bells:
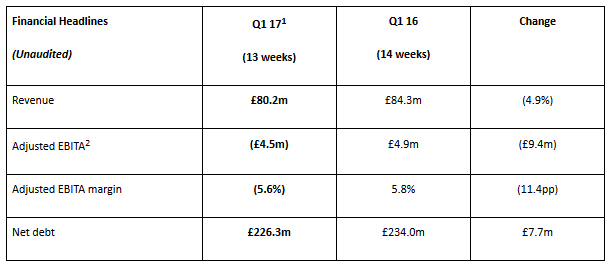
The company points out that there was one less trading week this quarter, and many branches were closed in a restructuring program over the last six months. So a reduction in revenue should have been expected - and so underlying revenue is reported as "flat" year-on-year.
Cash headroom is £30 million taking into account the current facilities.
A new CEO has been appointed, joining in a week, taking over the freshly restructured business. So it's tempting to think that trading could improve.
As a reminder, however, HSS had £136 million of 6.75% Senior Secured Notes outstanding at December. The rest of the debt is in the form of an RCF charging 2.25% over LIBOR. The bonds mature in 2019, which is also when the existing RCF matures.
At a 5.3% weighted average interest rate, you get a £12 million annual interest bill.
Reached that kind of EBIT on a consistent basis looks challenging, and with the note maturity date gradually approaching, I think the equity holders are in a precarious position
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

33 comments
Hi Graham, All
Mortgage Advice Bureau Holdings gave an update at their AGM today basically saying that the outlook is in-line with expectations. However, the market appears to have been anticipating an exceed expectations statement as the stock is down 4.9% today.
Given this and the massive sell off in Revolution Bars (LON:RBG), is this an indicator that everyone is starting to get very twitchy?
I sold out of RBG but still hold MAB1 and continue to do so as it looks like a very solid business,
Ditto with Softcat today Graham I'm struggling to find any value and most of my 4-5 faves all seem to have topped out and off 5-10% even the lovely Somero seems to have stalled.
Re Softcat (LON:SCT) I was surprised how much it went up so I think just some profit taking, in line is not good enough for some investors. You won't find much value as the market has gone up so much since Brexit. But does value matter, value investing does not seem to have worked so well for 2 years or so compared to momentum.
Yes there does seem to have been a lull recently but some of mine are still going up such as Zytronic (LON:ZYT), Burford Capital (LON:BUR), Fevertree Drinks (LON:FEVR), Patisserie Holdings (LON:CAKE), G4M. I do hold Somero Enterprises Inc (LON:SOM) as well, down to 50MA think this is due the concerns in the US re Trump.
I think the movement in MAB is more likely related to the HMRC figures released yesterday (https://www.gov.uk/government/uploads/system/uploads/attachment_data/file/614562/UK_Tables_May_2017__cir_.pdf). "For April 2017 the number of non-adjusted residential transactions was about 22.5% lower compared with March 2017. The number of non-adjusted residential transactions was 12.8% higher than in April 2016." How unusual for newspapers to be focusing on the first sentence and not the second. For comparison, the sequential decline in housing transactions in 2016 from Mar to Apr was 57%.
Jan-Apr 2016 was 420.3k transactions and Jan-Apr 2017 was 354.3k or -15.7% (page 6). If you look at Jan, Feb and Apr (ie exclude Mar) then it was 248.9k transactions in 2016 and 247.2k in 2017. Not sure where that leaves us. Lots of volatility around Mar in both years.
CML mortgage lending figures should be out tomorrow which will provide another data point. I expect very little progress for MAB in 1H.
Thanks bestace
Thanks for the coverage on BOWL Graham following my request, very much appreciated
It looks like one of the pensions changes at Hogg Robinson (LON:HRG) was to update their longevity assumptions to use the CMI_2016 tables rather than the CMI_2013 tables used last year. Normally the expected lifespan of pensioners increases each year by small amounts - tenths of a year maybe, but the adoption of the new longevity tables has led to a big drop in assumed life expectancy this time round for HRG:
The fact that longevity assumptions are falling is not a surprise - the FT covered the effect of the new longevity tables earlier this month (to get around the paywall, Google 'Pension providers find a bright side of death'), but it's interesting to see the effect on a real pension scheme.
In the case of Hogg Robinson (LON:HRG) the effect is a reduction in pension liabilities of just over 3%, which amounts to a £19m gain. 3% may not sound like much, but when deficits are calculated as the difference between two very large numbers, a 3% reduction in pension liabilities could have a material effect on a pension deficit.
The latest CMI tables were only released at the end of March, so there may be some read across to other companies with final salary pension schemes who will no doubt be updating their longevity assumptions in due course.
bestace
My understanding is that the positive trend in mortality improvement is still true, except that the improvement rate is not as high as that assumed in previous CMI studies.
Happy to be corrected. I also believe that this trend of slowing down improvement in mortality is apparent in the US.
That's what the CMI press release implies, but the FT article quotes the actual numbers:
It may be a blip in a longer term trend, but that's now two years in a row and even if it is a blip, there will be a lot of Finance Directors who will be happy to take advantage in the short term given the impact on pension deficits.
Triennial reviews are carried out by actuaries and they set the assumptions. So the key question is will the actuaries reflect this apparent slowdown in improvement, or will they be ultra caution and wait a bit more?
Hogg Robinson (LON:HRG) took advantage of the change for their IAS19 valuation, with the triennial valuation to follow:
For the IAS19 valuation, it's ultimately up to the company management to decide on the assumptions and I'm not sure an actuary/auditor would be able to object if the management pushes to use the updated longevity tables.
My memory of the FT article is that people on final salary pensions are still benefiting from improving lifespans and that the negative change is concentrated on those not lucky enough to have that benefit.
Which clearly raises questions about applying the new figures to calculating the liabilities of final salary schemes.
Hi all
Can anyone suggest what might be happening with Avingtrans (LON:AVG) (Avingtrans).
I see that throughout most of May, NPlus Singer Capital Markets Ltd are noted as doing share transactions under Rule 8.5. Does anyone know what that might mean?
Disclosure I hold.
Regards
Howard
Its a takeover situation. You usually see this with the big investment banks when a large cap is involved.
I wouldnt worry about it. When I take a position in my momentum portfolio one of the things I look for when doing my quick sanity check is any RNS' with the same headings, as that tells me M&A is involved.
http://www.stockopedia.com/share-prices/avingtrans-LON:AVG/news/rns/170428avg6219d.htm/?title=extension-to-deadline-under-rule26c-of-the-code
Hi steviej
Many thanks for the rapid response and the information.
Regards
Howard
http://www.thetakeoverpanel.org.uk/wp-content/uploads/2008/11/code.pdf?v=2May2017
P120 is the one, it is a technical reporting requirement when a takeover is in play , no great significance
Hi rhomboid1
Wow that's some document. Many thanks for your clarification.
Regards
Howard
Hollywood Bowl...strikes a very upbeat tone. Like what you did there!! I visited this place a few times for workplace team building etc. It was a dump and needed a lot of investment. Clearly they were saving on capex pre-listing. My guess is they will need to spend quite a bit in the future. That said, could be a one off so worth investors doing a bit of field research.
HI Graham, I was wondering what your's and Paul's thoughts are on Eve Sleep Plc (sorry, ticker didn't work)? It's online only and new to the market, selling mattresses and pillows amongst other things. It looks like another online disruptor, taking a product which is traditionally only brought in a shop, and selling it online with all the cost efficiencies that go with an e-commerce business. I particularly like the fact that they can roll-up the mattresses so that hey are cheaper to ship and easier to lug up the stairs to the bedroom!
Look forward to any thoughts you have and thanks to both you and Paul for such enjoyable lunchtime reading.
eve Sleep (LON:EVE). Can you roll them up? I have read they are heavy and you need 2 people to lift them. There are quite a few comments about this company on another post a few days ago here: http://www.stockopedia.com/con...
They do not make the mattresses themselves, anyone can do this, there are also similar companies doing this already. Simba is one, gets very good reviews, similar prices.
Thanks Herbie - missed this!
I've bought several memory foam mattresses online in recent years. They arrive rolled up tight in a bale, with a strong plastic bag around it. So they're fairly easy to lug around indoors, or to put in your car.
So I don't really understand what eve Sleep (LON:EVE) is doing that's unique?
Also, I paid about £600 for a memory foam mattress online, about 4 years ago.
I bought another, similar, but slightly thinner one online about 6 months ago for just £150.
So price deflation is another issue - maybe that's why they're floating on the stock market now?
PP.
Hi Paul,
I can't see anything unique and looking online there seems to quite a few other companies that are doing similar mattresses, just seen Bruno, Emma and HydeandSleep as well as Simba and Casper I already knew about. Also it seems you can order direct from the manufacturer. In reviews Eve rarely seem to come out on top. Here is an article: http://www.independent.co.uk/extras/indybest/house-garden/best-mattress-side-sleeper-kids-review-tempur-a6950396.html
I'm amazed how many mattresses there are, seems a crowded market. If Eve had something unique I think it maybe be a good investment but I'm struggling to see the potential. Anyway I'm sticking with my Warren Evans for a few years yet, it's very comfortable.
IKEA sell their mattresses rolled up. The Morgedal is a Which best buy at £165 for a UK double.
I'm not sure I would pay more for the EVE "disruptor" product or that their customers are the ones seeing the benefit of their lower online costs.
It typically takes 72 hours for rolled-up mattresses to unroll fully.
Hi Graham
I second your thoughts on Scapa (LON:SCPA) please!
Cheers
Good luck with the house move Paul, hope you have happy times in your new gaff!
Interesting that you mention keeping the expenses low: Financial independence bloggers often mention the need to pay for only the stuff you find adds value to you life and not give in to spending to assuage our status anxieties.
It's a lesson I only learned recently!
Once again thanks for the service you and Graham provide.
Hi Graham - SCPA results yesterday were excellent. Worth looking at ?
Any thoughts on Softcat appreciated Graham a private investor favourite seems market was expecting more than "in line with managements expectations"
Thanks
Hi clarea, sorry I'm not supposed to be going above £400 million without a really good reason and there are a few other bits for me to cover today. Hope you understand!
Graham
No worries Graham I second everyone on here thanks for the input you and Paul put in and the knowledge you are both willing to share .
Hi Graham - any chance of commenting on the interims of Hollywood Bowl (BOWL) please!
Done!
Not sure if you were the person who was asking me to cover it before but I'm glad I've finally done it!!
Cheers
Graham
Re. Spaceandpeople (LON:SAL) I have just added another adage to my list of stock market do's and don'ts .
- Stay clear of 'snakes and ladders' stocks. Good for punts but bad as investments