Sigma Pharmaceutical: Taking its medicine
This article was written by regular contributor Anton Crabbe. You can read his bio here
Sigma Healthcare (ASX:SIG) are a full line pharmaceutical wholesaler and distributor. They also have a network of independent and franchised pharmacies and healthcare providers across Australia.
SIG have experienced changes over the past decade however recently have been focused on improving their business operationions through IT upgrades, increased warehousing capacity, brand consolidation, and sale of non-core assets.
However when coupled with COVID supply issues, this has led to business disruptions, loss of market share and unfortunately resulted in a net loss in FY22. That considered, it is starting to look like the restructure and streamlining strategy is bearing fruit in FY23, with the company reporting a small net income figure of $3.3m and paying a final dividend of 0.5 cents, fully franked.
As mentioned, FY23 was a busy year for SIG, with the upgrade of their distribution centres and IT systems being completed. Further, they commenced the amalgamation of Amcal and Guardian pharmacy brands, ceased their loss making Cura operations and sold their Wholelife hospitals for $44m.
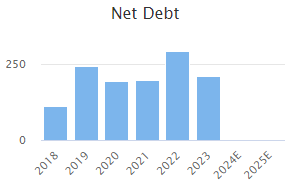
What was encouraging to see was that despite all this, SIG increased reported revenue by 6.2 per cent to $3.7B, whilst also improving margins and cash flow. Furthermore, they reduced Net Debt from the high figure six months ago, but it is still elevated. (more on that in a moment.)
Health, medical and hospital spending continue to increase. This is a huge market and has strong long-term tail winds driven by an aging population and changing health policies. Ideally, if the efficiencies and improvements SIG have recently made continue, SIG are in a prime position to capitalise on these strong sector tailwinds. Adding to this, SIG are planning to enter the higher margin ‘health, beauty and wellness’ product categories and increase their own label offering.
Stock Rank:
Since SIG released their annual FY23 report on 23rd March, their Quality and Value ranks rose on the back of the turnaround in business performance. But it looks like the Momentum rank has decreased more significantly despite a relatively stable price. This is on the back of the Analysts cutting their EPS targets for SIG for FY24 and FY25, with this factor contributing to the overall decrease in the StockRank.
Before their report

After their report


Deeper into Momentum:
Despite the drop in Momentum Rank, I still find this interesting, especially as SIG’s volume change indicator is up close to 150% in recent times.
Without knowing exactly why, the large number does tells us that the average volume of shares traded in the last 10-days is higher than the average volume of shares traded in the last 3-months, and when the short term price is doing well, this effectively means there are buyers in the market.
Further, this can indicate there is an increase in institutional activity and larger blocks of shares are being bought. This narrative ties into the recent increase in SIG’s share price and the speculation that their largest shareholder Home Consortium Ltd. (19%) might be considering a purchase and lease back of SIG’s distributions centres and properties.

Home Consortium Ltd was set up with the help of Chemist Warehouse and it is thought that this close relationship may help SIG in regaining the contract they lost in 2018 to supply some 400 Chemist Warehouse stores. Back in 2018, SIG’s share price fell 40% on the back of the expiry of this contract and it left a large hole in earnings. Given the increase in volume change, price and speculation around SIG, it is no surprise that they qualify for Value Momentum and 52-Week High momentum screens.
Financial Health:
As reported by SIG in their FY23 annual report, they reduced debt by $85m, increased sales and EBITDA, and most importantly net cash flow from operating activities was $142m up from negative $46.0m in FY22.
The improvement in cash was pleasing to see and has turned the company’s cash flow ratios positive.

SIG have indicated that their capex program has finished, and will return to normal levels of between $5m-10m moving forward and their planned dividend policy is to payout between 50-60% of reported net profits.
The improvement in business metrics has seen the Health score of the company reach 7, however despite this the Bankruptcy Risk is still high.Given their recent past issues, it’s not surprising that they have a poor Z-Score.
Investors will hope that a continued reduction in debt, alongside increases in sales, profits and margins will see the Z-score improve. As noted by SIG themselves, the job is only half done, and now that they have stabilised the business, the focus is on winning back and increasing market share, brand consolidation, and the introduction of higher margin categories and own label products.

Ownership
52% of SIG is owned by their top shareholders, with the largest holding of 19% belonging to Home Consortium Ltd. SIG have a free float of 741m shares, which is 73% of the 990m shares on issue. Indicating there is good liquidity for small DIY investors to get in and out of the stock.

Outlook
SIG have not provided sales or net profit guidance, but they did expect their strong operational performance to continue to improve as they implement their business strategy. They did provide EBIT guidance of $26.0m to $31.0m for FY24. Consensus estimates obviously don’t share as rosy a picture as what SIG is trying to portray, with the latest result seeing cuts to EPS expectations for both FY2024 and FY2025 and the general view is that the stock is a sell.
Conclusion:
Whether you are trading on Momentum or buying Quality, there is a lot to like from both sides here.
For me from a fundamental point of view, investors can take heart from the fact that the numbers are matching what management is saying and they are doing the right things by paying down debt and paying dividends. If this continues investors can expect the good things that happen with increased cash flow and profits (i.e. share buy-backs, increased dividends and a higher share price). But, despite the positive trajectory, SIG have noted the job is only half done and there is still a lot of work to do
Important Information: Stockopedia Ltd ABN 39 757 874 670 UK business registration number 0637267 (“Stockopedia”) is an Authorised Representative of Daylight Financial Group Pty Ltd ABN 77 633 984 773 (“DFGPL”) which is the holder of an Australian Financial Services Licence (AFS Licence No. 521404).
Information in this commentary is current as at date prepared unless otherwise stated. However, please bear in mind that investments can go up or down in value, and that past performance is not a reliable indicator of future performance. For more Important Information please refer to the Disclaimer section of this website.
This communication may contain general financial product advice. It has been prepared without taking into account your personal circumstances, and you should therefore consider its appropriateness in light of your objectives, financial circumstances and needs before acting on it..
If our advice relates to the acquisition or possible acquisition of a particular financial product, you should obtain a copy of and consider the Product Disclosure Statement (PDS) before making any decision.
The author holds interests in the following stocks mentioned in this article: SIG . This position can and will change at any time without notice.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
2 comments
Key Takeaways From 2023 AGM Held on 17th May:
SIG is in a very interesting space at the moment.
Wesfarmers Health is charging along acquiring API and now SLA, they have set up new offices in Melbourne over 2 levels of a new building (they are taking this seriously).
SIG owns AMCAL chemist
EBO own Terry White Pharmacy
API own Priceline
The gorilla in the room is Chemist Warehouse who were rumoured in 2021 to be preparing to IPO, this has not happened.
SIG lost he Chemist Warehouse distribution contract to EBO. In the mean time SIG seems to be sorting themselves out and have commissioned a NEW distribution facility.
Since 2018 SIG has a resistance level at the current share price (+/- 70c), it is trying to break out now, some good news may kick it along.
INTERESTING TIMES