Similar Small Cap Silliness - more stocks looking too cheap today

In September 2023, I wrote a follow-up to my Midcap Madness article called Small Cap Silliness. The theory was that outflows from the UK markets that had made many midcap stocks look good value would extend to smaller companies. Again, I used a screen with some very simple value criteria, but this time, I focused on the market cap range between £30m and £300m.
The other criteria were:
Price-Earnings Ratio Forecast 1y < 10
I wanted companies that are forecast to remain cheap.
Dividend Yield Rolling 1yr > 5%
While this wasn't designed to be an income screen, a large dividend yield is a sign of companies where the price has declined, but the company retains its dividend payout. This may indicate that management believes the company's future is not as bad as the market has priced.
Stockopedia QV Rank > 70
This was a sense check that I was getting stocks with reasonable Quality and Value.
Industry Group excludes "Collective Investments"
I wanted to look for trading businesses, so I excluded funds and fund-like stocks.
The original screen had 28 results, and I picked ten stocks that I thought had interesting value characteristics at the time.
Were they just too cheap?
Here's the performance of the full list of 28 stocks:
Price at: |
13/9/23 |
3/2/25 |
Price Return |
AA4 |
46.41 |
62.89 |
35.5% |
ALU |
162.5 |
282.5 |
73.8% |
ARBB |
955 |
905 |
-5.2% |
BILN |
350 |
480.2 |
37.2% |
BRCK |
46.5 |
56.02 |
20.5% |
DUKE |
33 |
28.95 |
-12.3% |
ECEL |
111 |
145 |
30.6% |
EPWN |
69 |
90.1 |
30.6% |
HAT |
406 |
339 |
-16.5% |
IPF |
124.5 |
128 |
2.8% |
JIM |
117.5 |
46.45 |
-60.5% |
KGH |
88 |
118.47 |
34.6% |
NXR |
149 |
232 |
55.7% |
PAF |
14 |
40.2 |
187.1% |
PPHC |
130.5 |
134 |
2.7% |
RCH |
73.5 |
85.9 |
16.9% |
SDY |
34.9 |
20.22 |
-42.1% |
SFR |
60.4 |
48.8 |
-19.2% |
SNWS |
43 |
62.4 |
45.1% |
SPR |
59.5 |
91 |
52.9% |
SRAD |
111 |
143.33 |
29.1% |
SUP |
93 |
180 |
93.5% |
TENT |
62 |
45 |
-27.4% |
TMG |
42 |
31 |
-26.2% |
ULTP |
123 |
85.56 |
-30.4% |
VID |
505.25 |
100.4 |
-80.1% |
VP |
540 |
604.09 |
11.9% |
WIN |
241 |
605 |
151.0% |
Total |
21.1% |
During this period, the UK Small Cap Index (excluding Investment Trusts) returned 14%, so this is a handy outperformance. This will have been further enhanced by the higher dividend yield received from these stocks due to the dividend yield criteria in the screen. Overall, it shows that buying cheap can work, even in difficult market conditions. Not every stock delivered great returns, of course. However, there were enough, such as Pan African Resources (LON:PAF) with gold price exposure or £WIN that was taken over during the period, to deliver good results overall.
The returns are even better when looking at the ten stocks that I chose to highlight:
Price at: |
13/9/23 |
3/2/25 |
Price Return |
TMG |
42 |
30.5 |
-27.4% |
BILN |
350 |
490 |
40.0% |
ALU |
162.5 |
287.5 |
76.9% |
SNWS |
43 |
61.4 |
42.8% |
ULTP |
123 |
84.4 |
-31.4% |
HAT |
406 |
338 |
-16.7% |
SFR |
60.4 |
49 |
-18.9% |
VP |
540 |
575 |
6.5% |
NWOR |
15 |
22.5 |
50.0% |
PAF |
14 |
41.2 |
194.3% |
Total |
31.6% |
(Note that I chose to cheat slightly and replace Reach (LON:RCH) with the much cheaper National World (LON:NWOR) in this smaller list after my analysis of the sector.)
Again, higher dividends would have further enhanced the returns here, and I estimate the total return from holding this portfolio of stocks would have been around 40% versus around 20% from investing in the small cap index over the same period.
It is worth noting that in this smaller portfolio, the presence of a large winner, such as Pan African Resources (LON:PAF) , can skew the results. However, even if I exclude this stock, the total return of the portfolio would have been around 30%, which is still significantly higher than the total return of the UK small cap index. It seems value stock-picking is not a completely dying art form!
The Same Screen Now
At the start of this week, here are the results from the same screen:
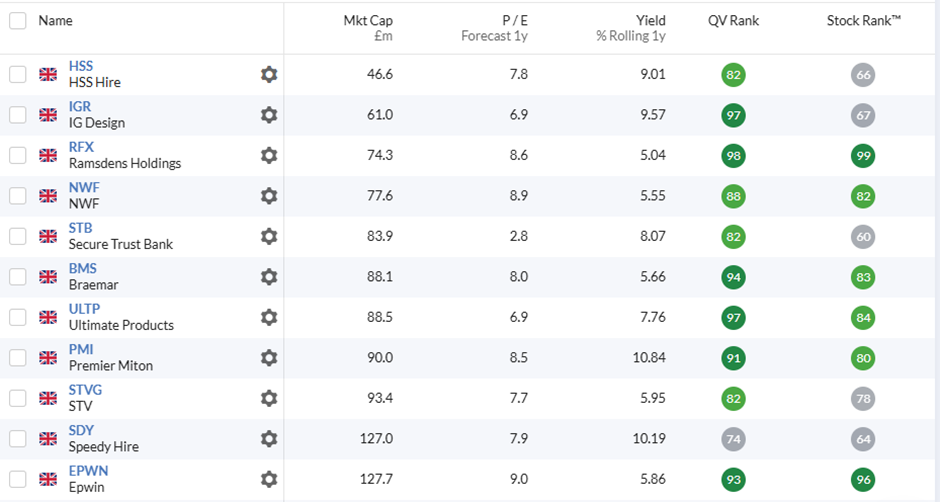
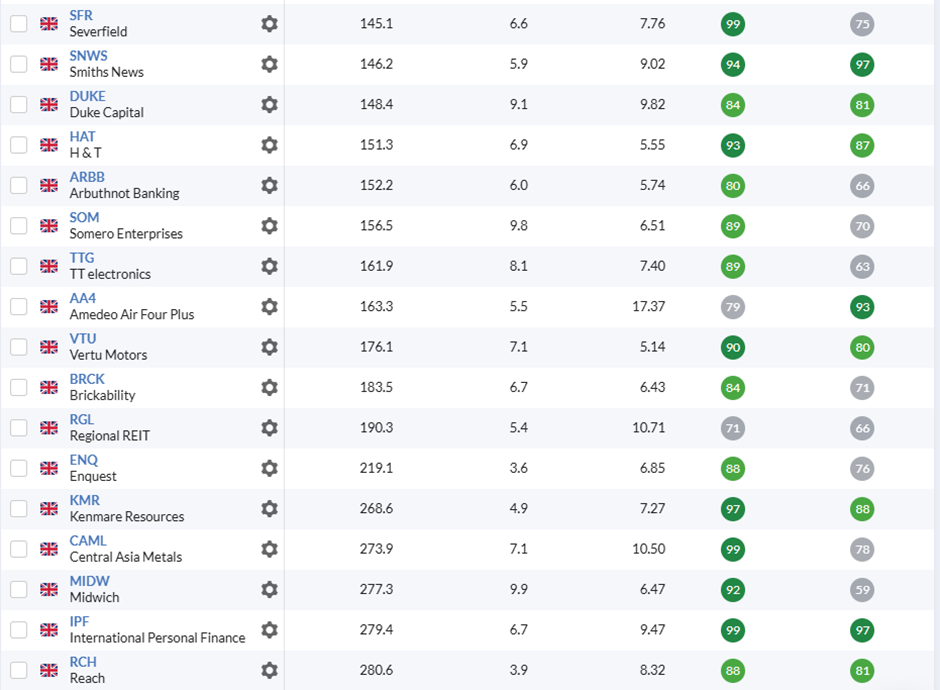

Of these, nine were on the original small cap silliness screen, and four of these made my smaller list of ten stocks: H & T (LON:HAT) Severfield (LON:SFR) Smiths News (LON:SNWS) Ultimate Products (LON:ULTP) . This isn't necessarily good news. Severfield (LON:SFR) and Ultimate Products (LON:ULTP) have both had severe profit warnings, and it may be too soon to call the bottom here. Smiths News (LON:SNWS) has re-rated but has not managed to mitigate the cliff edge it faces at some point in the future when the major newspapers stop physical printing. H & T (LON:HAT) still looks cheap but not as cheap as rival Ramsdens Holdings (LON:RFX) .
Liontrust Asset Management (LON:LIO) and Kenmare Resources (LON:KMR) were both part of the original Midcap Madness screen but have fallen sufficiently to now qualify for the small cap version of this screen instead. I think both of these still look good value despite the share price falls.
The New Stocks
Here is a quick look at some of the more interesting stocks that have been added to the screen:
IG Design (LON:IGR)
It's worth making a brief comment on this one. I picked this as one of the 12 Stocks of Christmas, at least partially because they are a supplier of seasonal goods. So far, it has been a terrible pick. My thesis was that its assets, largely inventories and receivables, will become productive again at some point, and they have a management team committed to making this happen. So, buying at 0.5xTBV would give a considerable upside. However, this didn't protect the downside when the company announced a huge profit warning in January:
Correspondingly, FY25 adjusted profit is now expected to be significantly impacted, with profit delivery for the full year around break-even, and well below last year, as well as being significantly below current market expectations (believed to be $32.0m)
The problem is that management also said:
Under these challenging circumstances, at this stage, and until the recent events are more fully assessed, the Board is no longer able to provide guidance for the years beyond FY25.
This means that the forecasts in the StockReport have been withdrawn, and the P/E can't be relied upon:
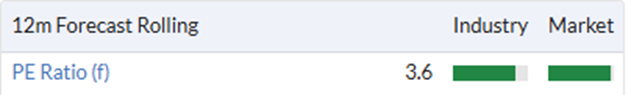
Following the c.60% fall on the profits warning, the company is arguably even better value on an asset basis:
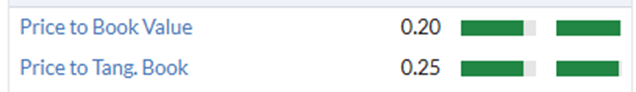
And the shares trade at the same level as when the company was in financial distress, something that is no longer the case. So, this may be a good recovery play. However, it doesn't meet the requirements for my small cap silliness screen, which is a business that is cheap on forward earnings. Hence, I'm not including it here.
[For more background on the company, Roland wrote a StockPitch article last year.]
Ramsdens Holdings (LON:RFX)
The last set of small cap silliness included pawnbroker H & T (LON:HAT) . This time, it is joined by competitor Ramsdens Holdings (LON:RFX) , indicating that the sector is currently unloved.
The poor performance of H&T is partly down to its pattern of broker downgrades:
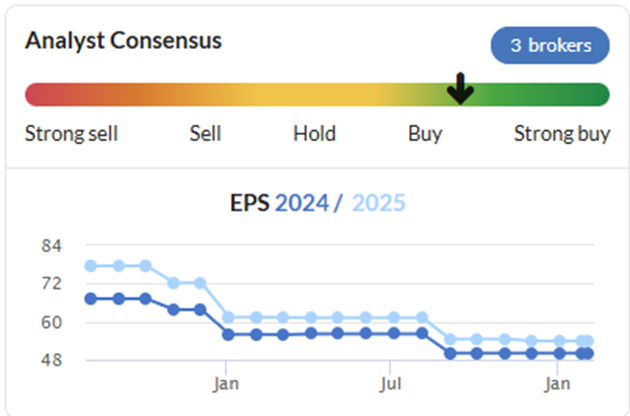
However, the same can't be said of Ramsden's, where an inherent conservatism in forecasting has had the opposite effect:
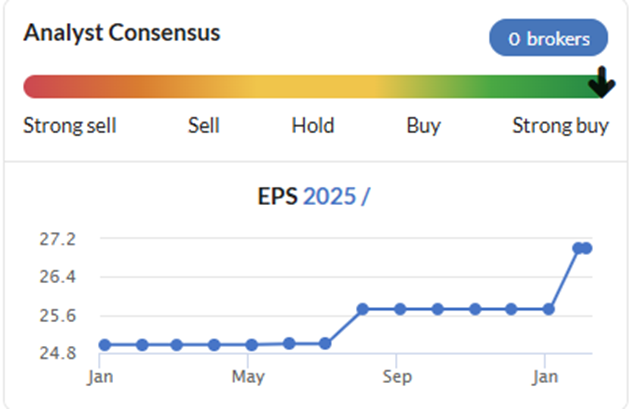
Despite this, Ramsdens is cheaper once you take into account the net cash at Ramsdens and net debt at H&T. Whereas H&T only just gets into double figures for ROCE:
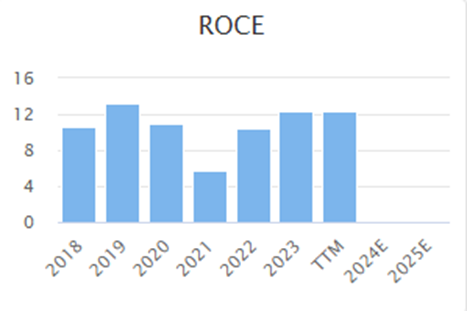
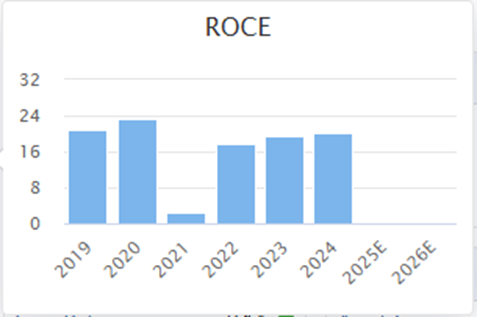
Ramsdens ROCE often exceeds 20%:
Ramsden's revenue is forecast to grow further:
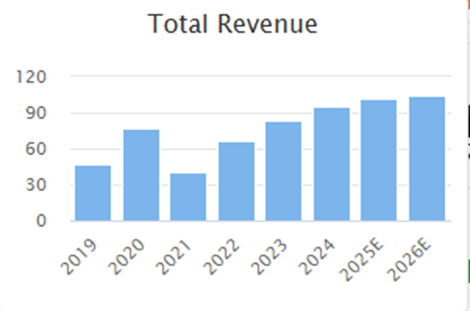
EPS growth is forecast to only be mid-single digits. This is partly due to the impact of upcoming National Insurance cost increases for employees. However, I wouldn't be surprised if these figures are upgraded again over time, making the forward P/E of 8.7 looks too low.
NWF (LON:NWF)
NWF reported their Half-year results on Tuesday, and the market was unimpressed, marking the shares down slightly to 150p. The results themselves don't look too bad, at least on an adjusted basis:
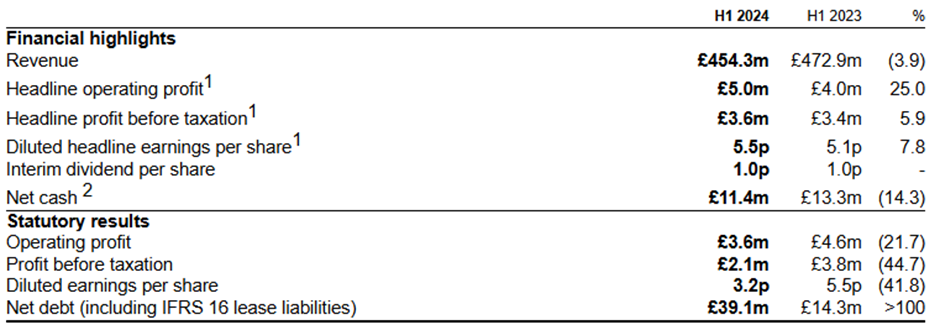
Revenue is down, but that doesn't really matter for a distributor of commodity products. Headline Operating profit is up significantly. And importantly, they say:
The Board's full year trading expectations remain unchanged ahead of the seasonally more significant second half.
Meaning that these metrics look good value:
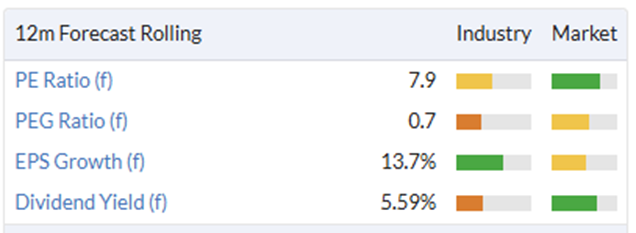
It is worth noting that they don't get a favourable comparison to their industry because it is classified as an oil and gas company. This is presumably because a large part of their turnover is fuel distribution. However, they are a very different company than an oil extraction business.
Although they are a very low-margin business being a distributor, their return on capital has been acceptable (although not outstanding) due to their rapid asset turnover:
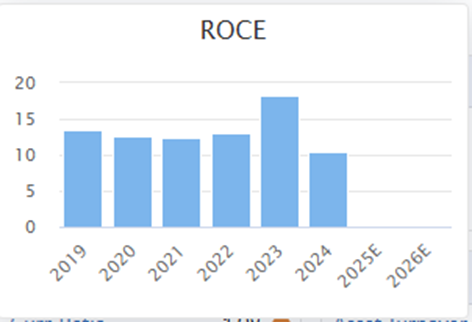
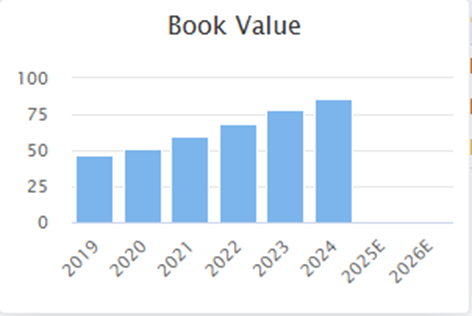
The recent dip reflects both weaker earnings than the exceptional level in 2023 and growing book value:
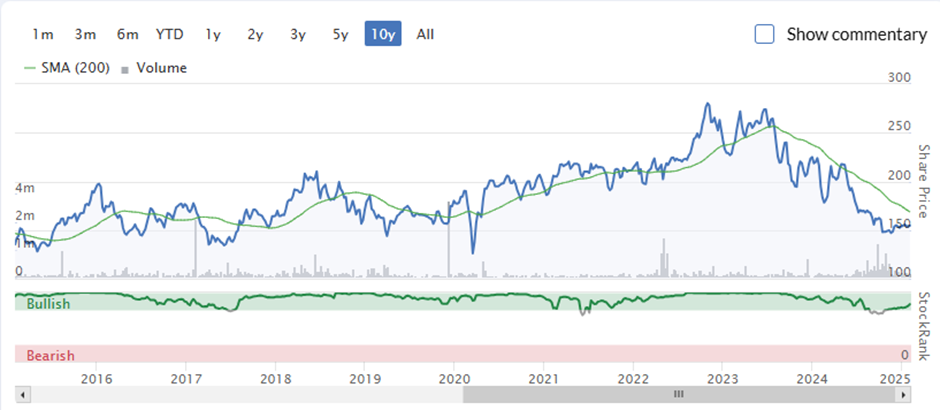
Over the long term, this appears to have some cyclicality, and we are currently in the down phase:
However, the company has an enviable dividend record:
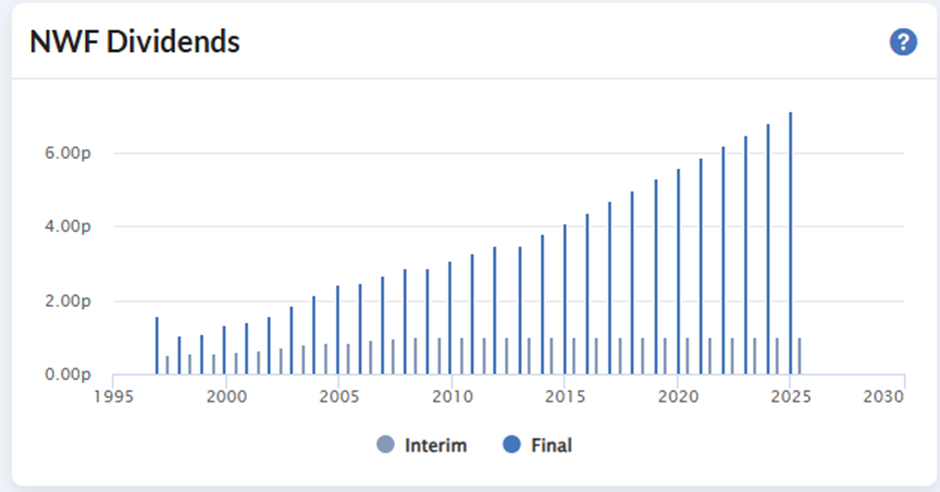
The forward yield is over 5% and rewards investors willing to wait for the next upswing, whenever it may be.
Braemar (LON:BMS)
Braemar is a cheaply rated stock:
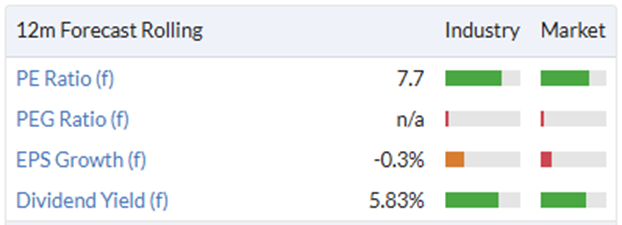
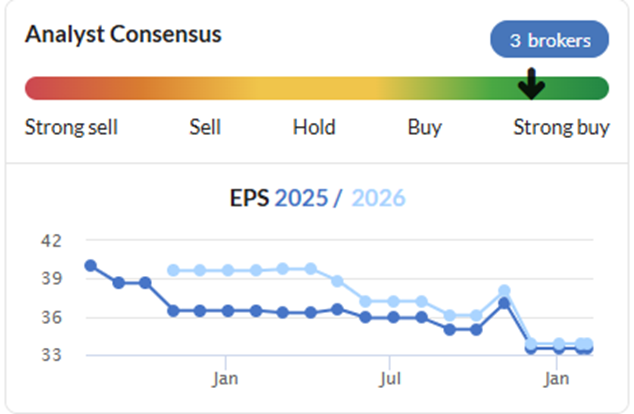
But then, as a people business where the employees like to be paid bonuses, it perhaps should be. Being a shipping broker, it is also subject to large swings in shipping rates, which makes results volatile and hard to predict. The recent broker trend isn't particularly encouraging:
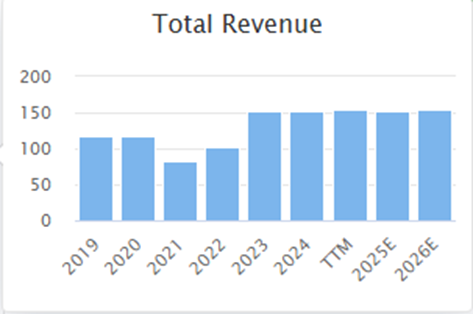
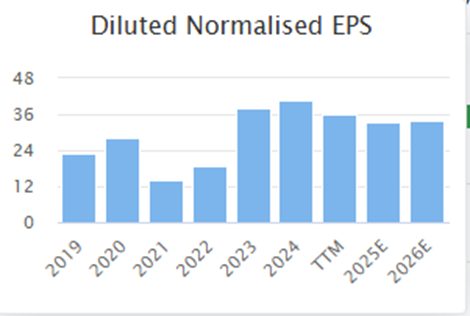
Nor is the revenue or EPS trends:
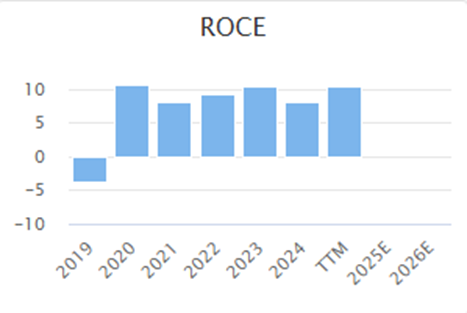
The return on capital isn't particularly impressive either. (Although it is worth noting that the vast majority of the book value is goodwill from acquisitions.)
Some investors may be able to get an edge in this sector by analysing shipping rates and other industry factors. This is cheaply rated. However, I do not see enough evidence that this is market silliness rather than rational pricing of a people business that isn't forecast to grow in the near term.
Premier Miton (LON:PMI)
Asset manager Premier Miton is at the smaller end of the UK asset management sector. However, it is doing better than many at the moment. In its recent trading statement, they said that they experienced outflows of £33m. However, this is just 0.3% of their AUM. As one may expect, the outflows were concentrated in UK equity funds:
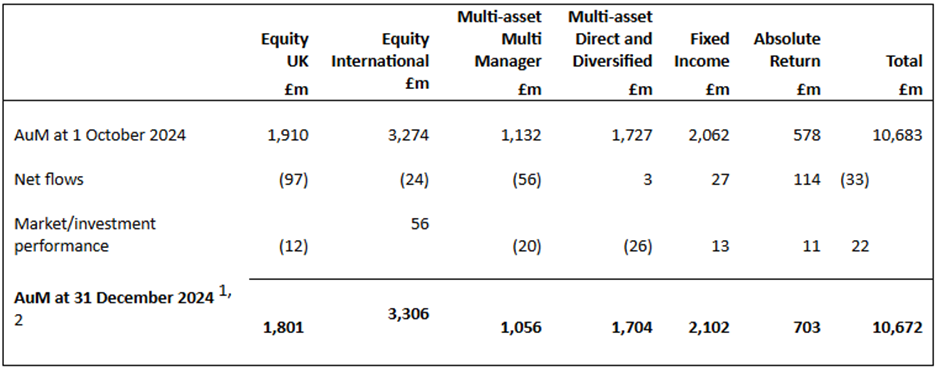
These outflows were focussed early in the quarter:
Uncertainty ahead of the UK budget was evident during October and this resulted in net outflows during the month. However, it was pleasing to note that flows turned slightly positive in both November and December.
And the rest of their strategies are offsetting this weakness:
This was largely driven by positive flow into our US equity, Diversified multi-asset, fixed income and absolute return strategies alongside continued outflows from our UK equity strategies.
Even in these challenging times, the rating remains modest:
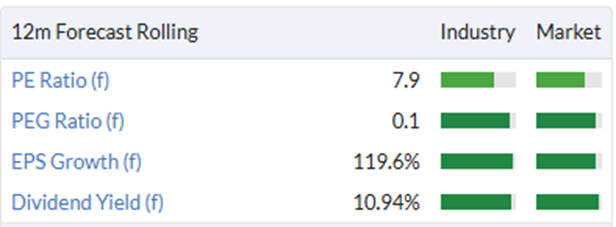
And unlike many peers, the 6p/share dividend is still just covered by earnings:
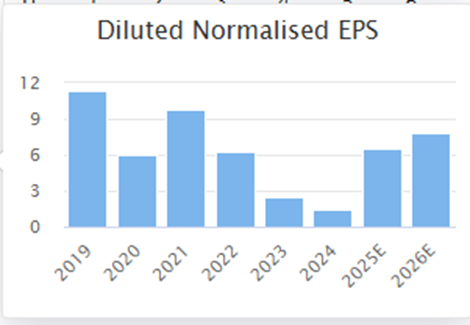
This should make it sustainable in all but the most extreme market conditions, which means investors will receive an 11% yield. They also have about a third of their market cap in cash:
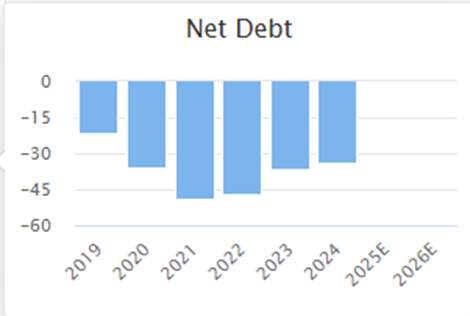
While some of this will be regulatory capital, it gives further reassurance that the company can ride out this sticky patch.
STV (LON:STVG)
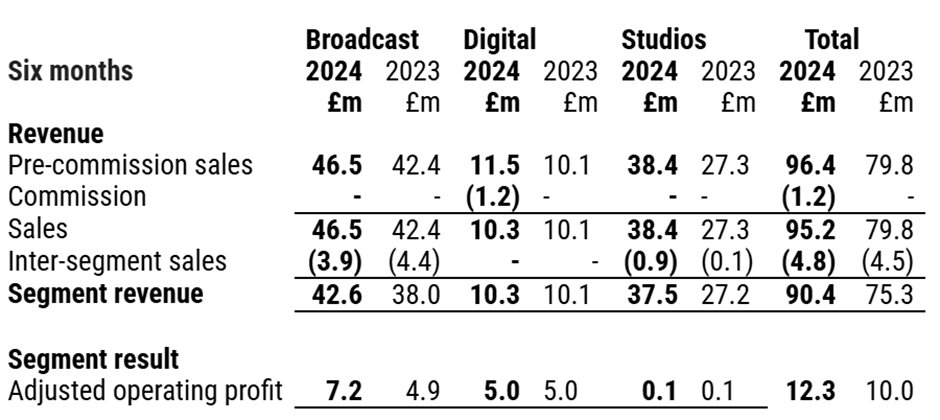
I looked at ITV in my More Midcap Madness article. Many of the arguments for holding ITV also apply to its smaller brethren, STV. While the broadcaster is best known for the TV channel, the studio part of the business is becoming increasingly significant (although not contributing to H1 operating profits due to seasonality):
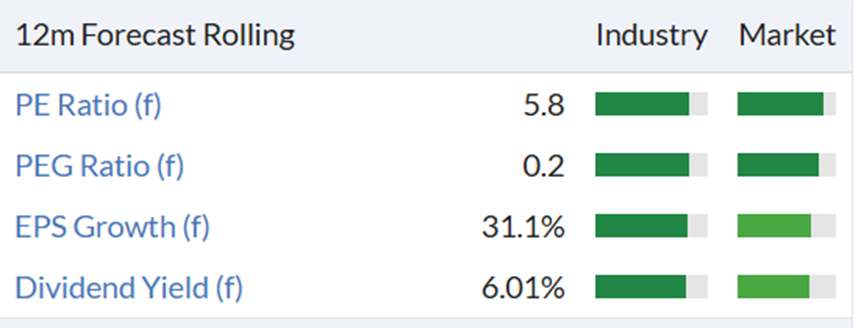
On the surface, the metrics look even better for STV than ITV:
The share price has been relatively weak for a company where the broker trend is slightly positive:
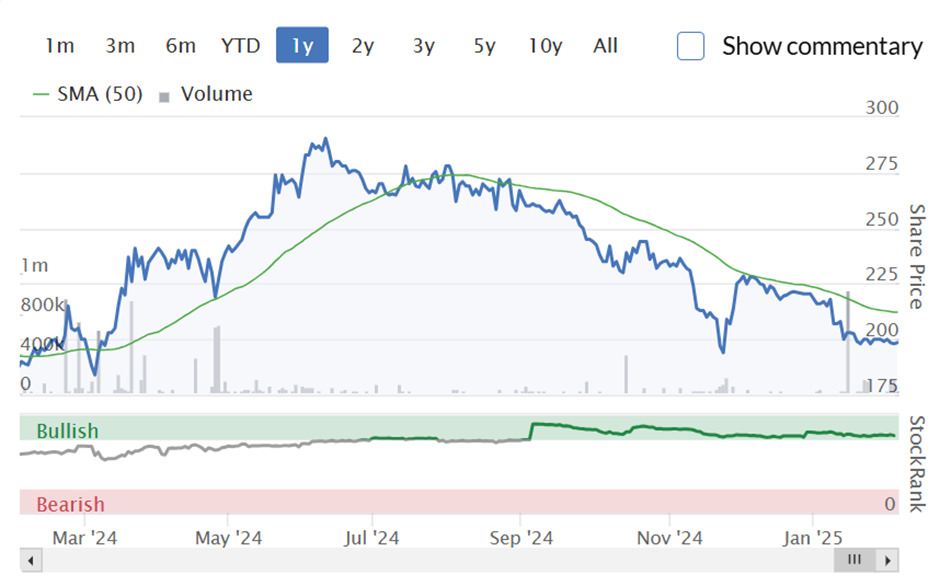
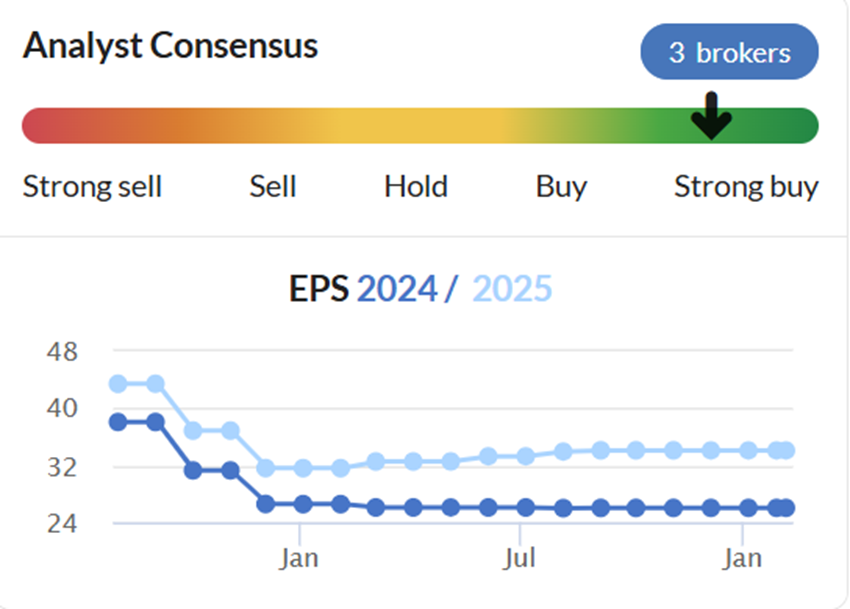
So, this may be an opportune time to consider this stock. However, every time I look at this company, I return to two factors that impact the valuation. The first is that the company has £28m net bank debt. The second is a large pension deficit. Usefully, the company has recently updated the triennial valuation. Here are the headlines:
· Funding deficit reduces to £61m from £116m in 2020 valuation
· Aggregate monthly cash contributions slightly lower
· Contingent cash contribution mechanism paused until at least 2028
Those cash contributions are £10.2m, not insignificant, given that the net profit consensus is at just over £18m for FY25:
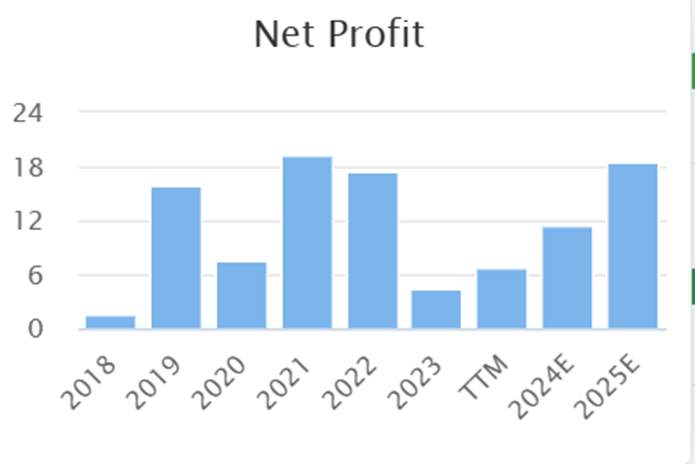
However, ending in 2030 is probably near-term enough to treat the total deficit as debt. With a market cap of £92.5m, we have an effective enterprise value of £183.5m. Research provider Progressive have an adjusted EBITDA forecast of £30.8m for FY25. This means the company trades on 6x adjusted EBITDA. It is not as cheap as it first appears, but it may still be worth considering, especially if trends for growing studio revenue and a potential recovery in the advertising markets are factored in.
Brickability (LON:BRCK)
You would expect that a supplier of construction materials would be a coiled spring at the moment, preparing for a boom in housebuilding driven by government incentives. However, the price chart suggests otherwise:
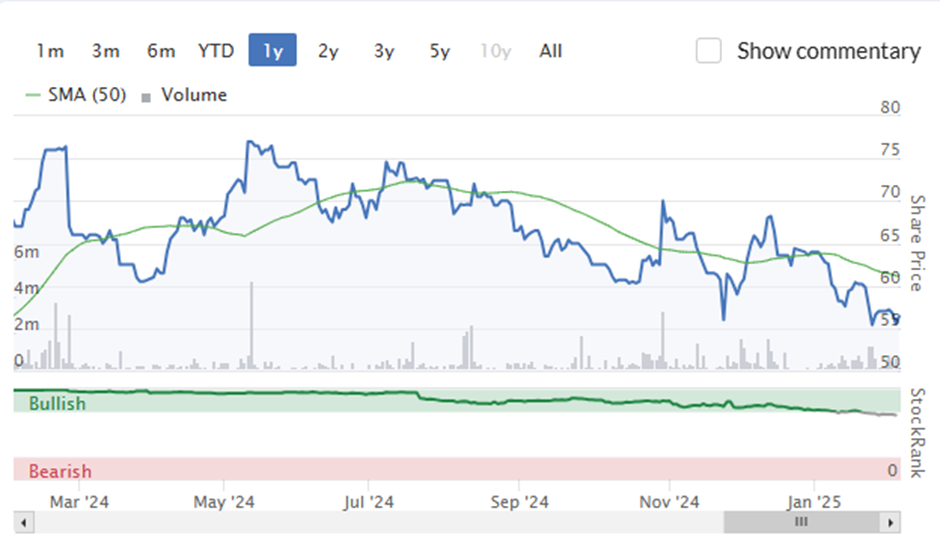
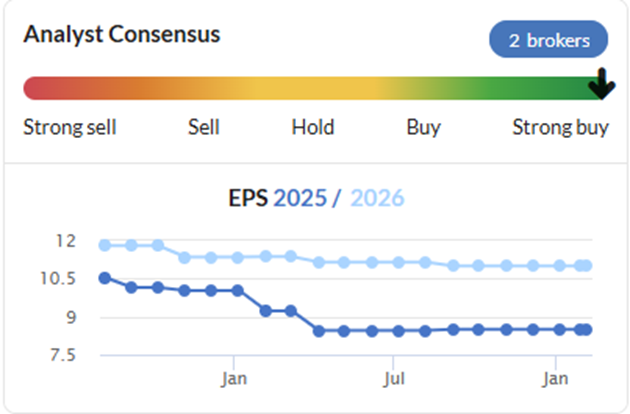
However, this is driven by broker downgrades, which are largely flat over the last six months:
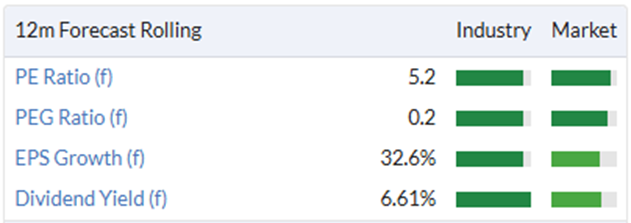
Leaving the company on a very modest forward rating:
There is, however, around £56m of net bank debt that the company has taken on to fund acquisitions, most recently TSL in January 2024 and Topek in October 2023.
As is often the case with acquisitive companies, there is a big gap between statutory and adjusted profits. They haven't covered themselves in glory in the past, having to write off a loan to a JV, for example. However, a new CEO joined in April 2024, and management changes can often bring better capital discipline.
Their underlying cash flow has allowed them to increase their dividends over the years:
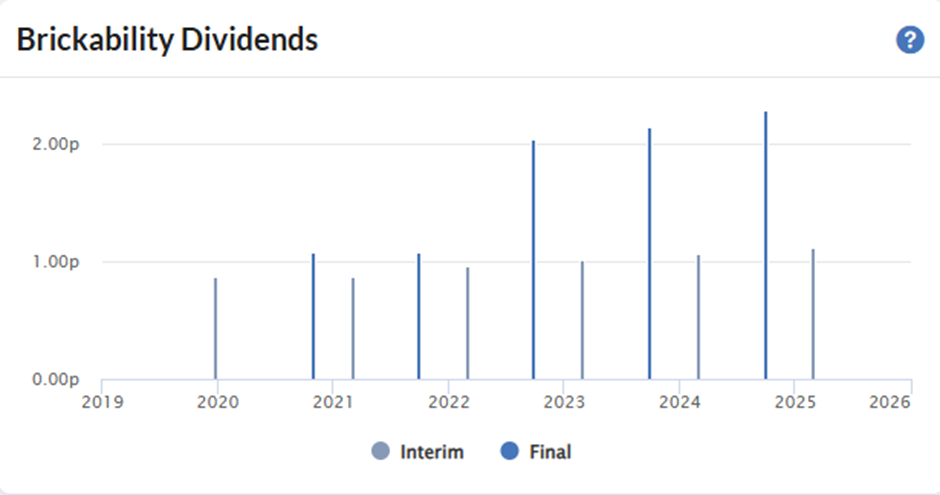
With a forecast yield of over 6%, investors are paid to wait for the sector to benefit from increased demand in the sector.
Vertu Motors (LON:VTU)
Motor retailer Vertu is very much the last listed dealership left standing in the UK markets. All the other dealership groups have been acquired over the last few years (apart from Motorpoint, which has a slightly different business model). While there was a lot of competition for the acquired dealerships, not all of them appear to have flourished under their new management. This is both a blessing and a curse for Vertu. Less capital going into competitors strengthens their trading position. However, it also lessens the chance that Vertu themselves get taken over.
There's still a chance that they may be in the crosshairs of a bigger group. The shareholder register still includes Constellation (under the guise of CAG Vega 2 Ltd) and Gavin Hydes, the boss of Irish motor dealer Joe Duffy Motors (represented by Nivag Holdings Ltd, Nivag being Gavin backwards!) One can't help feeling that if a deal was there to be done, it would have been completed by now.
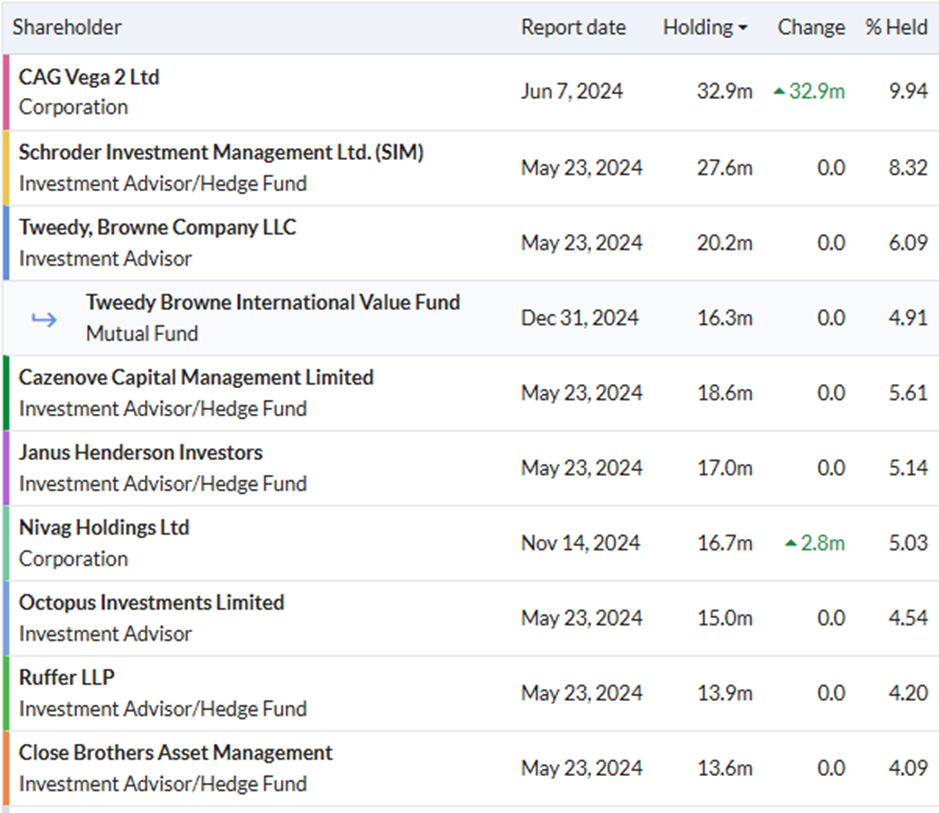
Putting aside any chance of corporate action, Vertu is very modestly rated:
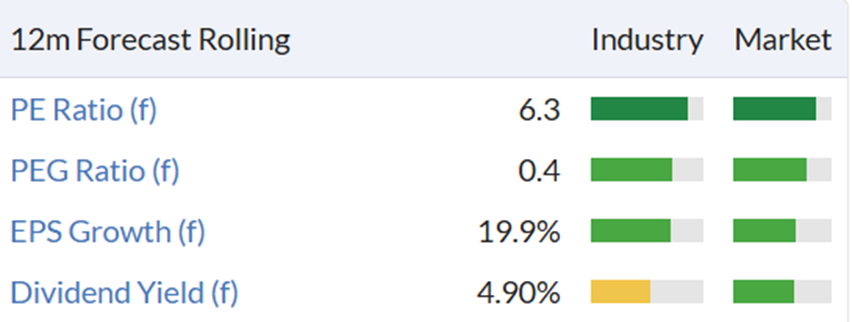
It has never been a particularly highly rated stock. The market has genuine concerns over how the motor industry will look in several years. Many electric car brands sell directly to consumers, and electric cars require less servicing (a big earning for the dealerships.) However, what marks this out as potentially oversold is the discount to TBV:
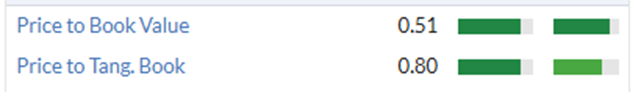
The bulk of this is freehold property that often has alternative use value. While this isn't intended to be an asset screen, this gives confidence that if the returns from being a motor dealer evaporate, in the long term, the share price won't.
Impax Asset Management (LON:IPX)
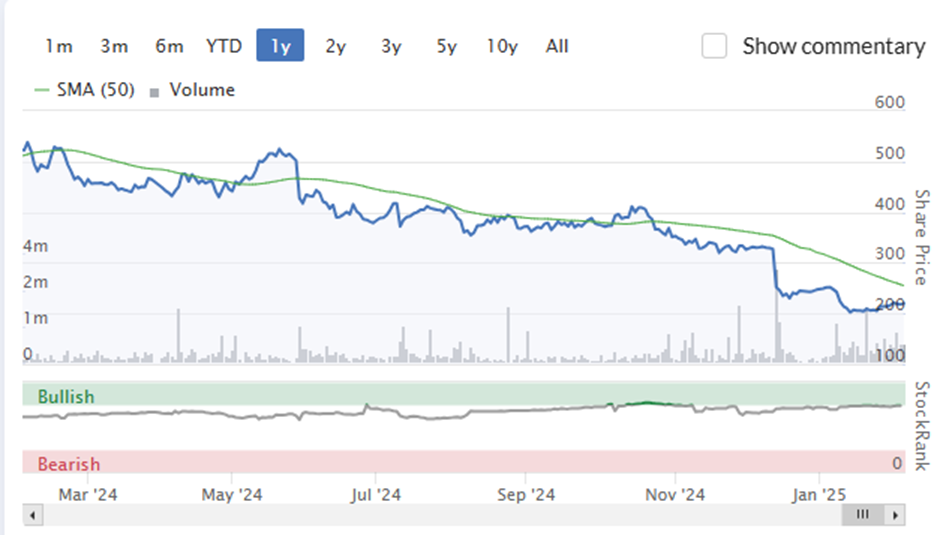
It's fair to say that investors in Impax have had a torrid time recently:
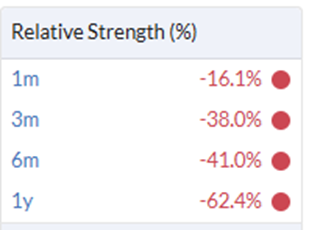
Losses in mandates, together with declining AUM, have made this once darling of the sector the ugly step-sister:
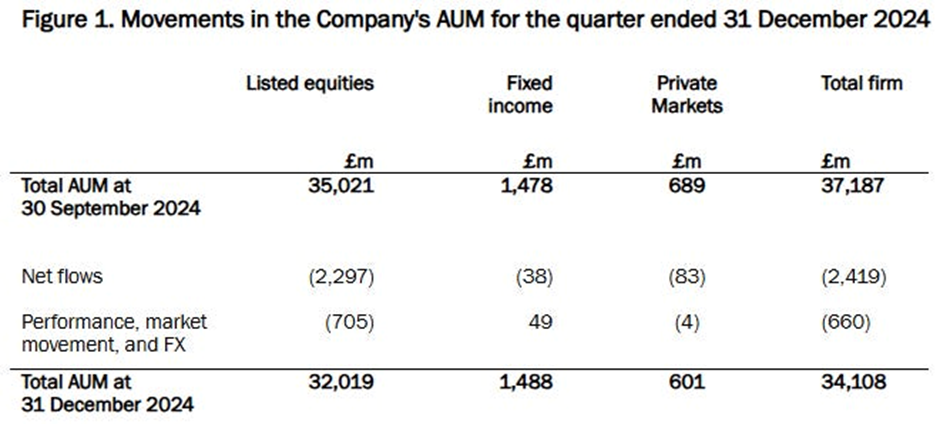
The big StJames Place AUM exit is yet to come, so this latest quarter does not read well:
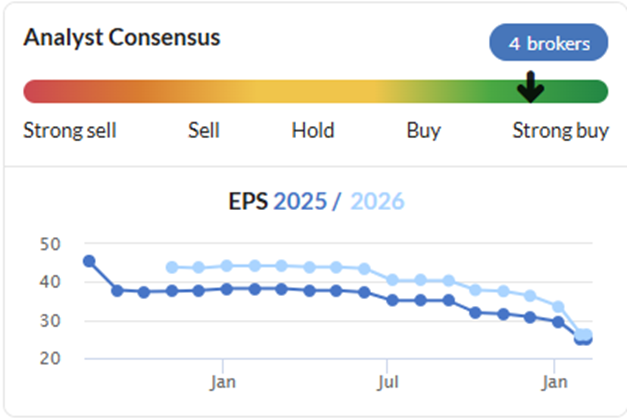
This is reflected in declining broker forecasts:
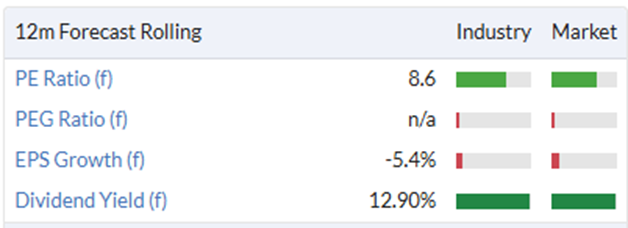
Despite this trend, the shares are now cheaply rated:
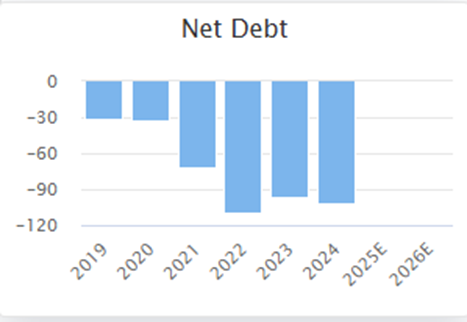
Especially as a third of the market cap is in cash:
This means that brokers are forecasting for dividends to be raised slightly in FY26:
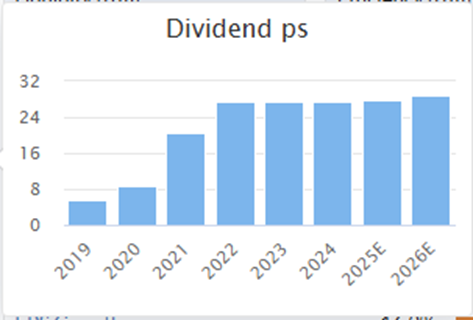
Making the 13% dividend yield look sustainable until better market conditions return.
So, this time round, I have a new set of nine stocks that look too cheap on forward earnings and dividend yield, Ramsdens Holdings (LON:RFX) NWF (LON:NWF) Premier Miton (LON:PMI) STV (LON:STVG) Brickability (LON:BRCK) Vertu Motors (LON:VTU) and Impax Asset Management (LON:IPX) , plus the two fallers from the Mid Cap Madness list: Liontrust Asset Management (LON:LIO) and Kenmare Resources (LON:KMR) . I will review again in a year or so to see if these perform as well as the original small cap silliness set.
[Disclosure: Mark owns shares in IG Design (LON:IGR) Premier Miton (LON:PMI) Ramsdens Holdings (LON:RFX) ]
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

19 comments
Eurocell (LON:ECEL) very similar to Epwin (LON:EPWN) just misses the screen, as dividend is only 4.8%
Another stock worth looking at that didn’t make this screen, but is cheap on forward looking forecasts, 6% dividend and recent bod buys of nearly £2m. Foresight group (LON:FSG) Nice quality score too.
This comes up on my quality garp screen I know them reasonably well they are a bit double glazing like with the hard sell on product push and involved in a lot of bpr offerings so not sure how the recent budget iht changes will impact them yet. Fund outflows don't appear to be as much of an issue as with the other major mid range fund houses.
Heroic effort. Thanks Mark.
Great post once again, everyone loves a good bargain. Thanks.
Would it be worth a mention as another value play being Oxford Metrics (LON:OMG) ?
While it has missed out on this screen, the current tumble in the sp has left it at an EV value of just £15m. It probably missed the screen due to it's higher PE, but due to the high cash position, this would probably be worth working out by EV/EBITDA instead of using PE.
It is a terrible looking chart and initially I had an alert set for 41p based on charting, and it could well drop to that level. But I'm not so sure now as at that price a buyer would then be picking up a profitable company, that has been running for 40 years with a product that is "Best in Class", all for basically, nothing.
So, to pick it up now at an EV of just £15m, you get a company forecast to make £3m profit this year. Now, that seems like a bargain to me!
Hi gmtrader,
I largely agree, and have been adding to a small position here recently. The core product is clearly good as the high gross margins suggest. I am less convinced by their diversification strategy into industrial applications, and hiring a new CFO from FireAngel, of all places!
I'm not sure if it will hit this screen as the cash balance makes the P/E high. It is if we adjust it out that they look very cheap. The cash also protects the downside but the it also limits the upside, as they will start to look expensive again above 80p or so, unless they can drive a recovery in EPS.
So a very good low-risk positive expected outcome bet below 50p IMO, but with more limited upside than in the past.
Cheers,
Mark
Yes that was my thought. An easy 50% uplift unless they actually do make good use of the surplus cash. This is my third venture into Oxford Metrics (LON:OMG) making 50% both previous times. Lets hope for third time lucky.
Thanks Mark - Ive copied and then tweeked the list as I prefer to go for a bit larger market cap. Is there an easy way to then copy into a folio each stock with say £10000 invested so that I can monitor progress ?
Thanks
Hi bohenie,
You can select all the results of a screen and then click to add them all to a portfolio, but transactions can only be added individually.
This being an example.
Regards,
Jon
You can setup the transactions in a spreadsheet then import into a folio. There's help on this in the folio screen
Interesting article thanks mark
Hi Mark, it appears that we have similar investment approaches. I hold Brickability (LON:BRCK) average buy price 61p, Ramsdens Holdings (LON:RFX) average buy price 213p and Premier Miton (LON:PMI) average buy price 58p.
It is difficult to understand why all three remain so cheap based on current metrics and given falling interest rates.
As you mention, there is a relatively new CEO at Brickability (LON:BRCK) , Frank Hanna who is well regarded and was previously joint CEO at Michelmersh Brick Holdings (LON:MBH). Apart from the anticipated demand for bricks and other building materials as and when house building picks up, the company operates a capex light model and is a beneficiary of the demand for cladding and façade works as a consequence of the Building Safety Act.
As for Ramsdens Holdings (LON:RFX) the gold price remains elevated and is likely to continue do so, given the inflationary agenda of the somewhat delusional Mr Trump. In addition demand for foreign holidays remains strong so should benefit FX. Jewellery and high end watch sales have stabilised and challenging economic conditions should provide support for pawn broking.
I added more Premier Miton (LON:PMI) this morning at 55p. Given that AUM outflows have stabilised and falling interest rates are positive for equities, especially small caps. There is also some £30m cash or thereabouts on the balance sheet, which as you point out represents a sizeable percentage of the market cap..
I am of the view that patience will ultimately be rewarded.
Mark, Vertu Motors (LON:VTU) just released a RNS, looks like a profit warning. Bad form, releasing at 14.35 hours.
Yes, agreed. You can’t say they only found out about these headwinds at lunchtime today. The lack of reaction so far perhaps suggests that the property value is protecting the downside or the buyback being increased .Although the update also appears to have caught the brokers on the hop so we don’t have a steer on what the short term impact is. There may be further falls when the notes land on desks.
Vertu Motors (LON:VTU) certainly did not find out about these issues on 6th Feb. I posted this link in DSMR on the 12th December having noticed it on 11th December. This problem was well known in the car sector and formed the strategy for holding back sales of petrol and diesel cars to avoid large and avoidable fines, but could be considered madness caused by govt quotas:
Car makers 'withholding deliveries of new petrol and diesel models until January' to hit 2024 EV sales targets
Great article again Mark. Lots of stocks with negative momentum here so it will be interesting to see if they pick up to any great extent within a year.
great article
Love these type of articles. Thanks Mark
Thanks, Mark. That’s really interesting and helpful.