Small Cap Dog of the Day LOOP UP (TCN, PCIP, QUIZ, HSMO, RBG, DISH)

£LOOP
Tricorn (LON:TCN) - Tricorn one for the naughty step
Updated 16th Nov 2020
Declining from 40p to 5p today. Tricorn (LON:TCN) provides a post-trading update that the New Finance Director fines £3.6M hole in the financial statement. This is seldom with just error and is probably known to be happening by a number of personal at the company. I suspect it going to get a lot worst before the truth is known.
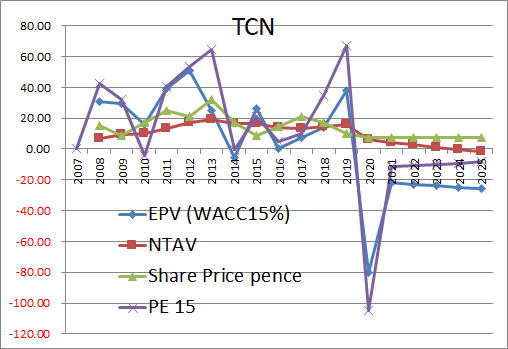
Sales profile 2019-2025

The Model below suggest this should be on the bargepole list
Bigdish (LON:DISH) – Buyer Beware
Updated 16th Nov 2020
Only the most guidable audience would believe today's announcement.
Translation of today's Funding Update (12th Oct 2020)
'The Company has signed a Letter of Intent (LOI) with a Central European investment group ("the New Investor") that has diverse multinational investment holdings, that is owned by an Ultra High Net Worth Individual (UHNWI). The LOI provides for a USD 5 million investment subject to key Conditions Precedent ("CPs") which are outlined below:'
Translation ;
- Bigdish (LON:DISH) was unable to raise money from shareholders or the markets
- The Bigdish-to-GO Saas platform is delayed to Q1 2021.
- The funding available is conditional on auditing and completing the SaaS platform and Restaurant acceptance of BigDish-to-GO and business plan.
'If successful, the investment would be made into a Special Purpose Vehicle (SPV) to support international expansion and would not be dilutive to the Company.'
Translation;
- Deare shareholder we think its best if we don't tell you how onerous terms of the agreement will be
'The Company has been managing its cash position and in order to ensure the successful build-out of the SaaS platform has secured a short term loan from an investment company of £540,000. These funds would be used to include increasing the size of the technology team in order to facilitate the build-out of the SaaS platform. This short term funding will ensure that the Company has sufficient runway until the end of the second quarter of 2021 and to ensure the CPs are completed. Loan repayments will be due in the second and third quarters of 2021.'
Translation;
- Deare shareholder we think its best if we don't tell you how onerous terms of the agreement will be
Buyer Beware
The share price has declined from a high of 9.2p to 2.25p. (I have no position)
There are many reasons to avoid putting hard-earned cash into Bigdish (LON:DISH), but most importantly because the company's only purpose seems to move wealth from investors to management. I’m still trying to figure out where has all the CASH gone?
With limited resources (management and cash) Bigdish plan to take on dining reservation and delivery service apps. For Investors to profit they have to believe that the current zero-revenue business model generating zero cash will generate a critical mass network of restaurants and users to increase company valuations. All this must happen with the current cash and without mass dilution, as the Bigdish (LON:DISH) try to raise more cash.
Why this should be on every private investor’s barge pole list
Late to the party – Competition has already achieved critical mass and networking-effect.
Competing companies have already achieved a critical mass and networking effect. The competition includes;
- OpenTable have 5m+ users, it also pays customers to use the app with a reward scheme
- Deliveroo 10M+ users,
- Uber Eat 100M+ users,
- Just Eat 5M+ users.
The larger restaurant group have their own personal app all for free.
Bigdish with 50k+ users will need to spend substantially on marketing to reach any meaningful size.
Musical chairs for CEO’s and Strategies
- Aug 2018 Listed with Joost Boer, CEO
- Aug 2018 announced Asia company acquisition and strategy.
- Nov 2018 (3month later) consider the sale of Asian business and of Asia strategy
- Jan 2019, Bigdish hires new CEO Sanj Naha and refocus strategy to the UK. (No more news on the Asian business sale).
- Dec 2019, Hires Tom Sumner as the new Chief Executive Officer
- Mar-2020, Saved by COVID-19, Furloughed employee saved cash burn. The company engaged/pay foreign advisory to raise additional funds
- Jun-2020 Announce will require more funding by year-end 2020.
- Jul 2020 With money running out, new strategy decided to change to zero-fee model for reservation platform (No money), move to a SaaS model (more cost, revenue delay), and launch BigDish-to-Go to take on giants like Deliveroo, and Uber Eats (more cost).
- Announcement coming out quicker than hot dinners about new restaurants on the platform note all at zero cost. I assume this is to raise the share price before they tap investors again.
The only successful strategy the company has executed so far is to tap investors for cash and pay it to management. (see below)
Raising cash, raising more cash, and dilution
- Aug-2018 Listed with 285M shares at 4.5p raising £2.2M.
- Jun-2019 placing 29.2M shares at 7.2p company says its fully fund until 2021.
- July 2019 issued more share 23M shares issued apparently to pay management (Salary sacrifice) what happened to the cash raised in June?
- Aug 2019 13.8M shares issued to for Poucher shareholders.
- 24 Jul2020 More dilution as employees asked to take shares instead of pay. 24M shares issued
- 29 July BigDish Plc (LON: DISH), announces that Jonathan Morley-Kirk, Non-Executive Chairman, sold 349,045 shares that were recently issued under the Salary Sacrifice Scheme, at an aggregated price of 2.3 pence per share on 28 July 2020
Needs to raise significantly more than £2M to have a viable business
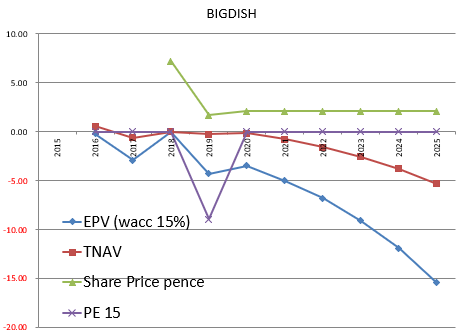
I’ve modeled out Bigdish's cost curve (see below). The cost of building an app can be approximately £250K-£500K, Bigdish has already raise £4.5M, and failed to capture a user base.
The largest cost will be the marketing cost for building the user base and network. Using the model at a 50% growth rate they would need to spend close to £15-20M to gain any meaningful scale of business. With a limited network of restaurants and users and competition from more successful and competent competition it hard to find any value in this company.
Possible they can tap up investors for more cash indefinitely, but I only see this share being valued at 0p at some point.
Models cost for building a user base and network.
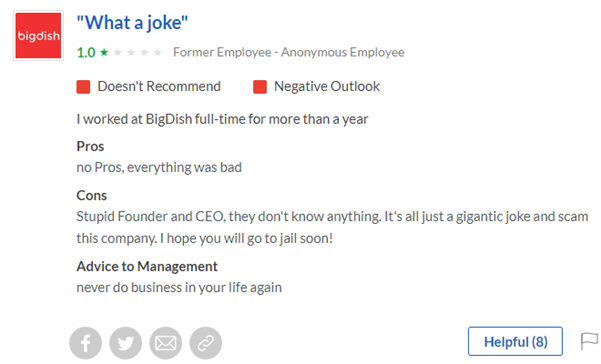
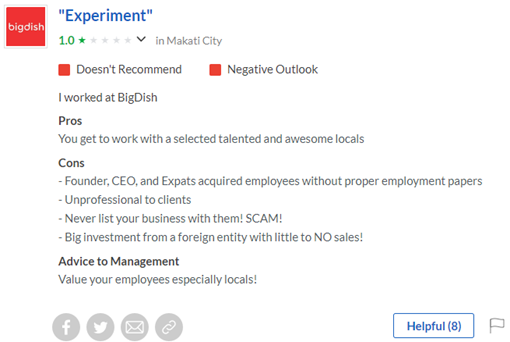
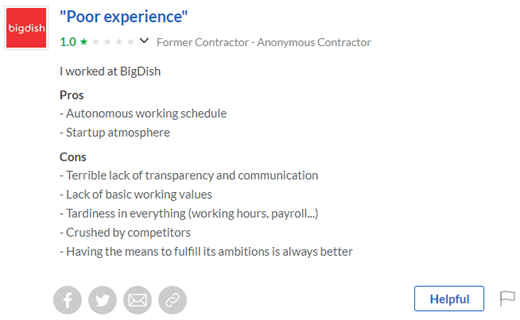
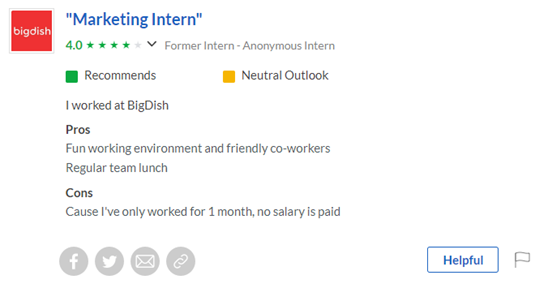
Finally, I leave you with what employees have to say on Glassdoor (employee company feedback website), and you can come to your own conclusion.
https://www.glassdoor.co.uk/Reviews/BigDish-Reviews-E1622525.htm
As Always, DYOR
BSV
Pci- Pal (LON: PCIP) - Long way from profitability
17th Sept 2020
With a market high of 80p, the share has fallen to 43p recently does this represent value, and has the company become investable.
The company has been on quite a growth spur recently due to home working during the COVID-19 period possible it can continue to grow.
The company to bang-up job selling company success stating;
- Revenue increase of 56% to GBP4.40 million (2019: GBP2.82 million)
- Gross margin increased to 69.2% (2019: 60.2%)
- Total contracted recurring ACV ("TACV(1) ") increased 66% and now stands at GBP6.75 million (2019: GBP4.06 million)
It all sounds really good, so why are we looking at a £4.35M loss?
Well, the fundamental reason is the costs are scale just as quickly as sales, hence find a profit is not easy for this company. Add to this the £1M capitalization of development spend and profitability looks a long way away.
By way of example take SG&A expenses the largest cost to the business.
From 2016-2020 sales grew by 400%, at the same time SG&A expense grew by 821%. (See table below).


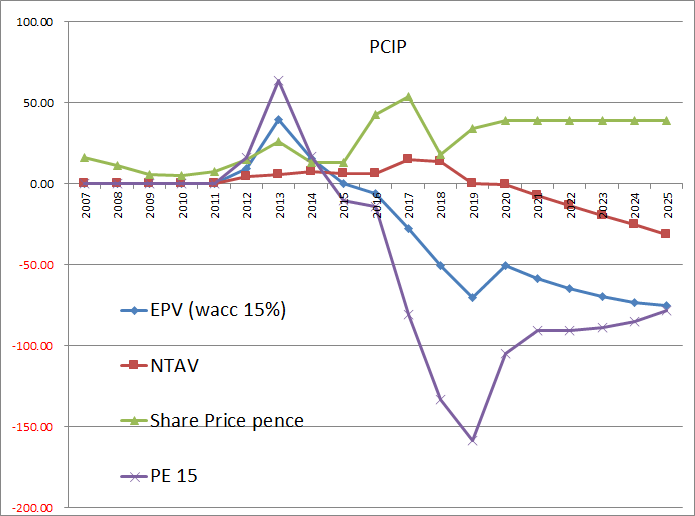
Future sales estimate 2020 - 2025

The model below suggests additional funding requirements in excess of £5M per year for a number of years.
Unless you're gots deeps pockets and patient capital this is one for the traders.
DYOR, don't trust the vloggers and bloggers.
BVS
Quiz (LON:QUIZ) - Still a poor business
Updated 16th Sept.
I was keen to understand how turnover rents affect valuations and I've tried to model Quiz (LON:QUIZ) below for illustrative purposes.
I found a useful article from fashion united which provides some detailed information. I included a link below which highlights what a contract might look like.
'The typical minimum base rent is around 75-80 percent of the total. The turnover payment element represents a percentage of the total turnover, usually between 5 and 12 percent; however, the mix can be tailored to suit both parties by negotiation. Typically, a retailer will want to increase the turnover rent element. (8 May 2020) .' (from fashion united).
https://fashionunited.uk/news/....
This probably does work well for a successful retailer, but not for a company like £QUIZ.
£23M of lease liability in 2019 with an average lease length of 26months. (£10.6M yearly rents)
So if we apply for some middle number base rent of 77.5%, and 8.5% of UK retail turnover
We get a base rent of £17.82M (base rent ) plus £7.64M (turnover rent, based on £89.8M retail turnover for 2019). This works out 25.46M for 26 months, or £11.75M yearly rent if sales recover to a previous level.
So no real reduction in rent as far as I can see, although it does help if revenues fall during another covid-19 shutdown. As the business has shut down a number of stores UK and internationally the rent will fall, but so will revenues supporting the cost structure.
My model still predicts negative cashflow even with a recovery of sales!
The CVA has extended the life of the company, not improved company management, its cost base, or its market proposition to the consumer.
DYOR
9th Sept 2020 ( current price 8p)
The retailer's IPO's placing price of 161p, before rasing to 207p high in 2018. It comes crashing down since to a 5p low in 2020. (I have no position)
Having reopened some stores and renegotiate rents within a pre-packed administration of the physical retail part of its business are things likely to improve?
Well, rents have come down and stores have been closed reducing overall costs. Rents are more aligned with sales within the physical stores, which must be good for future profitability.
Still concerning is the drop off in sales in physical sales (-89%), and online sales (-54%). Even in August Online sales are -11% low than the previous year. One would have expected online sales to be strongest in the current environment. With the gross margin declining by 6%, I can only conclude their core offering to the consumer is poor and competition too strong for this business to develop a meaningful recovery.
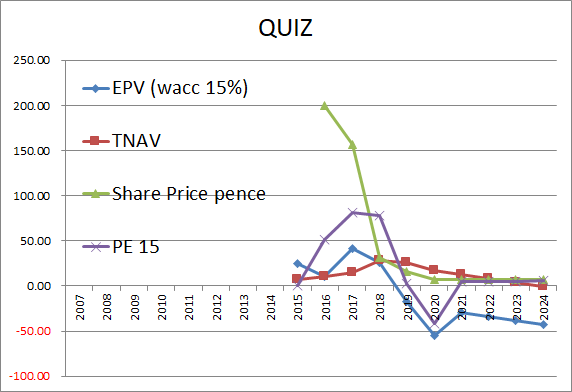
Sales profile 2019-2025

The Model below does show a 5p fair value (base on NTAV) for the company.
Possibly the company could recover sales more strongly, but QUIZ needs to demonstrate they have a consumer-relevant offer that does not need so much discounting. There are better management teams and companies worth looking at in the market so this needs to join the barge pole list for now.
As always do your own research. (DYOR)
BSV
Hammerson (LON:HMSO)
Updated 10 Sept 2020
Share price is 27p this morning. Is this really cheap?
I just revised my model Hammerson (LON:HMSO) with the revised share count and cash raised, it was a little bit difficult to keep track as new shares are placed and a share consolidation occurred at the same time. The overall effect was for the share count to increases from 765M to 3832M. (see below table). With a new £800m, the cash raised LTV% drops to 50% for 2020 a much healthier situation.
I decided to assume rents for city centers have to continue to reduce, as working from home trends continue, and rents are likely to keep falling. (see table below)
Sales and share count estimate from 2019 to 2025.
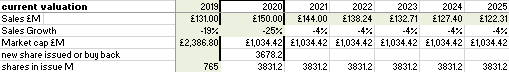
Valuation model
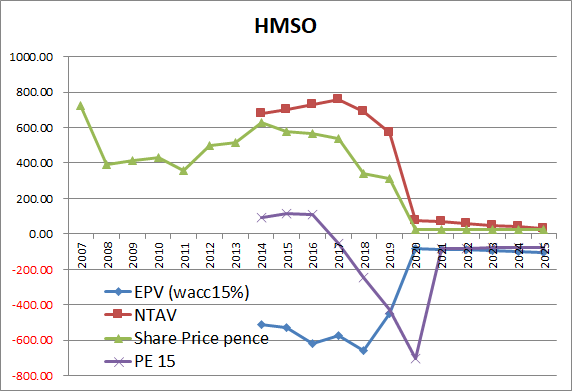
With a 27p share price and 2020 NTAV of 77p, there looks like an attractive upside if rents and valuation do not continue to fall further.
If my expectation that rents will keep falling occurs what happens to valuations?
By way of example, a 4% year on year fall in rent and valuation would reduce NTAV by ;
Year - NTAV, 2020 - 77p, 2021 - 68p, 2022- 59p, 2023 - 50p, 2024 - 41p , 2025 -32p etc etc
It far to risk for me to consider investing, but others may have a different view. (I hold no position)
DYOR
BSV
Refinance 3rd Sept 2020
Hammerson (LON:HMSO) announce the right issue and property sale. Key facts include;
- Proposed rights issue and to raise gross proceeds of approximately GBP552 million
- Propose a share consolidation for 5 to 1
- the sale of substantially all of the Company's 50% interest in VIA Outlets ("VIA") to a mutual fund managed by APG Asset Management N.V. ("APG") for estimated cash proceeds of approximately EUR301 million (equivalent to approximately GBP274 million)
- Following the completion of both Transactions, the Group's net debt would reduce to £2.2 billion on a pro forma basis as at 30 June 2020 and LTV would fall to 41.7% on a fully proportionally consolidated basis
This will raise £825M in total (net £794M after expenses)
Mass dilution. The consolidation and issue will mean approximately 3831 million shares in circulation with each newly issued costing 15p in the new share currency. (In old money each new share cost 3p.)
NTAV after the dilution and consolidation is approx 68p for 2021(~15p in today's money) according to the model below. )
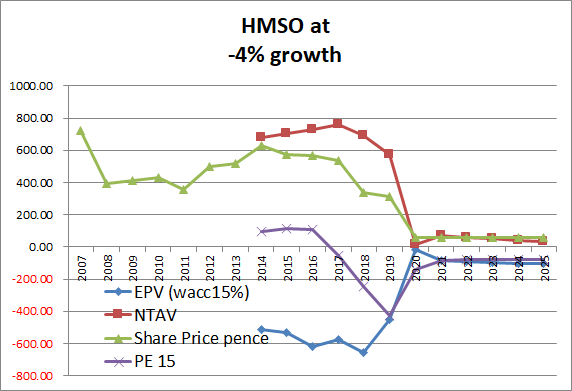
Is it worth participating in the rights issue?
There's probably more pain to come if property valuation and rents continue to fall.
(I hold no position in Hammerson (LON:HMSO)).
DYOR
BSV
Revolution Bars (LON:RBG)
Has seen a price decline from 205p in July 2015 to 15p today.
Unpicking today's update is impossible(3rd sept 2020). I can only imagine management would have been better of saying nothing.
With sales still down even with the 'help out to eat out the scheme', I can't see the business recovering anytime soon.
I've updated the numbers below and concluded they will need to raise more cash. (see numbers and model below)
The table below provided a sales recovery profile, with a partial recovery in 2021 and 2022.

The Model below does show no recovery in the business.
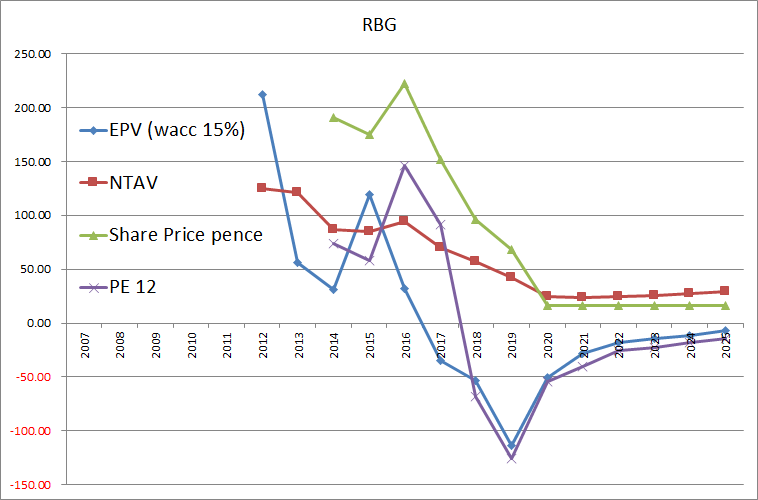
With lockdowns still possible and an end to furlong, sales could be a lot lower. All the minimum wage increases could make costs much higher. With more pain to come and not enough more funds need to survive it a complete basket case to invest at this point.
With the growing debt pile and revenues not recovering soon new funding will be required in 2021.
(I've ended my short position)
DYOR
BSV
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
27 comments
Revolution Bars (LON:RBG)
FXXkME more dilution, good luck holders with this dog.
BSV
Good analysis of BigDish. There are a few out there like this. Toople LON:TOOP is another example of a company that announces contract wins then tries to raise money. No doubt the directors do very nicely.
Hi Steve,
If only they could win contracts that pay money. What they say is just too funny. The last comment being
'The Company is confident that this amount along with the balance of the short term funding will be more than adequate to stretch the funding runway beyond the end of the second quarter of 2020.'
Did that not happened 4month ago.
Let hope too many people did not get caught up with the pumping of the stock.
All the best
BSV
Tricorn (LON:TCN) added
BSV
Quiz (LON:QUIZ), Seem like my -38% sales forecast in the report was optimistic(see above report). the business seems in terminal decline due to a poor proposition to the retail consumer.
DYOR
BSV
Bigdish (LON:DISH) updated.
BSV
Pci- Pal (LON:PCIP) added
I model how turnover rents might affect companies like Quiz (LON:QUIZ), using information from fashion united. I don't think it removes risk from poorly performing businesses but would help for a second lockdown. Recommend you read the update and come to your own conclusions.
BSV
Hammerson (LON:HMSO) updated
How about Newmark Security (LON:NWT) and M Winkworth (LON:WINK) ?
Hi Herbie47,
I did not get time to look either in detail but Stockpedia rates them well with a stock ranking of 85 and 97. Again wish you luck if you hold them.
As for $QUIZ, I'm not even sure finance director's with their double enter maths can be sure of the outcome for this company.
All the best
BSV
I don't hold any of them. I just went by the biggest fallers on Stockopedia list. To me they are the dogs of the day.
OK cool,
We are just looking at different things.
BSV
Quiz (LON:QUIZ) added to Dog of the Day.
BSV
Shares are up 5%?
Let bring out the champagne.
Hardly dog of the day then?
OK, it just an opinion.
Good luck with your investments.
BSV
Herbie, BSV has an agenda.
Thanks, Bryans,
Please feel free to fully express what you want to say.
If anyone really wants to know why I write this. Well, it simples it my method of looking at the detail to understand if to invest or short a position. I share the information with others out of a desire for civic duty.
BSV
RBG updated
As Churchill said:
"I cannot forecast to you the trajectory of BigDish. It is a riddle wrapped in a mystery inside an enema; but perhaps there is a key. That key is BigDish bullshitting ability. It cannot be in accordance with the interest of the future of BigDish that Deliveroo, Just Eat, Uber Eat should plant themselves in the way of BigDish's inevitable glory. That would be contrary to the historic investor duping interests of BigDish....so they'll pivot into some other hair-brain quarter-baked plan and dip the gullible for some more coin"
#GiantPish
Very funny mojo. First genuine laugh today.
Very amusing coverage of DISH. What are you basing your forecasts in the graphs on?
50% growth in users' number and cost to acquire them.
Bigdish (LON:DISH) covered
Revolution Bars (LON:RBG) covered