Small cap hire companies: bargain or buyer beware

Two things piqued my interest in the small cap hire sector. The first was that HSS Hire (LON:HSS) featured in the screen results from my Price-to-Sales screen. The second was that, since COVID hit, all of the small caps, Andrews Sykes (LON:ASY) HSS Hire (LON:HSS) Speedy Hire (LON:SDY) and VP (LON:VP.) have massively underperformed Ashtead (LON:AHT) , which is the behemoth in the sector:
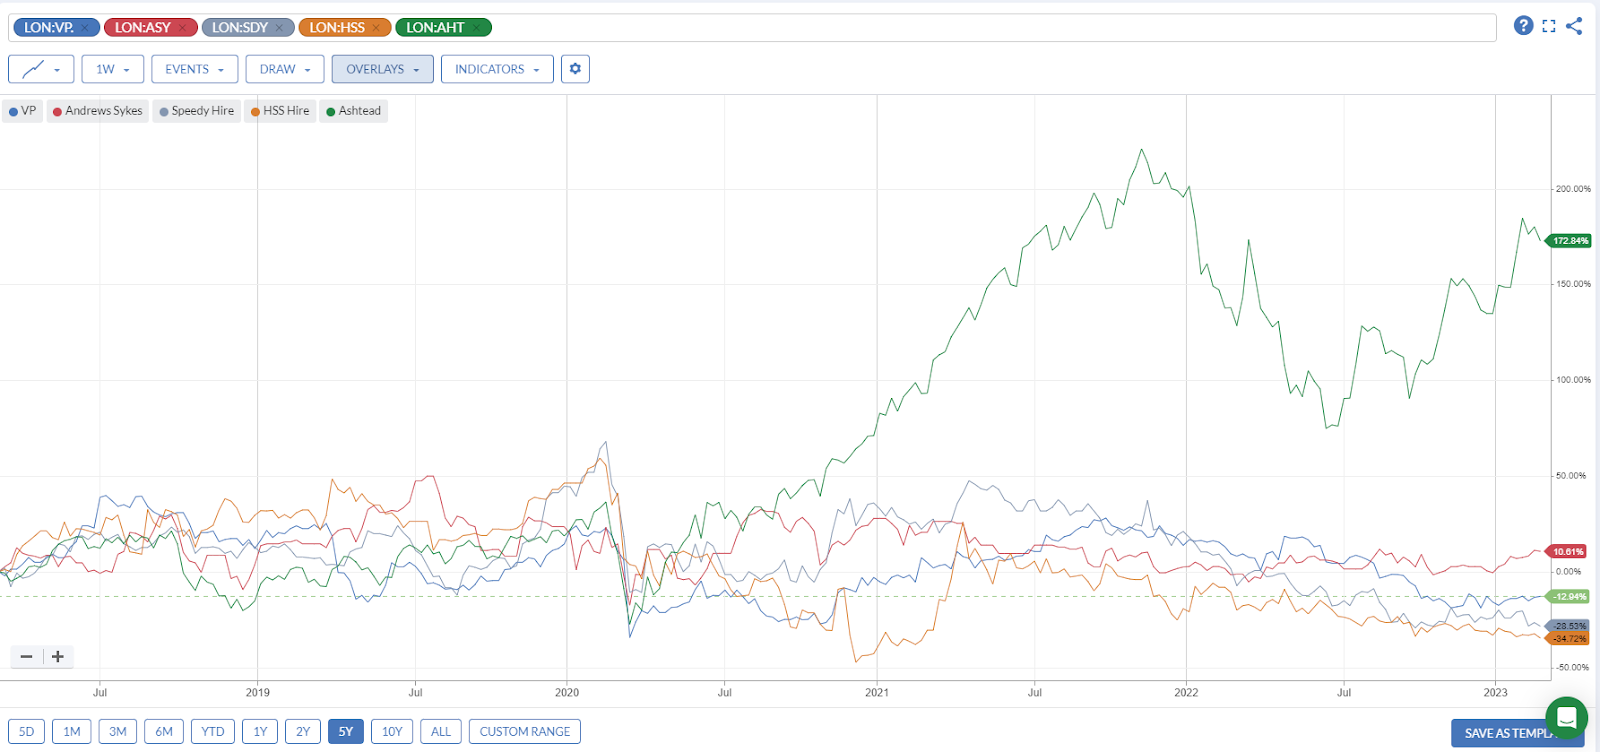
The majority of Ashtead’s business is in the US, so this isn’t a direct comparison. (Although several of the smaller firms have US, European or Middle Eastern operations too.) However, it is clear that there has been a step change in the perception of the businesses post-COVID, with Ashtead now trading at a significant premium to the smaller listed companies:

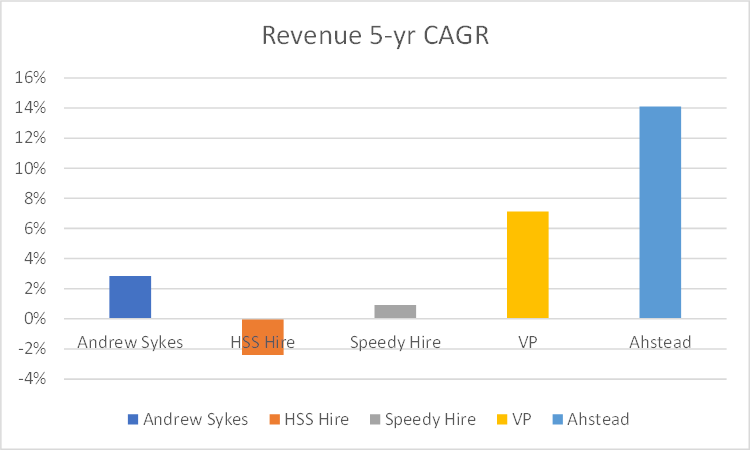
Part of this is justified. Ashtead has had much better revenue growth over the last five years:
The story for EPS growth is the same (excluding HSS Hire (LON:HSS) , where the figures are flattered by a poor starting year):

However, if brokers’ forecasts are to be believed, the picture going forward is more mixed:

And further into the future:
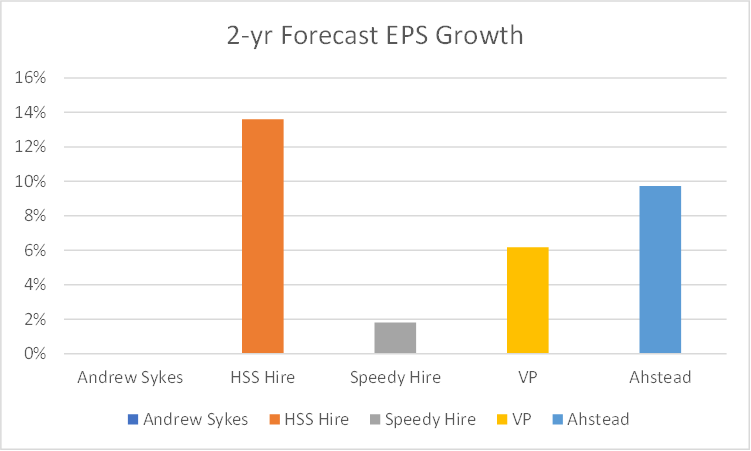
(Andrews Sykes has no broker forecasts, hence the lack of values.)
It is only worth paying a high multiple for a company if it will grow earnings rapidly in the future. While history may provide a guide to which companies can do this, the value investor tends to bet on mean reversion over the long term rather than continued momentum. If the rating disparity closed in the future, it would benefit these smaller companies.
In many industries, such as recruitment, the larger companies generate higher margins and are much more highly rated by the market because they benefit from network effects. However, there doesn’t seem to be the same effect at play here. AMA Research describes the sector as” extremely competitive and relatively fragmented”. For example, Statista shows that in 2021 Sunbelt (i.e. Ashtead) had just a 9% UK market share, with Speedy Hire at 7% and HSS Hire and VP at 6% each:

Since other companies make up 72% of the market, there is plenty of scope for any of these listed businesses to take market share if they execute well. But, equally, a poor performer will lose market share and scale.
In addition to size differences, there is another reason these companies may be justifiably cheap: they currently face a headwind in the UK residential construction market. This doesn’t explain why Ashtead bucks this trend, however. If anything, US residential construction looks more exposed to rising interest rates than the UK. In addition, many of the housebuilders have bounced far more strongly than the hire companies in the last three months:

HSS Hire and Speedy Hire are the worst performers over this time period. Andrews Sykes and VP are in line with the worst-performing housebuilders. This makes me think it is worth looking into these in more detail.
Profile
Andrews Sykes (LON:ASY)
The company traces its history back to 1857 when Henry Sykes formed Sykes Pumps, designing and manufacturing many pumping and winch solutions over the proceeding century. The other side of the business started as Andrews Industrial equipment when John Andrews bought several US-manufactured steam cleaners and portable heaters to sell into Europe. After demand from a business associate to borrow one of the heaters, John decided it was a better model to hire out the equipment instead. Demand for this service was high, and the company grew rapidly. In the 1980s, both companies were acquired by Braithwaite Group and combined to form Andrews Sykes, a specialist hire company. Non-Executive Chairman Jacques-Gaston Murray acquired a controlling stake in the company in 1994. It was listed on AIM in 2001.
Being a specialist hire company means that Andrews Sykes has a very high gross margin of over 60%, which leads it to have a much higher and more consistent Return on Equity versus the other hire companies.

This suggests the company has a strong competitive advantage in its niche as it is the place to hire specialist pumping, heating or air conditioning units. However, revenue growth has been hard to come by recently, suggesting that the company is the victim of static end markets:

These tend to follow fluctuations in extreme weather events, too, since flooding causes the need for more pumping and dehumidifying. In contrast, extreme cold means more demand for portable heaters.
The company is exceptionally tightly held with just 9% free-float:

Tristar Corporation is controlled by the trusts of Jean-Pierre and Jean-Jacques Murray, the sons of Chairman Jacques-Gaston Murray. Being a family-controlled company means this has quite a following amongst a particular type of value investor. The risk, of course, is that external shareholders can have little influence on the company. For example, this indifference to the market is reflected in the lack of broker forecasts.
HSS Hire (LON:HSS)
HSS Hire is also a company with a long history. Bert Taylor started it in 1957 as the UK’s first dedicated hire shop. Following a merger in the 1960s to become Hire Service Shops Ltd., the company grew organically for the next few decades. Then in the 1990s, an industrial owner and then a series of private equity owners drove the Group to expand to become the national chain it is today. The company was floated on AIM in 2015. As with many Private Equity floats, it has not been a magnanimous start to listed life:

The combination of £173m of bank debt and initial losses has been a toxic combination:

This led to a £13m placing in 2016 and a £54m raise in 2020. That now appears to have rebuilt the balance sheet, but at the cost of massive dilution to existing holders:

However, the more robust balance sheet combined with strong 2022 trading and forecasts for a profitable 2023/4 means that this is finally worth considering as an investment:

Speedy Hire (LON:SDY)
Speedy Hire started as Livesy Hire in Wigan in 1977 by John Brown. The Speedy name comes from the purchase of Speedy Fixings Power Tools in 1982. The company has grown organically and via the acquisition of other plant hire groups. The company was listed on the Main Market in 2003. There was press speculation that they would combine with HSS Hire in 2015, but the company denied this.
The company aims to be a first-mover in its industry and to take advantage of this. For example, the company has been keen to develop technology solutions and make their hiring process primarily digital, saying:
We are utilising technology to improve the customer and user experience through closely reviewing the customer journey, including on a digital basis, from point of enquiry through to delivery, collection, invoicing and cash collection.
Perhaps more importantly, Speedy Hire has operated without issuing shares, apart from share options, since they were forced to have a rights issue in 2009.

Directors have been consistent buyers recently:

The incoming CFO, Paul Rayner, has bought shares since his appointment in November 2022, although in relatively small amounts. The CEO of seven years, Russell Down, retired in August 2022 and was replaced by COO Dan Evans. Mr Evans has yet to buy shares in the market.
The changing of the guard appears to have uncovered a serious issue at the company. On 8 February, the company reported that:
Following recommendations made at the end of the audit for the year ended 31 March 2022 and as part of the subsequent work being undertaken by management to review controls around hire equipment, the Group has recently carried out a comprehensive count of all hire equipment in preparation for the upcoming 2023 audit.
The majority of the company’s assets have unique identifiers, and the audit found no issue with these, however:
…other equipment such as scaffolding towers, fencing and non-mechanical plant which does not have a unique serial identifier and is not tracked on an individual asset basis (“non-itemised assets”, representing 22%, or £49.9m, of the total reported net book value)…[the count found] a deficiency in the value of non-itemised assets of c.£20.4m.
It is unclear whether this is due to fraud or inattentiveness on the part of employees in tracking returned equipment. However, this is not a good scenario to find almost half of this equipment is missing. Clearly, additional checks and balances need to be put in place. However, the market cap dropped by £25m in response to the news, more than the value of the missing equipment. If this issue is now resolved, then this could be an overreaction.
VP (LON:VP.)
VP is another tightly held share, with Chairman Jeremy Pilkington controlling 50.33% of the shares. A holding of this size means that minority holders are along for the ride and are unlikely to be able to have a major influence on strategy or direction. This is another company with a long history, dating back to 1954 when it was formed as Vibratory Roller and Plant Hire (Northern) Limited. It floated on the Stock Exchange in 1973 as Vibroplant. The company re-launched as Vp plc in 2001 following the move away from general plant hire to more specialist equipment rental. At least ten acquisitions have followed in the intervening years. This is another company where the share count has been static. Indeed share buybacks over the years have seen the share count decline slightly:

The CEO, Neil Stothard, has been with the business for an extended period of time. He was first appointed to the Board as Finance Director in 1997 and became Group Managing Director in 2004 and subsequently Chief Executive. They have a new CFO. Anna Bielby was appointed in January of this year, having previously been CFO of KCOM and Lookers.
Mr Stothard owns over 2% of the business, which aligns his interests with shareholders. However, almost all of this is from his exercise of share options after selling to pay costs. He appears to have put little of his own capital in over the years:

The company tried to sell itself in August last year, but it seems the offers were not at a level the Board could accept, and it continues as a stand-alone business.
Competitive Advantage
The Stockopedia algorithms rate these as high-quality companies:

However, this isn’t just a story about margins, which vary significantly between the companies:

The specialist nature of Andrews Sykes pumps, heaters and air conditioners leads to consistently higher margins, but at the expense of the inability to deploy fresh capital at these high rates of return. For the rest, they are unlikely to have particularly strong moats. VP has slightly higher margins than HSS Hire or Speedy Hire. However, none of these three compares particularly favourably with their cost of capital. While the cost of debt was low, and the companies could finance asset purchases secured on the equipment at low spreads to low interest rates, these returns of capital may have made sense. Less so in a rising rate environment.
While the margins don’t scream quality, the high quality ranks indicate that these don’t appear to be financially distressed, are unlikely to be manipulating earnings, and have a reasonable health trend as indicated by their Piotroski F-Scores.
Growth and Profitability
Historically, VP has had the fasted revenue growth, with Andrews Sykes the laggard:

However, if forecasts are to be believed, HSS Hire, Speedy Hire and VP will all have similar growth rates going forward. When it comes to net income, Andrews Sykes has managed to grow net income despite largely static sales:

Net income for HSS Hire has been very erratic, although the overall trend of improvement is strongest. VP has been consistent in its profitability (barring the unique events of 2020). However, its growth rate in sales has not fed through to rapid growth in net income, suggesting a lack of operational gearing.
Balance Sheets
The Altman Z-scores for these companies suggest that some caution is required regarding their financial strength. As does the current ratios for all of the companies apart from Andrews Sykes:

However, I am more sanguine about the low current ratios for companies in this sector compared to other businesses for two reasons. The first is that the companies tend to require very little working capital. They mostly get paid up-front by customers or billed on short terms, and the major costs are wages and rent, utilities etc. Their hire equipment is funded by long-term debt secured against it. The second is that their capex is almost entirely discretionary, replacing worn-out equipment or buying new equipment to grow sales. In a downturn, these companies can just turn off their capex and run the business for cash. This isn’t sustainable in the long term, of course. However, it means the companies have far more free cash generation flexibility than the average business. They are not immune to extremely negative market conditions, as 2008/9 shows. However, this does make them relatively secure.
Dividends/Buybacks
All these companies pay a reasonable dividend, with Speedy Hire leading the pack:

Investors need to be wary of high dividend yields in companies facing headwinds in their end markets. This can often be a sign of an upcoming dividend cut. However, Speedy Hire also has an ongoing share buyback in place, suggesting that the management feels the dividend is sustainable.
Valuation
Both the P/E and EV/EBITDA suggest that HSS hire, Speedy Hire and VP offer good value at the moment. Assuming forecasts are to be believed, HSS Hire offers exceptional value on an earnings basis:


Speedy Hire stands out on a Price to Tangible Book basis:

Note that I’ve had to update this figure manually compared to the StockReport value due to the issue with the missing stock described above, which occurred between balance sheet reporting periods. However, this takes the P/TBV from 0.89 to 0.97, remaining just below one. At the May 2021 peak share price for Speedy Hire, the P/TBV exceeded two. At a previous low point over the summer of 2016, it bottomed out at just under one. So this is cheap on this metric compared to both peers and its own history.
Risks
The most obvious risk to investing in this sector is that a prolonged economic contraction in the UK and significant falls in house prices mean fewer building and DIY projects are commissioned. This would mean much lower demand for the equipment these companies provide for hire.
Speedy Hire has also neatly demonstrated one of the major risks here. Companies need robust stock procedures to ensure that claimed equipment really exists and is functional. Where these checks are not sufficiently in place, the companies are at risk of fraud or negligence from their staff.
Recent Trading
Despite their issues with missing stock, Speedy Hire have confirmed this month that trading is in line with expectations:
The Group continues to perform well in the second half, with its revenue (excluding disposals) for the four months to 31 January 2023 up c.16% against the corresponding period in the prior year and apart from any effects of the asset loss described above, the Board continues to be confident in delivering underlying profit* in line with its expectations for the full year.
While there has been some drop in broker forecasts over the last six months, this has been a relatively minor reduction compared to many trading companies during this period of inflation and supply chain disruption:

It is a very similar story at VP:

At their interim results announcement in November, they also confirmed they expected to be in line with these expectations. It is the same for HSS Hire, although they haven’t made any announcements since the End of September. The single broker and lack of change of forecasts here mean that this is perhaps more uncertain:

Andrews Sykes has no broker forecasts and also last reported in September when they said:
The second half of the year has started resiliently with record temperatures in the UK and Europe positively impacting demand for the Group’s air conditioning units and chillers. This increased summer demand leads management to be optimistic over the full year results. In the longer term, management remains optimistic that the business will continue to improve but are mindful of the current economic climate and the impact that heightened energy prices, inflation and recession risk can pose to the business and customer demand.
So again, the short-term outcome here looks highly uncertain but was aided by the scorching late summer weather.
Sentiment
Although the momentum ranks are not terrible, they will not be attractive to momentum investors:

Any momentum the companies have in their business performance is let down by the underperformance of all but Andrews Sykes on share price versus the general market:

While the weak sentiment that causes a divergence between expected business performance and share price performance will not attract momentum investors, this is often the type of play that attracts the value investor.
Conclusion
In truth, all of these companies have attractions to the value investor. Andrews Sykes is a stable, cash-generative family business with a niche offering, but it is highly illiquid and lacks growth. HSS Hire looks exceptional value on an earnings basis. Speedy Hire stands out by trading at Tangible Book value, meaning that the value of the business is entirely underpinned by the value of the equipment it owns. Finally, VP has higher margins and higher historical revenue growth, marking it out as a higher-quality company. The sector is not without risks, given the likely impact of higher rates on house prices and housebuilding in 2023. However, the stock market is forward-looking, and housebuilding companies have started to recover over the past few months. In contrast, the share prices of these companies have yet to bounce significantly. So each of these companies is attractive in its own way. However, none stand as the single best value share in the sector. Therefore, the value investor looking for a recovery play is best off taking a portfolio approach and holding all four.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

8 comments
Thanks for an excellent analysis of the sector. Still think that VP Group looks a likely takeover target. Although the group abandoned its formal sales process last Summer, my hunch is that Pilkington and Stothard, the ceo, had wanted to take the company private, something they had tried to do several years ago, and may yet return for another go if the VP share price remains depressed.
One straw in the wind is that Simon Knott’s Rights and Issues Investment Trust (RIII), which has a reputation as a smart long-term small cap investor, increased its stake in VP by 80% to 2.45m shares last Spring. It now controls just over 6% of the company (accounting for 11.78% of RIII’s portfolio) and is the biggest non-family shareholder.
This was prescient - HSS Hire (LON:HSS) up 14% today!
In many industries, such as recruitment, the larger companies generate higher margins
This might be true in other industries but, as far as the recruitment industry goes, you could not be more wrong. Sorry to put it so bluntly but the big listed recruiters operate on much lower fee percentages and generate operating margins around half the level of the strongest unquoted businesses.
I'm sure you are right, I am only aware of the quoted businesses where the opposite is true. I expect if you have a profitable, high -margin niche recruiter set up as a partnership then you keep quiet and don't list it. So only the listed small cap recruiters end up being the poor ones.
The first part is certainly true in that privately owned, high quality boutiques are highly profitable. But the smaller listed recruiters have low margins because they are typically in the most price sensitive market segments and employ the lowest grade of consultant in a negative spiral of declining performance. In other words, they are a bit crap - but not because they are small.
good article as always. i own Andrews Sykes to declare biases but just to highlight they have paid quite a lot of special dividends lately so even if they have normal c.12p final divi for FY22, the yield in the year is c. 8% given the special dividend at the interims. i think there's a fair chance of a bump too at half year given weather in both july/aug and december but this is speculative and biased of course. growth is hampered to a certain extent by re-investment risks but if one believes that extreme weather will become more likely they will be busier over the next few years with the same stock and shld extract some operating leverage..
Good point on the yield. What I don't understand with Andrews Sykes (LON:ASY) is how they manage to retain such a high ROE, surely their moat is relatively weak. What is stopping one of the other businesses starting a pumps, aircon, heater hire subsidiary? 60%+ gross margins is a lot to go after if you own an existing hire business. Habit, brand and reputation will be part of it, but surely a lot of business these days is googling "space heater" when you need one! yet the ROE remains fairly consistent.
I think the pumps biz is a lot trickier to break in to tbh.. quite specialist and ad-hoc.. the balance of the business means they can justify a reasonably wide geographical footprint. it also makes them a bit better at more ad hoc project work which they flag a lot in their blog. they really capture a lot of unexpected biz from weather events as far as I can tell