Small Cap Report (10 Apr) - DEMG, PRZ, IDH, VER

Events/Publications
Firstly, WH Ireland publish an interesting shares magazine every month, called WHI-Spy, which contains news & views on shares.
I find it an interesting read, and hence am happy to pass on the link here each month when it's published, so click here to read the April 2013 edition (no registration required).
Secondly, Master Investor have contacted me to offer some free tickets to readers here, which I'm happy to pass on. Click here and enter promotional code PP2013 to take up this offer. It's on Sat 27 April, in Islington, London. I shall be attending, so hope to see some of you there during the day. The blurb for the event is;
Master Investor 2013 will be held at the Business Design Centre in Islington, London, from 9am on Saturday 27th April. Organised by t1ps.com and now in its 11th successful year, the show features a unique line-up of top speakers, along with the chance to meet with over 100 top company executives, discuss investment opportunities and gain unique investment insights you won’t find anywhere else. For more information visithttp://www.masterinvestor.co.uk
Pre 8 a.m. comments
There is an interesting announcement from Deltex Medical (LON:DEMG), which is on my watch list following a recent presentation to investors by their CEO. It concerns the granting of a "unique ODM payment code" by the USA Govt, so that physicians will receive automated reimbursal every time they use one of Deltex's products in surgery.
I'm not going to pretend to understand the sector, but based on what the CEO said at the investor meeting I attended, then this sounds like pretty significant news. He asserted that their product improves results from surgery by bettering monitoring fluid levels in the patient, but that it was proving difficult and slow to commercialise.
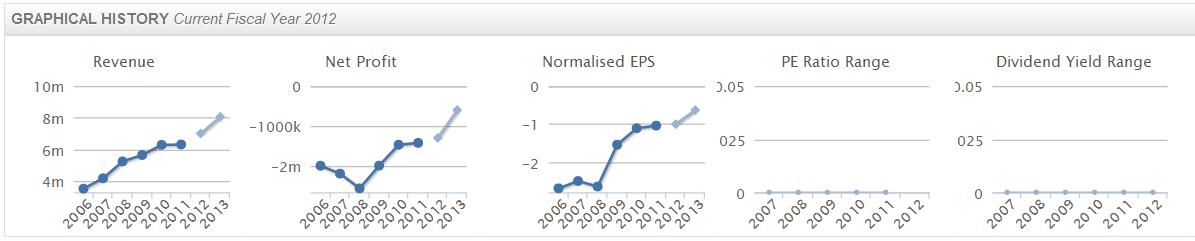
As you can see from the historic revenue chart above (where the lighter coloured lines are forecast), revenue has been stuck around the £6m level for the past four years. Perhaps this deal might give the company the impetus it needs to drive sales higher. It's a fairly high margin product too, so stronger growth could well take them into profitability. I've just bought a few at 14.38p, the £20m market cap does not look outrageous given the positive news today.
I remember being a big fan of shares in pizza/pasta restaurant chain Prezzo (LON:PRZ) a few years ago when they were about 25p. I made a bit of money on them, but they took so long to go up, that when they eventually did I sold out far too early (which is one of my main faults as an investor - not running my winners - always easier said than done though). Here is the five-year chart:

Anyway, my analysis of the company was correct, and the shares are now 84p. Excellent results this morning for the 52 weeks ended 30 Dec 2012 confirm what an excellent business this is. The founders (the Kaye family) have done it before, so very much know this sector inside out, and the business is very prudently financed with a very strong balance sheet, which interestingly (and unusually) includes a fair old chunk of freehold property (£33.8m net book value at 1 Jan 2012 is the figure in the last Annual Report).
Prezzo's results are just great - a quality business this, delivering steady growth despite consumer spending being under pressure. It's a straightforward roll-out, so they opened 31 new restaurants, taking them to a total of 211. I like retail businesses that are expanding at the moment, because they're getting fantastic deals on good sites, at reasonable priced rents, often with large landlord incentives paid to quality new tenants. It just shows how Prezzo's previous caution on new store openings, and prudent balance sheet financing, has proven very wise in the long run.
I'd like to linger over these accounts, as they are just such a pleasure to read - revenue up 17% to £144.5m, EBITDA up 16% to £25.5m, and adjusted pre-tax profit up 11% to £18.3m.
Adjusted EPS is up 13% to 5.9p, so that puts the shares on a PER of 14.2, which is certainly not expensive for such a quality business that is expanding well, has an excellent profit margin, and a very strong balance sheet. Freeholds make up about 17% of the market cap, although of course the lack of any rent on freehold stores mean that those sites boost profits.
I would have no hesitation putting PRZ shares into a very long term portfolio, even though this might not be the best point to buy, after they have already gone up significantly in the last few years. The outlook statement doesn't give any specifics, just saying that they are confident of further progress this year.
Post 8 a.m. comments
It's been an interesting market this morning in Deltex Medical (LON:DEMG), with a nice initial rise in the first few minutes of trading, then a clumsy seller has snuffed out the rise, so it's an unusual situation where we're now able to buy at a barely changed price, despite a very positive sounding announcement. So I've been back three times for more shares - I like an overhang from a seller, as it enables me to buy in whatever size I want, and without having to chase up a rising price. Eventually the seller is cleared, and the price should then move up. In theory, not always in practice!
Next I'm looking at Immunodiagnostic Systems Holdings (LON:IDH). It's a company I looked into in reasonable depth a few months ago, as the shares crashed from a big height when this former growth company suddenly found that new entrants entered the space it previously dominated, and the growth conked out, margins fell, and the shares lost the bulk of their value (follows on nicely from what myself & Ed were discussing in the comments to my article here yesterday).
This is what happens when you get the double whammy of lower earnings forecasts, and a lower PER multiple to reflect it going ex-growth:
On reading their trading statement today, I must admit to being unable to form a view either way, there are too many moving parts to be able to arrive at a quick conclusion. The market seems to like it though, with the shares up 10% to 320p at the time of writing.
The cash generation of £13.6m in the year, and £20.5m closing net cash are very impressive when put in the context of the market cap of £89m (calculated as 28.3m shares in issue, times 313p share price).
It's been a very successful company in the past, so if you think management can turn it around, then the shares could be cheap. If you think more decline is likely, then they may not be cheap. I think it looks interesting, and will try to dig deeper when time permits.
My purpose here is to flag up shares which might have an interesting investment case, for readers to do their own research, and this is one such situation.
Drug discovery companies are not usually my thing, as they take so long to commercialise anything, most projects fail, and they just generally make terrible investments. Plus I cannot verify anything that management say, as I'm not a scientist.
Accounts for Vernalis (LON:VER) caught my eye though, and might be worth a look. The market cap is £100m at 22p a share, but following a big fund-raising in Mar 2012 most of that is cash backed, so they have almost £82m in net cash on the balance sheet at 31 Dec 2012.
Moreover, the cash burn is relatively modest because most R&D spending is recouped from research collaborations & licence income. So they only burned £4.5m in 2012. I'm not sure whether that is expected to repeat, but superficially it looks quite interesting. One assumes the drugs they are developing must have promise, otherwise they wouldn't have been able to raise such a big chunk of money from investors in 2012.
The balance sheet shows a staggering retained loss of £647m! (i.e. the aggregate losses for the whole time the company has existed). I might add this to my watch list & look into it in more detail when time permits, but I like the idea of a speculative drug company which is fully cash funded, as it's usually the repeated fund raisings that dissipate the upside through dilution.
That's all for today. See you same time tomorrow.
Regards, Paul.
(of the companies mentioned today, Paul has this morning taken a new long position in Deltex Medical (LON:DEMG), and has no other long or short positions)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

19 comments
Deltex Medical (LON:DEMG) tipped in today's Shares magazine, alongside two other medical technology companies: Lombard Medical Technologies (LON:LMT) and Consort Medical (LON:CSRT)
Very interesting Edward, nothing like first hand experience and I agree, transparency is everything for us at least.
How does Blur compare with http://99designs.co.uk/ ?
Well the 100% money back guarantee at 99designs looks extremely compelling! We use lots of services like these - they are a wonderful leveller allowing designers the world over to bid for projects. You can find designers on peopleperhour.com , elance.com and lots of other sites who will do work for astonishingly low rates for high quality designs. It's terrifying for professional services individuals all over the world that there are is so much cheap skilled labour competing from abroad.
I presume that Blur's sales pitch is that they are a premium site where you'll deal with accredited designers... but they do say that they have 20,000 designers so they seem to be shooting for the same kind of scale pay day as these other websites but on larger ticket sizes.
I really can't comment on the relative investment merits of these companies though as I haven't done the due dil ! But Blur should definitely provide some kind of money back guarantee for a customer such as us to work with them.
Thanks guys.
Hi Paul and Cisk,
Deltex may well succeed as a company, I wish it and all its investors well.
The following is a simplification and is intended to provide some background information only.
Haemodynamic monitoring
The issue of advanced haemodynamic monitoring is not straight forward. The 'Gold' Standard product used to be the Pulmonary Artery Flotation catheter. Studies like PAC-man did not show a survival benefit in the use of a PAFC in patients. There are some retrospective studies that show a worse outcome if PAFCs are used.
Post hoc analysis of the PAC-man study showed: No overall difference in acute hospital outcome was seen between use of a PAC and no flow measurement (p = .748) or between use of an alternative flow measurement device and no flow measurement (p = .395).
Early goal directed therapy is often quoted as the basis for use of flow directed therapy, particularly in my own specialty of intensive care medicine. The ProMISe study mentioned above is a pragmatic UK replication of Rivers work from ten years ago. Rivers own recent review suggests that early aggressive resuscitation is associated with a reduction in mortality (but it does not suggest that devices such as CardioQ, Lidco Rapide, PiCCO, or the Vigileo have any specific benefit). Conversely, the FEAST study (early aggressive fluid resuscitation in children) seems to suggest that a similar measure increases mortality. I think that the recent FEAST study makes it clear that we do not understand fluid resuscitation as well as we thought we did, particularly in light of the Boldt case. Personally, I remain unconvinced by the evidence produced by Deltex, Lidco, Pulsion and Edwards, but I keep an open mind and am willing to be convinced if better data becomes available.
The Companies
Looking at the devices themselves, the individual companies mentioned above have all commissioned small studies which have looked at selected sub-groups and then the data has been extraoplated to all high risk patients. There has not (to my knowledge) been any study comparing the different devices against one another. There has not been a study of these devices in a similar sample size to PAC-man.
My view is that there is nothing to choose between the devices, except cost and personal preference.
Local purchasing
As to their purchase and day to day use. I am responsible for the purchase of kit on my ICU. As there is no comparative data showing that one device is better than another, the only factor I'm interested in is: 'How much?'
Over the last few years I have used equipment from all the companies mentioned. I am prepared to use any of them, and I trade one off against another to reduce my costs.
There is currently a potential income for hospitals by using these devices. My own Trust will get significant income from a local CQUIN for using them. But that doesn't mean that things can't change. I don't know whether we will have the same CQUIN next year, let alone in 5 years time. AIUI the same applies to the US.
Opinion:
If I was to buy shares in one of these companies, then it would be Edwards Lifesciences. They are the 300lb gorilla. From personal experience, they will let you have a couple of £20,000 units on trial for a year or so to see if you like them! Their turnover for the year to Dec 2012 is US$1.9b.
Hope all investors in Deltex do well and prove me wrong.
Best wishes,
Xig
Hi Xig,
Thanks v much for your knowledgeable input, much appreciated.
I should just mention, however, that the presentation at ShareSoc's Tech. Event was very much focussed on the application of the CardioQ in a surgical setting rather than for ICU. I'm not sure whether that changes much and whether the benefits of using the CardioQ during surgery are more clear-cut than specifically for monitoring/guiding the treatment of septic shock. It certainly seems like a safer/simpler option than PAFC (to a layman!).
Investors should definitely check out competitive threats - especially from Edwards, as you say. I guess the big question is whether Deltex has something better than Edwards' offering, which the latter can't readily reproduce. If they do, then there's a clear potential exit route for investors via a takeover.
Best,
Mark [no position in Deltex]
Nice one on WHI Spy Paul.
re. Deltex Medical (LON:DEMG) the one thing that caught my eye that I forgot to say at the ShareSoc tech seminar was the very serious dilution that shareholders have had to suffer over the years - have a look at the stock report. 13% compounded adds up!
This is my specialist area of medical practice.
Just a note of caution about Deltex Medical (LON:DEMG). They have direct competitors:
Lidco (LON:LID) http://www.lidco.com
Pulsion http://www.pulsion.com/?id=35
Edwards Lifesciences http://www.edwards.com/products/mininvasive/Pages/MinInvasiveHome.aspx
All 4 companies have been pushing their products for years, and the evidence is not as certain as they would have you believe. Each of these companies may be hugely successful, but it is not a done deal. There are a number of large, independent clinical trials, (for example ProMISe ) which are looking at optimising fluid therapy and currently collecting data. I'd be very cautious about any of these companies until these studies start to report.
IMO, the medical device equivalent of BioTech, and hence high risk.
All the best,
Xig
(No position)
Hi Xigris,
Many thanks for that, very interesting points.
Always great to hear from experts in the field.
I think your comparison to biotech (which are blue sky with zero turnover, and a binary outcome) is a bit unfair, as the DEMG products are actually out there & being sold, and generating repeat revenue from the consumables at quite high margins.
As the company mentioned, they could run the business at cashflow breakeven fairly easily if further funding were not available, and it's not actually burning much cash at the moment.
I did wonder about the competitive situation, but didn't get round to asking them about it at the recent investor meeting.
Good to have a reminder though that the picture given by most companies will be a heavily optimistic version of reality! I wouldn't have touched DEMG before this morning's announcement, because it seemed to be taking too long to ramp up sales - if the advantages of the product were so clear-cut, then surely surgeons would be clamouring for, and getting it.
But if they now have a process in the USA where hospitals can get automatic & rapid reimbursement for using it, then that surely must present the company with a significant opportunity to ramp up sales?
Grateful for any further thoughts you have on it.
Regards,
Paul.
Xig, I've followed (and held) Deltex for nearly 10 years now, so feel the company's progress is at odds with the share price. There has been a large seller which has driven the stock down from the late 20s to its current level.
I don't pretend to be an expert in their market, however I do know that there have been a large number of (independent) studies carried out on the Deltex product, the vast majority of which have reported favourably on the benefits of using ODM and the Deltex product.
Do you think that these studies are wrong regarding CardioQ? Are you expecting newer studies to rebuff the evidence from prior studies into the benefits of ODM / CardioQ?
Regards
Cisk
Hi Paul,
Re Deltex:
Thats not quite what their main product does. It monitors blood flows and hence can rapidly and effectively detect reduced flows that can lead to potentially damaging oxygen deficiency during surgery and intensive care.
Cheers,
Mark
Have just come across this short video from Deltex Medical (LON:DEMG) giving some more details about today's announcement.
There's a selling overhang in the market, so it's easy to pick up stock, I've bought three tranches already today. DYOR as usual!
Here is the link to the video
Hi Paul,
Many thanks for the link to WHI-Spy. Looks like a good little read.
I see they tip Utilitywise (UTW) and I was wondering if you have any opinions on that company after the presentation at the last Mello Central. Personally I thought the management talked a good game and presented with enthusiasm but I have doubts about the business model.
Steve
Hi Steve,
Glad you like the WHI-Spy, I thought it was nicely done & worthy of a mention.
Utilitywise (LON:UTW) is one I have mixed feelings about. Whilst the figures look good, I'm not keen on their business model either - i.e. getting paid by hidden commissions from the energy providers clearly creates an enormous conflict of interest.
Although on the other hand, the client is happy because UTW are saving them money, and these are B2B transactions, so all parties are grown-ups & should know what they're doing (much how I feel about the Banks derivatives mis-selling - if you didn't want or need an interest rate swap, then don't buy one!).
So it's on my watch list. I also thought the CEO was flummoxed by some tough questioning, and whilst a nice chap (the one who looked like Michael Heseltine) he somehow just didn't connect with me in the way that I need to buy into something. Can't put my finger on it, just a gut feel.
My view is that there are plenty of pebbles on the beach, so if it doesn't feel right, then I leave it where it is.
Cheers, Paul.
Hope you don't mind me asking this question here but do you have any insight into Blur Groups 10% share fall after publishing what I thought were cracking results yesterday?
sminers - I think that Blur Group is interesting but frankly it's on an incredibly high valuation. If you own a loss making stock valued at 36 times sales, when sales are still tiny, I would argue that you have to accept a lot of volatility in the share price!
I'd never heard of LBITDA before... so it's a new one for the lexicon... http://www.investegate.co.uk/blur--group--plc/rns/final-results/201304090700088625B/
Hi Ed,
Indeed. I usually skim the key numbers of almost all companies reporting each day, quickly compare to the market cap, and make a snap decision whether it's worth looking at more closely & including in my morning report here.
I took one look at Blur's results, saw that turnover was up strongly but still tiny, that losses had actually increased for the year, and that the mkt cap was £30m. So not even remotely within my remit for value-leaning or GARP shares!
So it's one for blue sky investors who like the concept & are prepared to punt on the chances of it succeeding.
Cheers, Paul.
I actually have been in touch with Blur (Group) (LON:BLUR) regarding some work I want done for Stockopedia as we need to improve our exhibition stands! As BLUR is an exchange for designers it seemed perfect - find a dozen designers to pitch for the job and see what comes out.
I put up a brief on the website and it all looked good, but then I clicked through and it needed me to tick the Ts & Cs. What stopped me from submitting it was that I was committing to a 10% 'listing fee'. i.e. about £500 if we were to spend £5k on a project through Blur's exchange. But this fee would be due even if Blur didn't find a designer to take on the project.
Now that might be ok if I had total faith that I was going to receive a dozen bids on the project. But none of the briefs are public, I can't see who the designers on the exchange are (or what their profiles are) and I can't see if anyone is getting any success using the website. Not only that but there are no testimonials or case studies on the website either. It feels very black box.
The sales guy called me and has told me that several companies I know are using the service. He said that the biggest objection he gets from new prospects is exactly what I've just said above - they stumble due to the listing fee and due to the fact that there's no transparency to the other side.
My feeling is that Blur need to radically open up their processes and become a lot more like Ebay - with vendor profiles (even if contact details are kept anonymous) with project histories and ratings. Also I'm not keen on the listing fee at all really and am not sure why its needed. For a company like ours £500 is too much to spend on something which feels like a punt.
To give them credit - they are a young company and the sales guy is planning on sending a bunch of material through - which I will update on this thread - and he says there are plans to increase transparency. The reason I am posting this is - similarly to my thoughts on Globo (LON:GBO) - that it's really important for investors to actually open the box and understand how an potential investment's business actually works rather than just reading PR fluff. The reality is that the £500 listing fee on Blur's exchange is something that a few Google searches makes redundant at the moment for us - and I'm sure there are plenty of others like us.