Small cap silliness: ten stocks that look too cheap

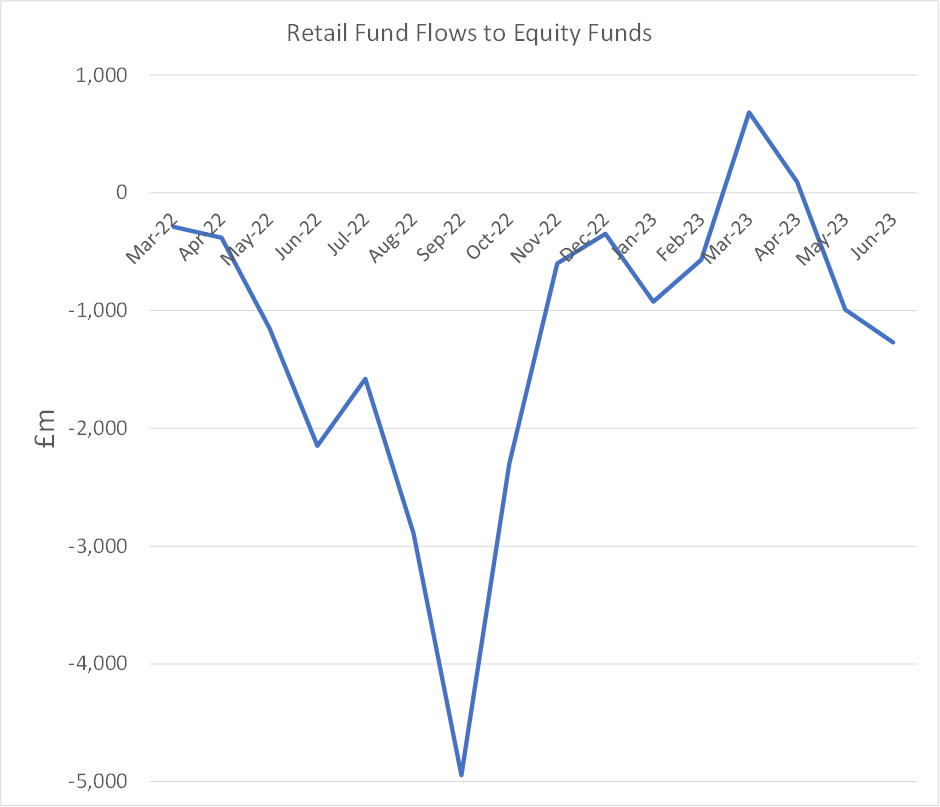
In May this year, I created a screen to look for UK stocks that looked simply too cheap. I picked the midcap space because I believed midcaps would be the first to benefit from any fund flows back into the equity markets. Sadly, those flows have yet to materialise. Indeed, after brief positive flows into equity funds in March and April this year, fund flows have since gone negative again:
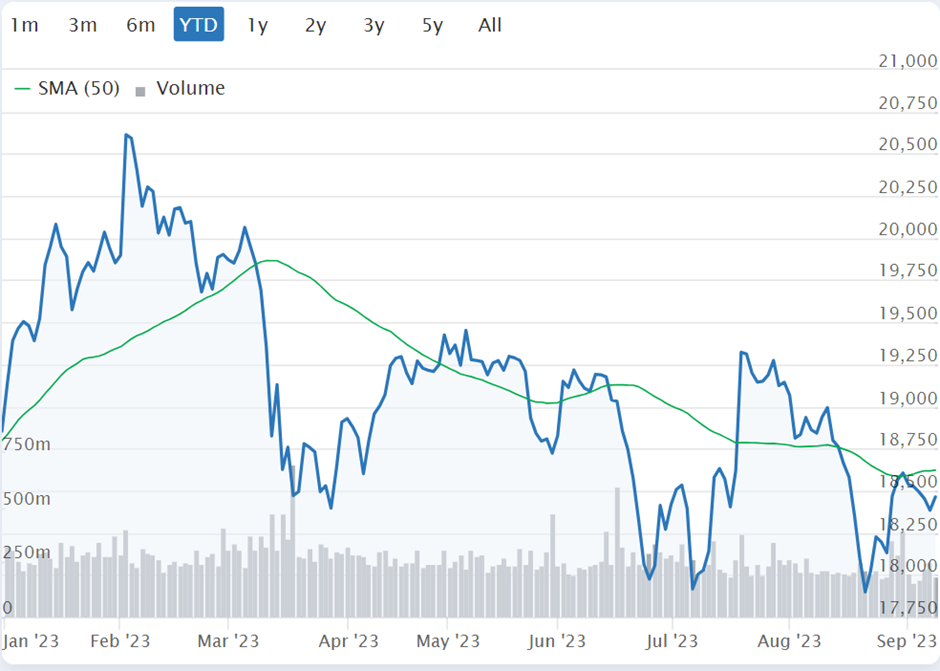
And this is reflected in the rather sickly performance of the FTSE250 since that date:
The narrative remains that the UK is the "sick man of Europe" and is suffering from lacklustre GDP growth and that this makes the UK uninvestable. While the UK has been far from outstanding on the international stage, this narrative misses a couple of key points. The first is that there isn't a positive correlation between short-term economic growth and stock market performance. This may seem counter-intuitive since countries that have won the growth race have also won the stock market race over the very long term. However, when Wharton Professor Jeremy Siegel looked at the data for his book Stocks for The Long Run, he found that when comparing between countries, or time periods within the same country, stock market performance is negatively correlated with GDP growth. [The main explanation for this is a value effect; the fastest-growing countries tend to have stock markets on overly high multiples. However, it may also be a function of the returns going to fresh capital rather than the holders of existing stocks.]
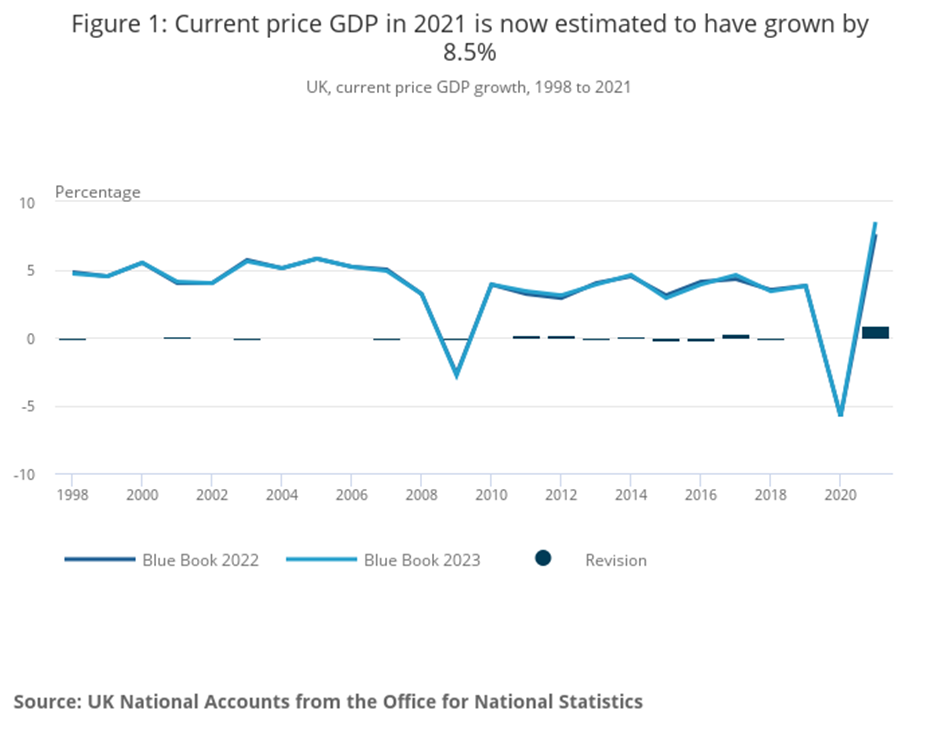
The second point is that GDP estimates are just that, estimates. They are based on survey data and statistical methodologies, and these face significant revisions over time. And one such recent revision paints the UK in a much better light:
The Midcap Madness screen aimed to find stocks that simply looked too cheap. These were the screening criteria:
Price-Earnings Ratio Forecast 1y < 10
I want companies that are forecast to remain cheap rather than one-off inflation beneficiaries.
Dividend Yield Rolling 1yr > 5%
While this isn't designed to be an income screen, a large dividend yield is a sign of companies where the price has declined, but the company retains its dividend payout. This may indicate that company management believes that the company's future is not as bad as the market has priced.
Stockopedia QV Rank > 70
This is a sense check that I am getting stocks with reasonable Quality and Value.
Industry Group excludes "Collective Investments"
I want to look for trading businesses, so I exclude funds and fund-like stocks.
Although I believe midcaps are still a fertile hunting ground for value investments at the moment, I didn't want to simply re-run the same screen since many of the screen results are the same. So this time, I have applied the same criteria to the small cap universe to create my Small Cap Silliness screen:
Market Cap: > £30m; < £300m
The Results
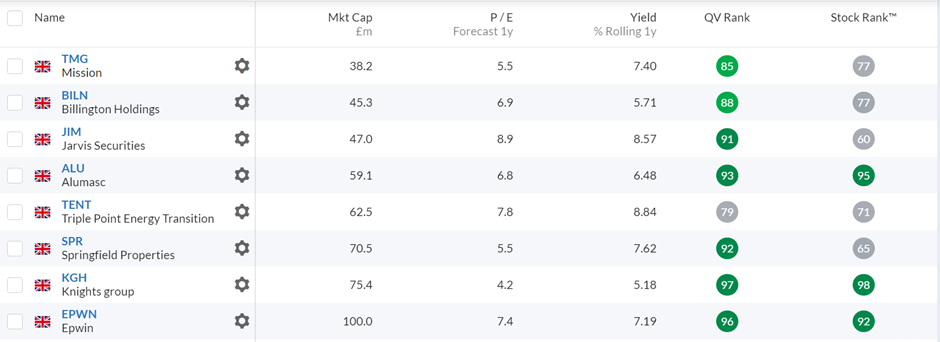
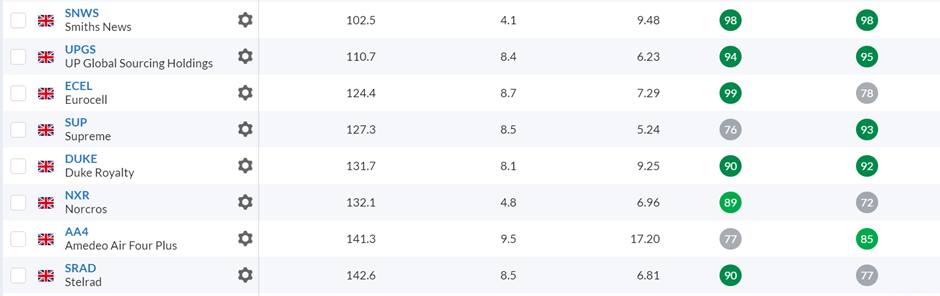
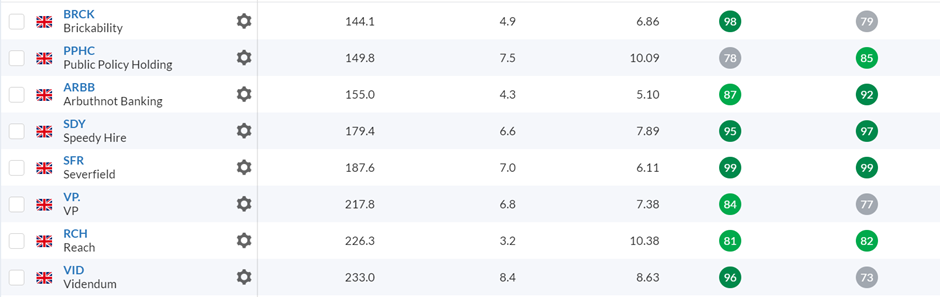
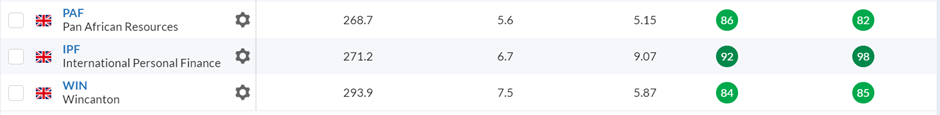
The screen currently generates 27 results:
The Companies
Out of these results, I have picked ten companies that I think are worthy of further research:
Mission (LON:TMG)
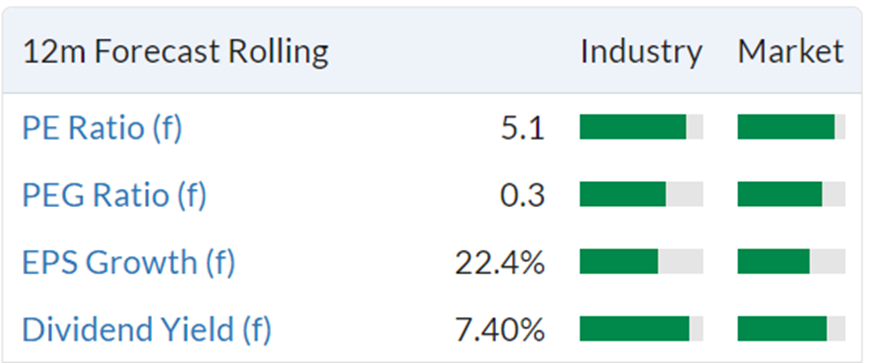
The Mission Group is a collection of digital marketing and communications agencies. As a people business, this will never be highly rated by the market. Even so, a forward P/E of 5.5 and a dividend yield of over 7% looks anomalous:
Of course, a high dividend yield means nothing if revenue and profitability collapse in the future. Investors need to be slightly careful about the revenue forecast here:
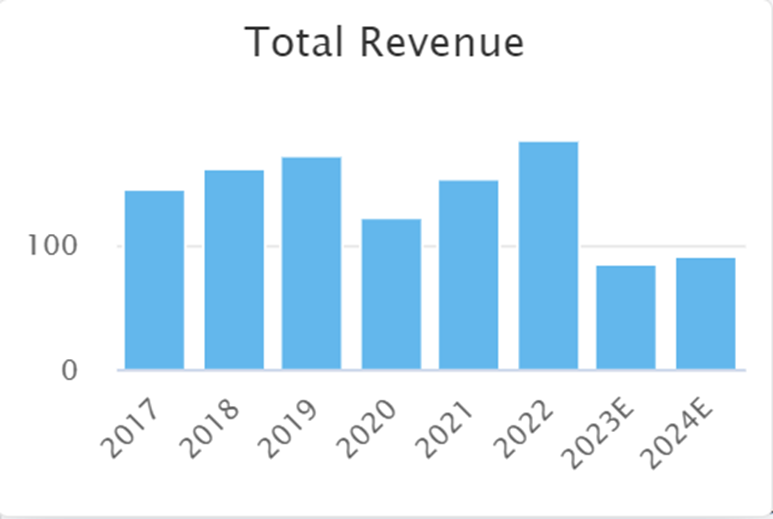
Stockopedia's data provider is picking up the Turnover for historical figures but Net operating income for brokers' forecasts. The difference is due to significant pass-through revenue. The last set of full results shows that, at £84m for FY23, it is forecast to grow:
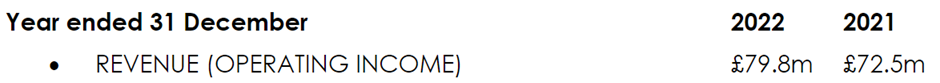
In their last trading statement at the end of July, the company said:
Whilst the Group remains on track to meet full-year guidance, profitability is likely to be at the lower end of the Board's expectations, with profit before tax expected to exceed that of 2022 (£7.8m).
Broker forecasts are unmoved in response:
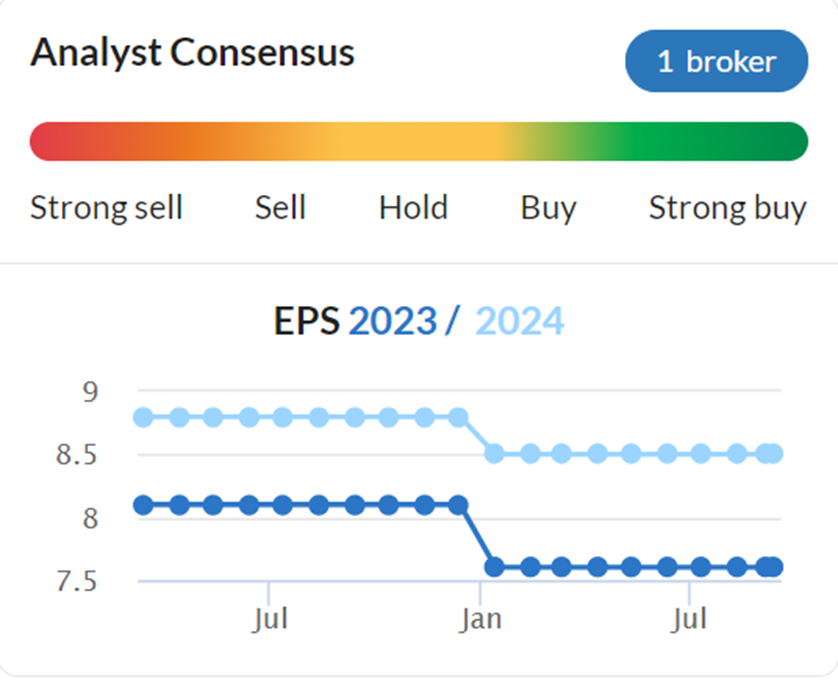
This suggests there could be some risk of a slight miss against expectations, especially with an H2-weighting more pronounced than in previous years. Still, a P/E of 5 gives a large margin of safety.
Billington Holdings (LON:BILN)
Ed chose Billington Holdings (LON:BILN) as an example when he looked at Trending Value stocks in June. Since then, the momentum has faded, and presumably, momentum investors are long gone:
Their AGM statement in June was upbeat:
2023 has started positively for Billington and the Company is trading in line with market expectations. Despite the continuing macroeconomic headwinds, the opportunities the Group are seeing in its targeted sectors remain buoyant, providing optimism for the later part of 2023 and into 2024. We have a robust business with significant momentum and I remain confident in the Group's prospects for the medium and long term.
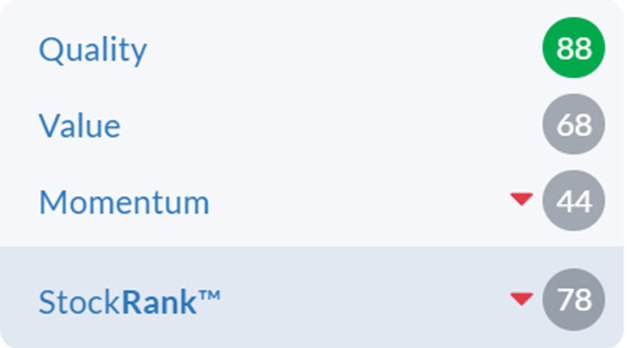
Although this was an inline statement, meaning no upgrade from their broker:
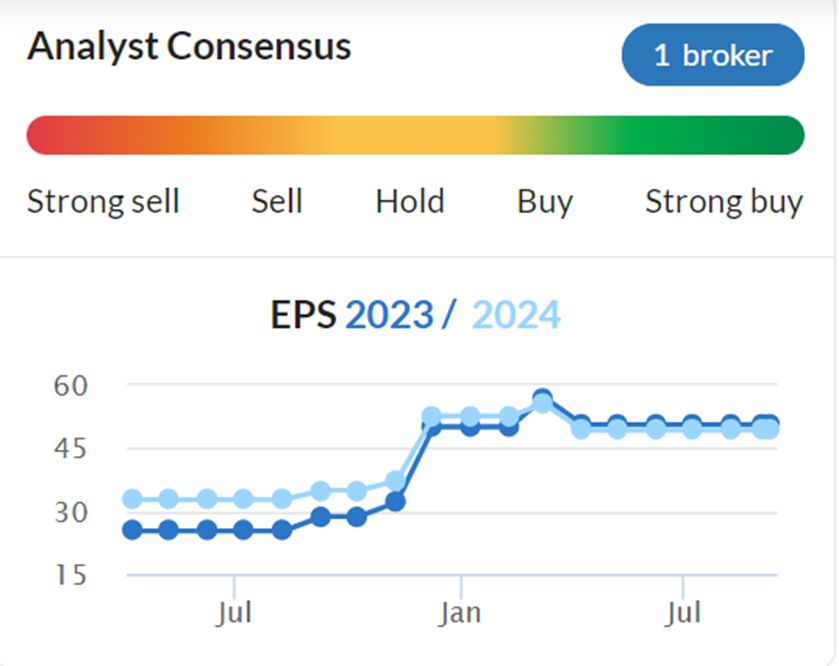
The Value Rank is not outstanding here, but that is partially due to how cheap their industry group has become:
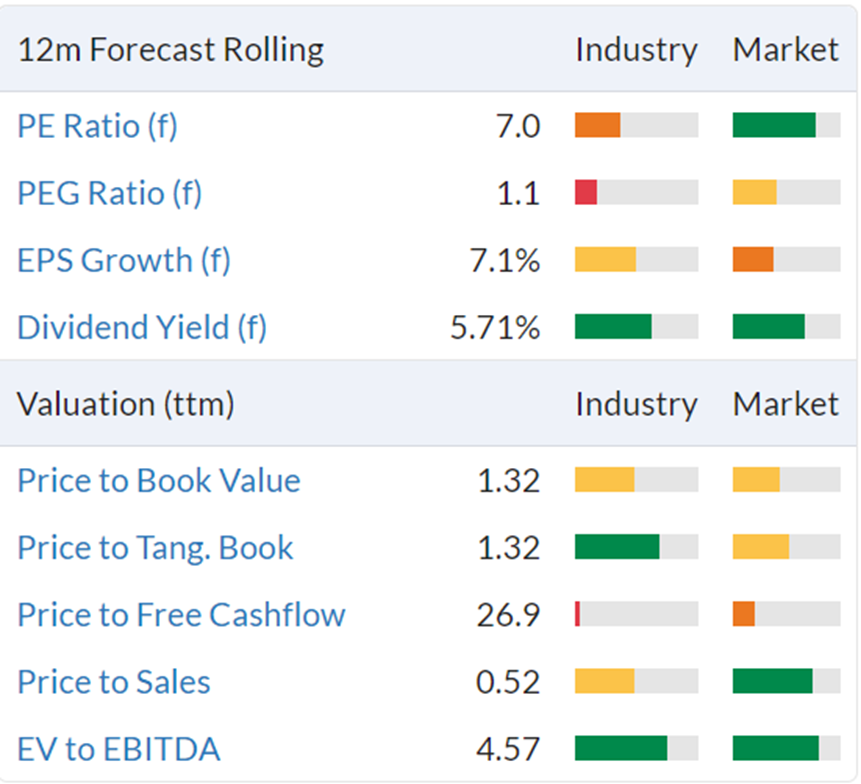
In absolute terms, a P/E of 7 for a company with net cash and a reasonable outlook is cheap.
One risk I am aware of is that, when I met the company at a Mello event in 2022, they had plans for a major European acquisition. Something of this scale would almost certainly require an equity raise. And when they changed broker from WH Ireland to finnCap (now Cavendish Financial following their merger with Cenkos), it seemed that a raise was on the way. This sort of thing almost always happens at a discount. However, no deal or placing has been forthcoming yet.
Alumasc (LON:ALU)
I looked at this company in some detail in July this year. My biggest concerns were around the state of the newbuild housing market and the price paid for recent acquisitions. If anything, the UK housing market's outlook has worsened since then. However, we have also had Final Results from the company. These were okay but not outstanding:
§ Group revenues from continuing operations maintained at £89.1m (FY22: £89.4m)
§ Group underlying* profit before tax from continuing operations £11.2m (FY22: £12.7m)
However, the outlook was not bad:
§ Healthy order book; year started in line with management's expectations…
§ The Board anticipate short-term market conditions will remain challenging, but are confident the Group has taken the right actions to manage these, while the Group remains well positioned to benefit when markets normalise.
Their house broker, finnCap, made no change to operating profit forecasts, although FY24 forecasts fell by 5%, reflecting higher interest costs:
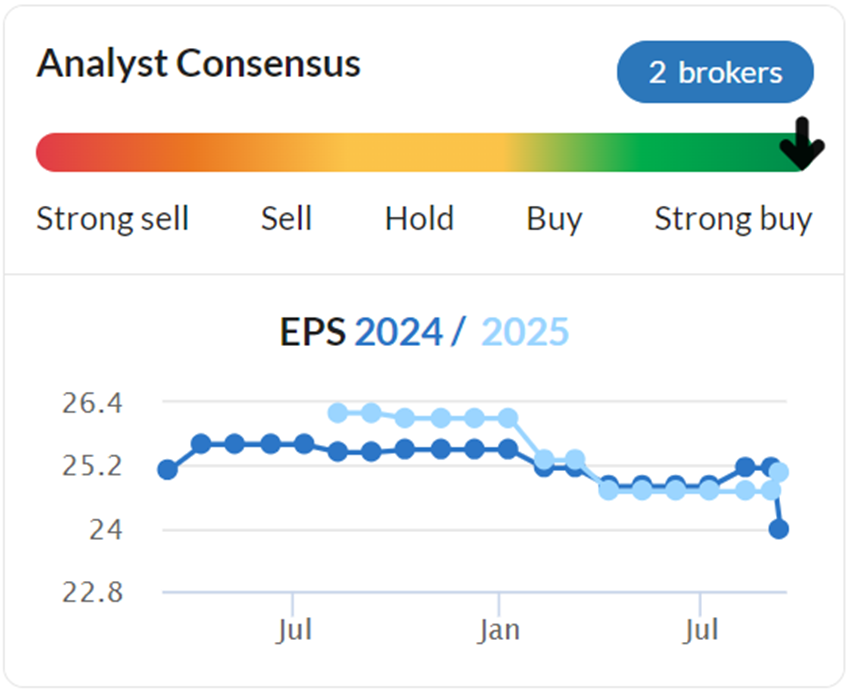
They also say that their "progressive dividend policy reflects Board's confidence in outlook". Actions often speak louder than words when it comes to company results, so it may well pay to trust management on this one.
Smiths News (LON:SNWS)
I wrote up Smiths News as a Stock Pitch in April. Since then, not much has changed, despite in line Full Year Results in May:
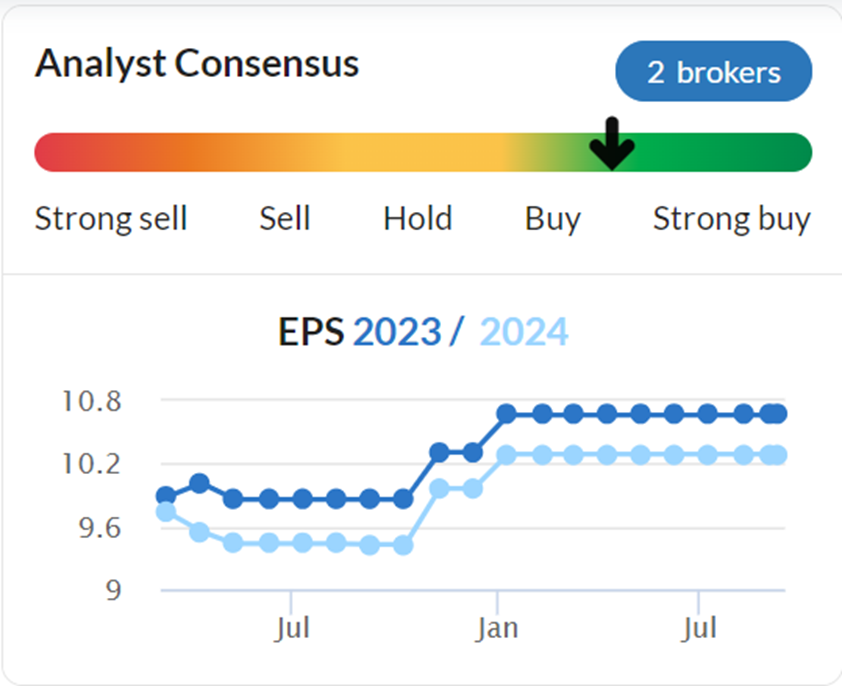
However, the price is cheaper today:
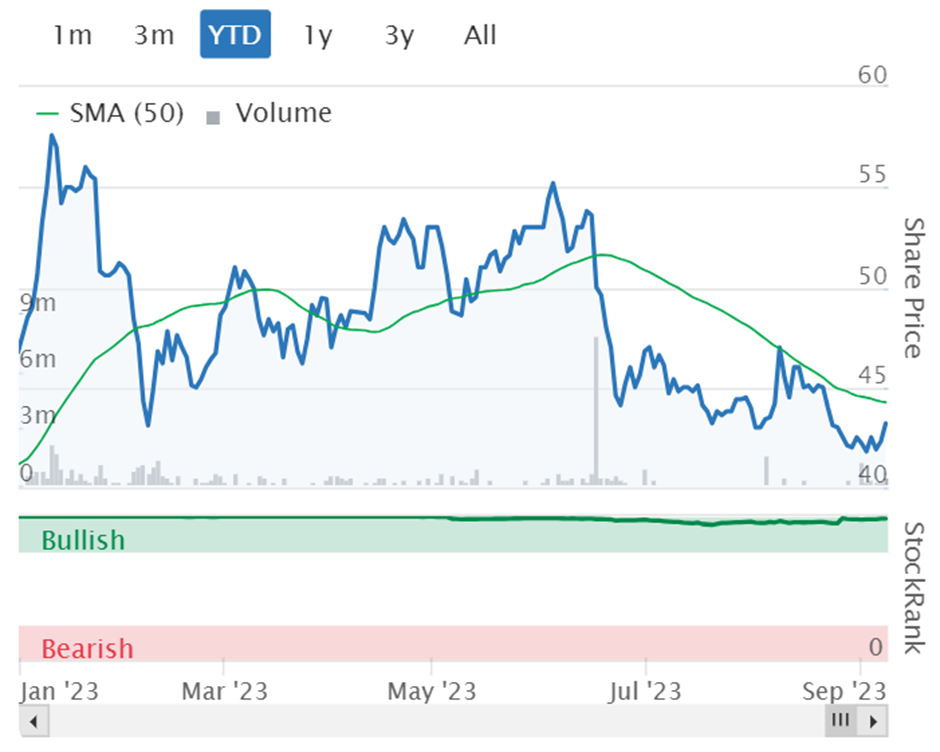
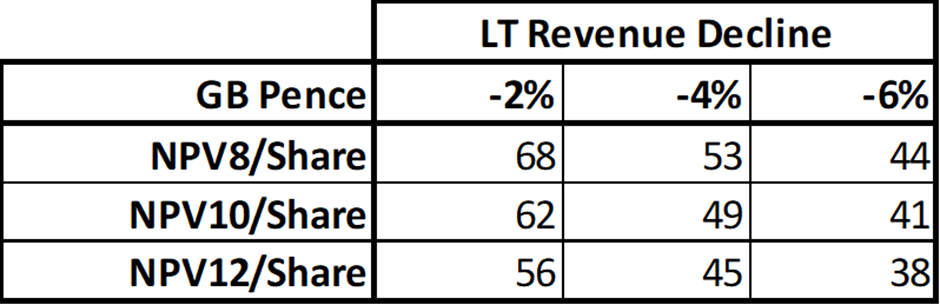
Given that the company is in a declining market, investors need to be careful about expecting large gains simply due to the low P/E ratio. As I made clear in the Stock Pitch, a Discounted Cash Flow model is a better way of determining undervaluation. In mine, the company now looks undervalued under all but the most pessimistic set of assumptions:
UP Global Sourcing Holdings (LON:UPGS)
UP Global Sourcing is a designer and manufacturer of homewares, typically at the more affordable end of the market. It sounds like a pretty mundane business, but good execution has allowed them to consistently generate a return on equity significantly above their cost of capital:
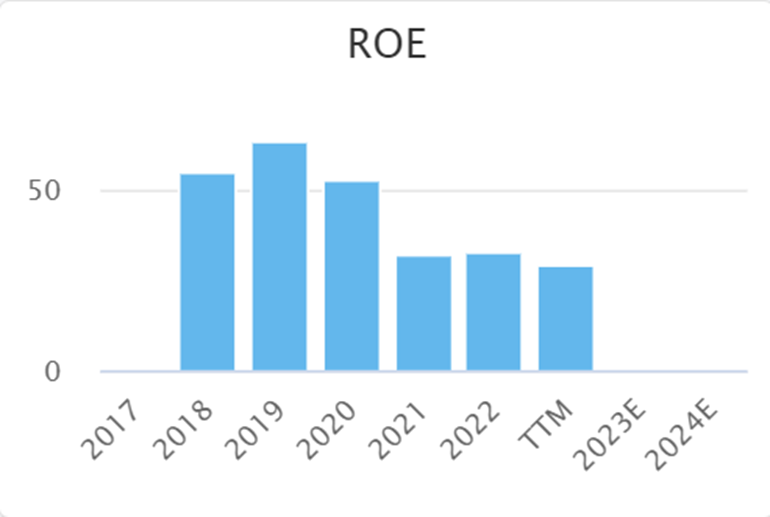
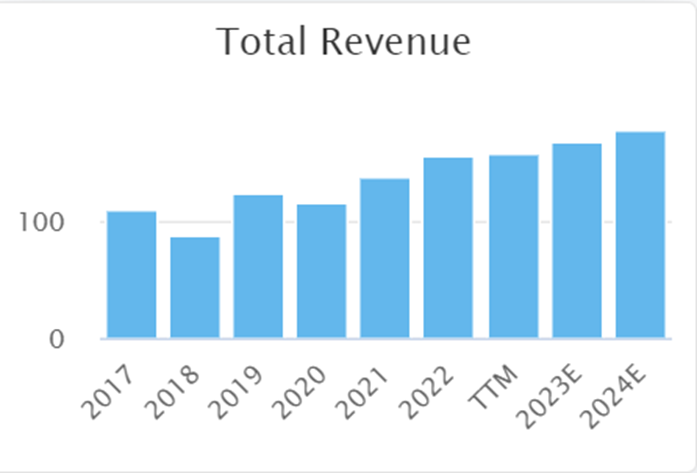
This means that their steady revenue growth, while not outstanding at 7% CAGR, is enough to have delivered significant shareholder value:
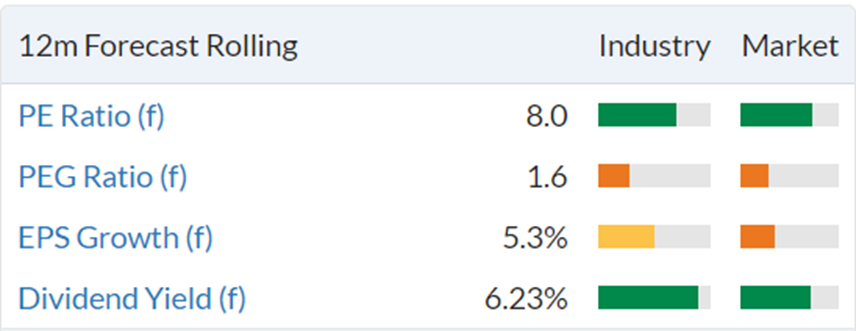
In light of this, a forward P/E of 8 and dividend yield of 6% looks too low:
In their pre-close trading statement last month, the company confirmed that they are trading in line with expectations on decent revenue growth:
Unaudited Group revenues increased 8% to a record £166.3m (FY22: £154.2m), driven by exceptional growth at the Group's online division, where revenues were up 64% year-on-year, together with an improved sales mix.
They have achieved this partly by giving up margin to maintain their price competitiveness. Their margins will likely return to market levels over time, which may offer an upside on top of long-term growth at a very reasonable price.
H & T (LON:HAT)
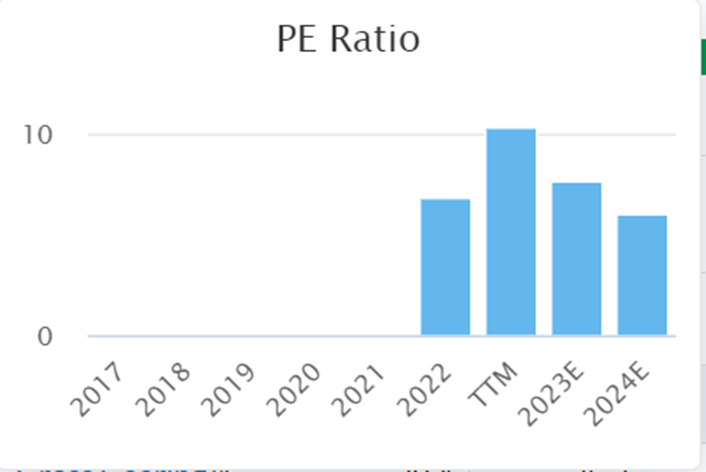
When I looked at pawnbroker, Ramsdens Holdings (LON:RFX) , as part of the series looking at SuperStocks, I noted that competitor H & T (LON:HAT) looked quite a bit cheaper, at least on a P/E basis. Although Ramsdens Holdings appears to be a better-run business with higher quality metrics, the valuation difference may be too much to ignore. 2024 broker estimates leave H&T on a forward P/E of 6 versus 9 for Ramsden's:
In their interim results last month, H&T reported:
Profit before tax increased by 31% to £8.8m (H1'2022: £6.7m), as continued momentum in our core pawnbroking business provides a robust revenue and profit foundation for the remainder of the financial year.
The pledge book grew 14% to £114.6m (December 2022: £100.7m; June 2022: £85.1m) with demand for pledge lending remaining at record levels. Gross lending grew 22% to £128m (H1'2022: £105m).
On top of which, they say:
We expect a lower level of cost inflation in the second half of the year which, alongside the growing revenue momentum of the business, puts us on track to deliver record profits in 2023.
Despite this, some investors may be wary about the outlook here. In response to these interims, their broker cut their EPS forecast by 7%. And after making 16.3p in H1, it needs a very good H2 to achieve the 53.7p for the full year.
Cashflow and profitability are also adversely affected by loan book growth, but this will help the scale economics of individual stores. There seems to be plenty of scope for further expansion without significant capex. This will require working capital, but there is no sign that the company is overstretching itself in this. And if the loan book growth slows, they will generate free cash. Their lending is all secured and relatively short-term, so it leaves them exposed to little credit risk. Given these qualities, a forward P/E of 6 seems harsh, even if there is work for the company to do in H2.
Severfield (LON:SFR)
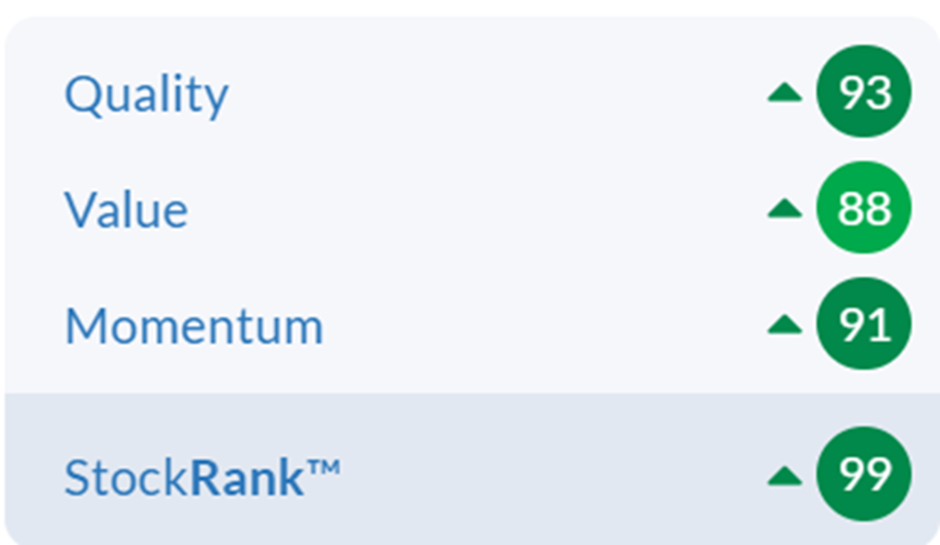
Severfield was one of the three SuperStocks I looked at in more detail in an article at the end of July. At that time, the SuperStock ranking was largely due to the QM ranks (although the Value Rank was not bad):
Since then, there has been a small downgrade in forecasts:
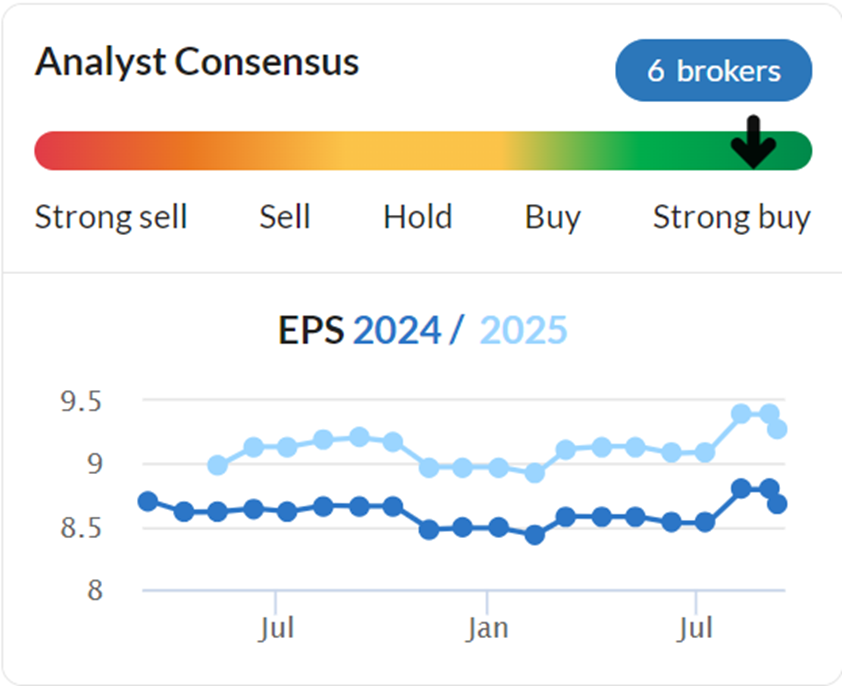
This was in response to a weaker outlook in the AGM statement earlier this month:
Whilst current trading conditions are more challenging, given the Group's historical performance, diversified activities and the strength of our order books, we continue to expect to deliver further progress and a result for 2024 which is in line with our expectations.
In line here seems to not mean in line with broker expectations! However, with a 10% drop in share price on a 2% decline in forecasts, this appears to be an overreaction.
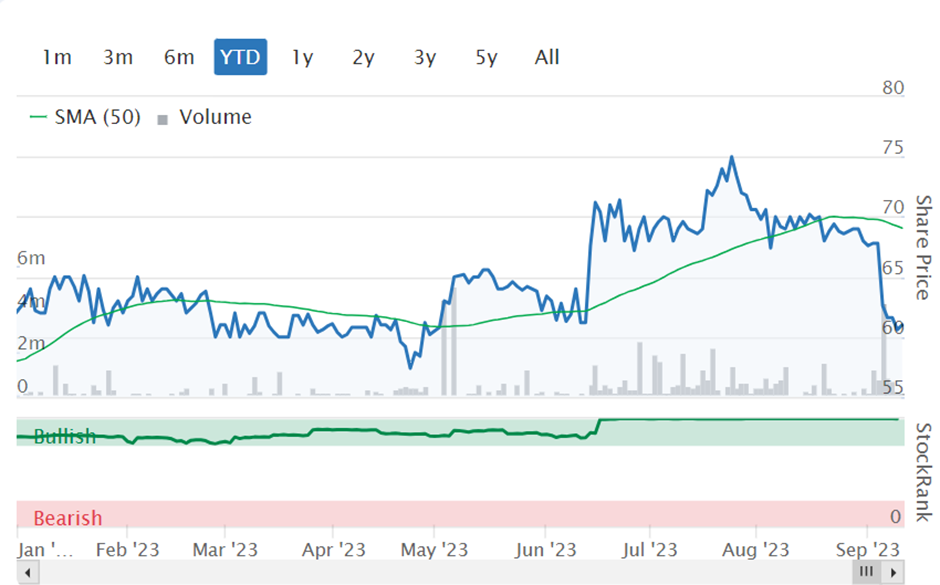
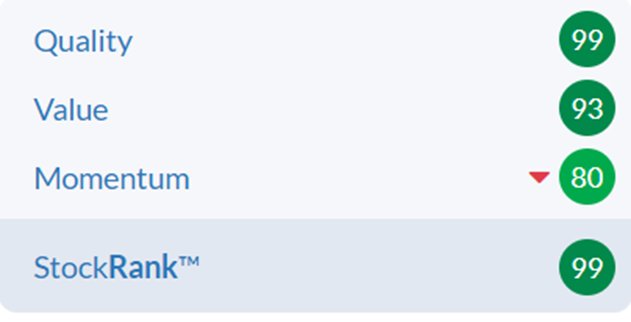
The stock remains a SuperStock, but now the value Rank is doing the heavy lifting instead of the Momentum Rank:
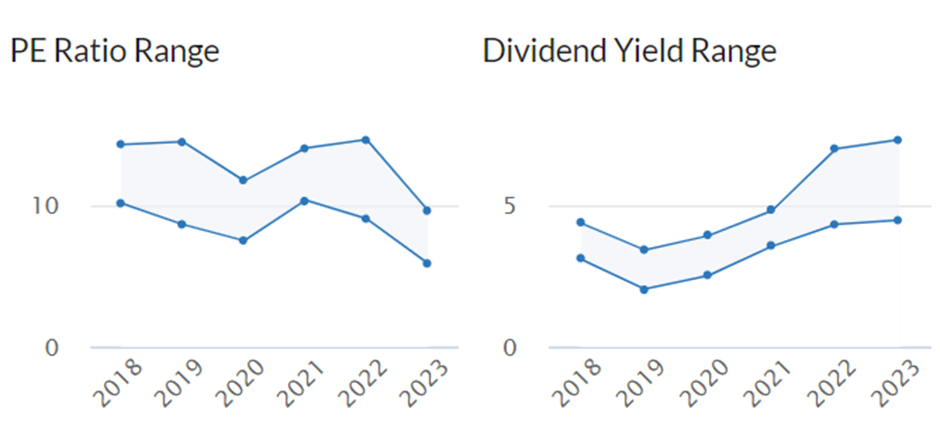
The P/E ratio is now lower, and the yield is higher than at any point in the recent past:
VP (LON:VP.)
VP was one of the businesses I looked at as part of my sector review of the small cap hire companies in May. This wasn't the cheapest company in the sector, but it was the fastest growing, making it attractive. Since then, the share price has dropped further:
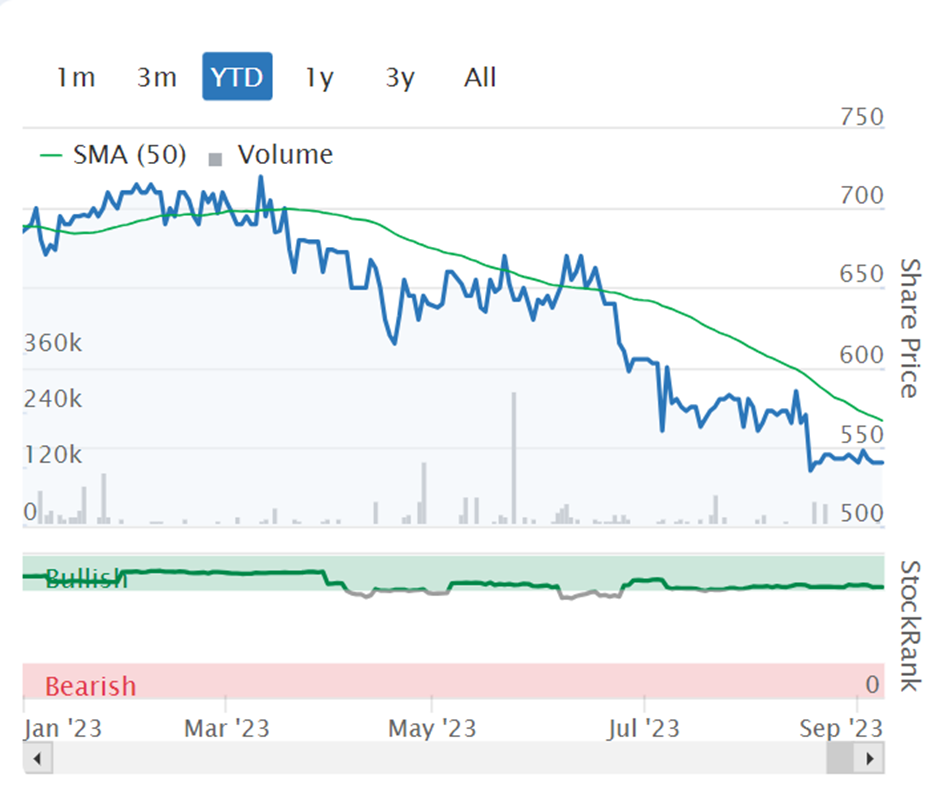
Perhaps logically so, given the weakening outlook for the UK housing market. However, this has not been reflected in weaker broker forecasts for the company:
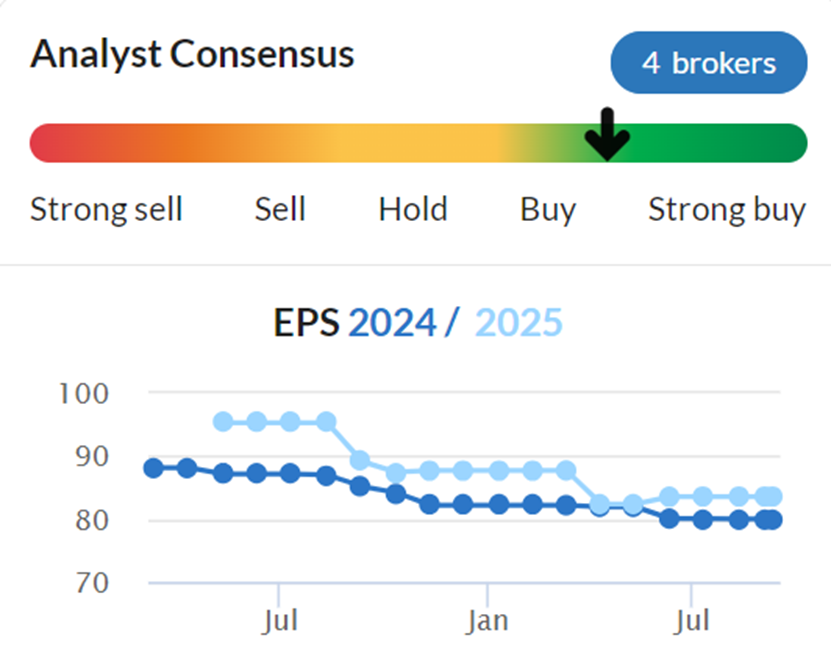
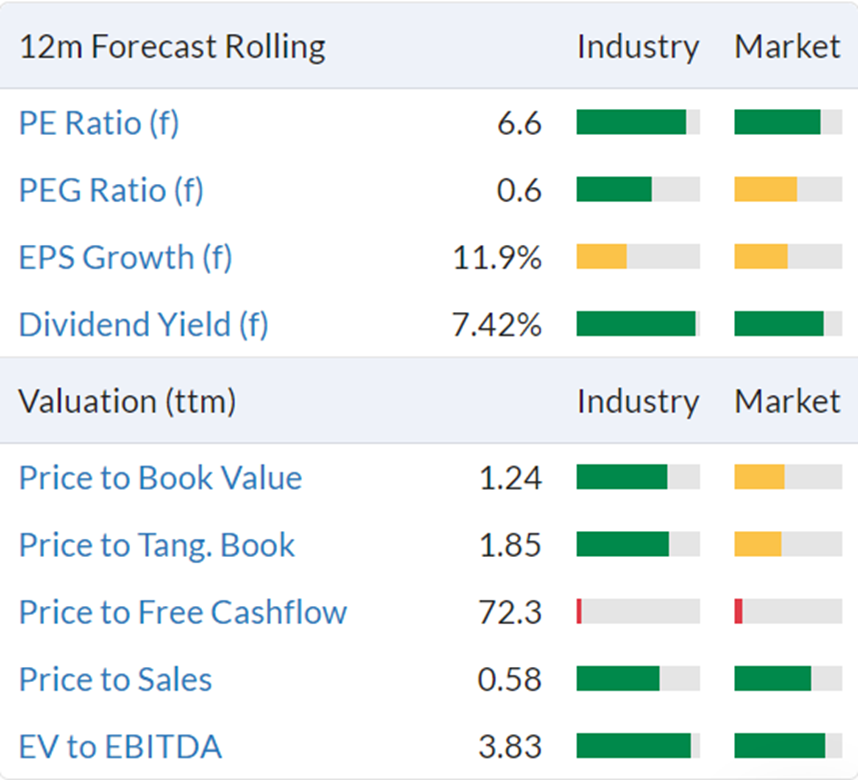
And in the company's AGM statement in July, they confirmed that they are trading in line with these expectations despite market headwinds. As such, the value metrics are a sea of green:
Reach (LON:RCH)
The dividend yield of over 10% will be attractive to many investors on its own:
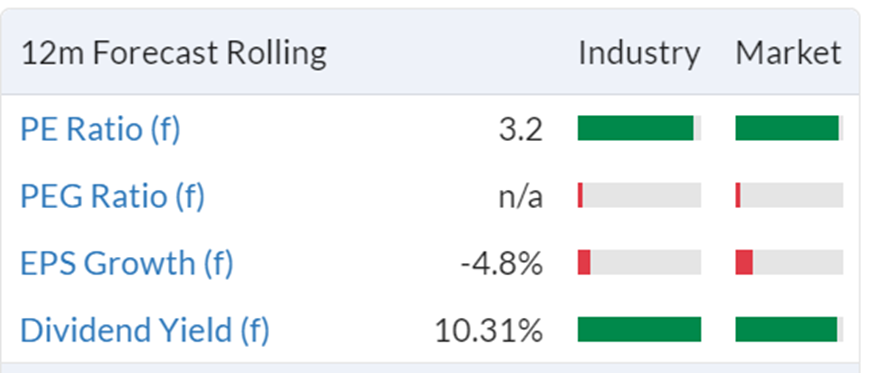
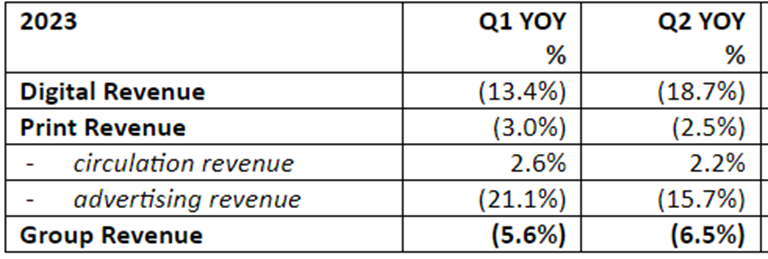
On the surface, the P/E of 3 may look good as well. However, this is a declining business. The message management is giving is one of growing digital revenues taking over from declining print. Unfortunately, recent results paint a different picture:
The other thing these simple metrics miss is that the company is barely above break-even on a statutory basis. This is what management would like investors to ignore to get to adjusted EPS:
Included in adjusted items in 2023 are restructuring charges of £10.2m, principally severance costs that relate to cost management actions taken in the period. Other adjusted items comprise the Group's legal fees in respect of historical legal issues (£4.6m), adviser costs in relation to the triennial funding valuations (£1.2m), internal pension administration expenses (£0.3m) and corporate simplification costs (£0.2m), less a reduction in National Insurance costs relating to share awards (£0.4m) and the profit on sale of impaired assets (£0.3m).
However, their business model is to keep taking costs out by making journalists redundant, so there will always be restructuring charges. They will almost always have legal fees, and the pension is not going away. The triennial pension advisor costs are potentially exceptional or at least shouldn't occur each year. However, it does take them more than three years to agree to a triennial valuation. So, hopefully, they are not paying double fees now they have two on the go simultaneously.
Even simply adding the pension deficit and legal provisions means that the company is on an adjusted P/E of closer to 10 rather than the 3 that it first appears. The real small cap silliness is that smaller peer National World (LON:NWOR) is on a much lower cash-adjusted P/E of 4 despite not having the same legacy issues. I wrote a recent Stock Pitch on this company here.
Pan African Resources (LON:PAF)
I looked at this South African gold miner in October 2022 as part of my series looking for stocks that were cheap on earnings. Since then, the shares have been on a bit of a rollercoaster ride:
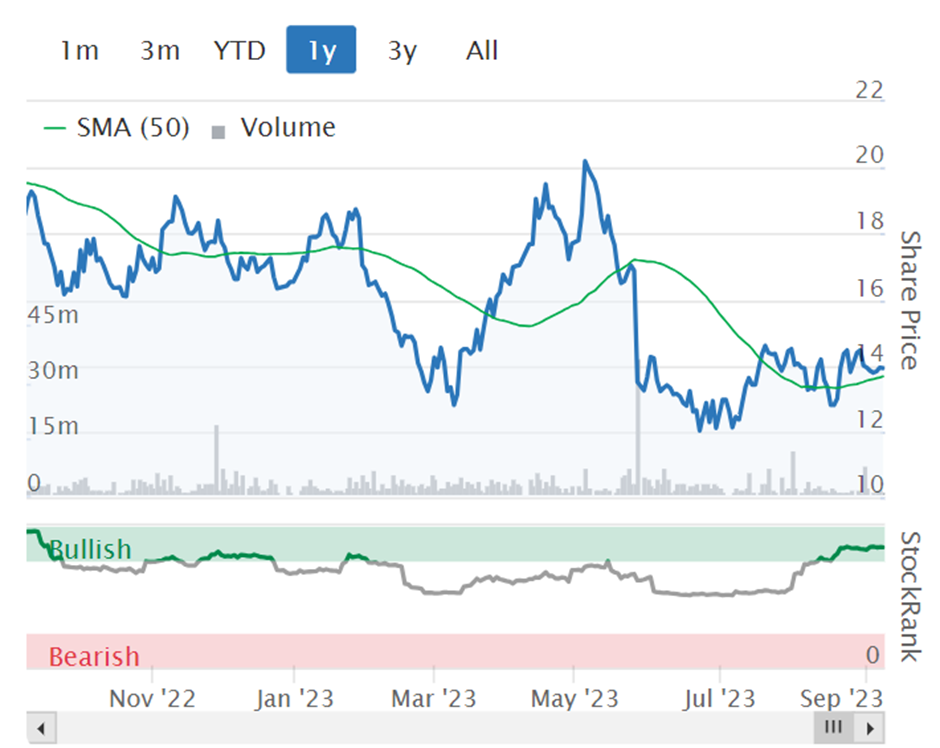
Earlier this year, the shares sold off on worries that they would need to raise new equity to fund their plans to develop the xx project. In the end, they managed to obtain sufficient debt funding to develop this, and no equity raise was required. Along with some strength in the gold price, this saw the shares rise from around 13p to over 20p. Sadly, this was short-lived. In June, they announced that the well-publicised issues with the South African power grid had impacted them more severely than expected, and they cut their production guidance. This led to a downgrade in brokers' forecasts:
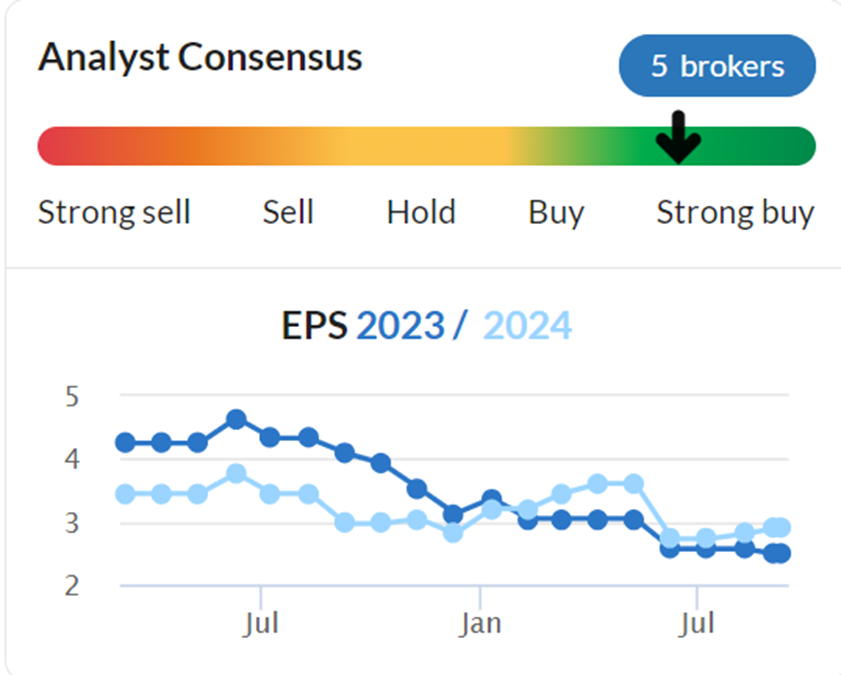
However, it is not all doom and gloom. The company has been one of the first to commit to solar projects and had plans in place even before the latest power issues. Although it will take time for the solar power to be installed and connected, this foresight puts them in a better position than many South African peers.
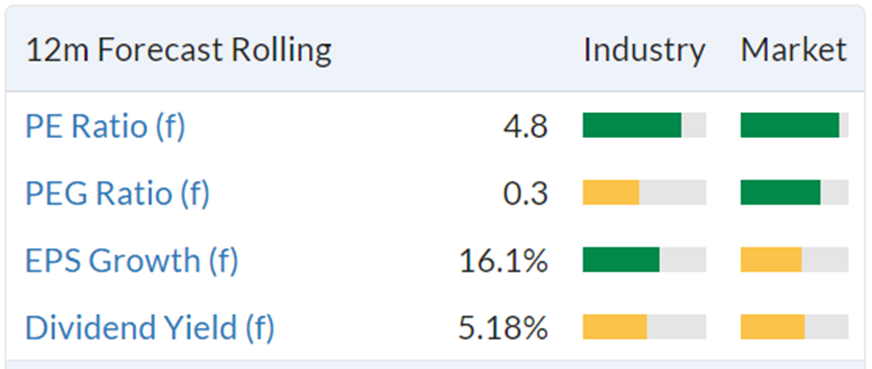
Despite the setbacks, the company remains on a very undemanding rating:
Although this screen seems relatively simple, it has generated many ideas worthy of further research. Next week, I will see if similar value exists in large caps.
[Disclosure: Mark holds shares in National World (LON:NWOR) Pan African Resources (LON:PAF) ]
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

9 comments
UP Global Sourcing Holdings (LON:UPGS) is my 3rd largest holding which I initially bought after a sharp fall in 2019. Slight correction, they are not a manufacturer, I'm not even sure the design element is that significant I see them mainly as a brand manager and box shifter. That appeals, no stores to run, no shoplifters or returns to deal with; move a palette from A to B, send an invoice.
Another appeal is that they deal in the cheap and cheerful end of the market. I cynically saw it very much as a post Brexit stock catering to the newly impoverished in a newly declining nation. However, they do have a significant overseas market supplying many household names, being skint is a fairly universal condition. The term cost of living crisis hadn't been coined when I bought but that certainly describes their market segment.
I think when looking for overlooked value its actually better to look for a dividend yield under 5%, as a high dividend yield always attracts attention.
Mark, the tags for all the companies, covered in this article, have gone missing.
found thanks!
hi Mark great thanks for this - were is the link to the screen please. ?
Tharisa (LON:THS) is an interesting play as well. Often not picked up in lists as I think it may be dual listed.
Yes, the primary listing is JSE, otherwise Tharisa (LON:THS) would be in these screen results, and I agree it looks too cheap, and hold it. I think the key point is that, at current commodity prices, Tharisa (LON:THS) is far cheaper than Sylvania Platinum (LON:SLP), but many investors only hold Sylvania Platinum (LON:SLP) on former glories in the hope that PGM pricing is coming back, whereas Tharisa (LON:THS) have the chrome production that makes them a much safer bet, with similar upside if PGM prices bounce.
Good article. If you broadened the market cap criteria to £500m, the screen might throw up my largest small cap holding, Paypoint. (LON:PAY). PER under 10 and yield above 7%.
Paypoint was the first company I reviewed in the midcap madness article: https://www.stockopedia.com/co...
Defining midcaps and small caps is always a bit of an art rather than a science, but I think these criteria overall work across all sized companies.