Small Cap Value Report (1 Apr 2016) - LAKE, JDG, TRCS, NXR

Good morning!
April Fool's Day today, and my favourite article is this corker from the Guardian, which had me in stitches once I realised it was not serious, about half way through.
Best Tweet of the day (well from last night, to be completely accurate) so far comes from the utterly brilliant (get this woman into Parliament) Julia Hartley-Brewer;
Lakehouse (LON:LAKE)
(at the time of writing, I hold a long position in this share)
Slater/Rawlings EGM statement - I was rather hoping that this announcement was also an April Fool, but sadly it appears not. As a LAKE shareholder myself, I'm getting increasingly perplexed and annoyed by the mud-slinging in public going on between the Slater/Rawlings team, and the incumbent management of LAKE.
This is just not the way things should be done. If they think management are no good, then Slater/Rawlings should have called an EGM to replace the executive Directors. Instead they have gone down the bizarre route of wanting to evict the NEDs, and put in Rawlings himself (the founder), and 2 other people they think would be good NEDs.
The company's response was to reject this - mainly on the grounds that the new NEDs would not be independent, which is a fair point. Although I think the company was foolish to then publicly slate the 3 suggested new NEDs, undermining their credentials in this announcement, which seems to have burned their bridges towards a compromise - not a good negotiation stance.
All in all, it's ludicrous situation that needs to be sorted out asap, as the company is just racking up unnecessary costs on numerous consultants, not to mention management time wasted, on this issue.
I can't help feeling that it's a bit of petulance on the part of Slater. They overpaid in a bad IPO, and are now throwing their toys out of the pram. If they're serious about changing management, then they should have just spoken to management, and if not possible to get the changes they want, then call an EGM to unseat the executive Directors, and put in new management. That's the way it should be done. Changing the NEDs but leaving in place the execs that they say have done a bad job, seems daft to me.
Anyway, the current situation is not showing anybody in a good light, so they need to be locked in a room, and not let out until all the issues have been resolved one way or another.
EDIT: I've just been emailed the official response today from Lakehouse to Slater/Rawlings announcement above. It says:
The board of Lakehouse notes the statement lodged by the Requisitionists this morning and will respond in more detail on Monday 4th April, 2016.
While the board is considering the Requisitionists' statement, it notes the reference to private noises made by Slater Investments. As you know, the Board announced its intention to seek a fourth independent Non-Executive Director.
The Board, reflecting on the views expressed by some Lakehouse Shareholders, did meet with Slater Investments on Tuesday 22 March 2016 to discuss the possibility of appointing a fourth Non-Executive Director.
Your Board considered this action sensible and appropriate in order to avoid further adverse disruption, and unnecessary cost, that the Company has now suffered.The Lakehouse Board urges all shareholders to vote against the resolutions put forward by the Requisitionists.
It's encouraging to see that the two sides have met, and that the company has offered to compromise. All the shareholders I've spoken to are unhappy with both sides, and want this issue put to bed immediately, leaving management (however structured) to get on with restoring shareholder value.
Note that the current CEO, Stuart Black, is also a substantial shareholder, owning 5.5m shares. So his interests are very much aligned with ours, as well as the founder, Steven Rawlings (who owns 24.4m shares), and Slater Investments (c.6% I think).
On reflection, I don't like this comment from the Slater statement today, which says;
Lakehouse's history as a public company is short and disappointing. Lakehouse listed on 23rd March 2015 at a price of 89p per ordinary share. On 10th December 2015, Stuart Black, at the time the Company's Executive Chairman, reported that "the Board remains confident for the current financial year." Only eight weeks later, on 1stFebruary 2016, the same Board issued a major profit warning. The share price fell 58% from 84p to 35p. Since we requisitioned this General Meeting the shares have rallied a little. We do not believe that the Board has a firm grip on the Company and its prospects.
The share price has actually rallied 44% since the low point of 35p which they mention above. I don't call that a little! Also, I don't think the rally was driven by their EGM requisition, as they imply. It was an oversold rally which would have happened anyway. Actually, I think the EGM requisition is holding back the price, by creating uncertainty, and recall that when the EGM requisition came out, the share price fell sharply, but has since rebounded.
Finally, if the last sentence above is true, then why on earth are Slater/Rawlings not trying to remove the Execs? The company pointed out that at the AGM, Slater & Rawlings actually voted in favour of the Directors, but then shortly afterwards requisitioned this EGM. So at the moment I'm leaning towards supporting the incumbent Board in the EGM vote.
Buy & build
Lakehouse (LON:LAKE) is a buy & build group, and that is the theme of today's report. For anyone not familiar with the term, buy & build is where a group is built fairly rapidly, by starting with a core management & company, then bolting on multiple other acquired companies usually in the same sector. Trying to improve profitability through using the expertise, IT, and sales/marketing capabilities of the core company is usually key to this strategy.
Generally, investors are wary of groups which aim to grow through a buy & build strategy, because this approach often goes badly wrong in the long run, if too much debt is accumulated, and if management are incompetent and buy lots of duds, or overpay for not very good companies.
Although it can be done well - it's all down to good management, with a disciplined approach to buying the right companies at the right price. Look what a spectacular success David Cicurel has made of Judges Scientific (LON:JDG) - which incidentally announces another small, but profitable acquisition today. Interestingly, Cicurel's strategy has been to largely ignore synergies, but to just buy good businesses on attractive multiples. The group is valued on a higher earnings multiple than the companies it buys, so it instantly creates shareholder value every time he makes another acquisition.
Another example is John McArthur at Tracsis (LON:TRCS) who has also created considerable shareholder value from a similarly disciplined approach to buying target companies - he sets out the specific acquisition strategy, and a worked example on valuation, on Tracsis's website here. Other company CEOs should read that website page, as it's a masterclass on how to make decent acquisitions!
Norcros (LON:NXR)
Share price: 169p (up 1.7% today)
No. shares: 61.0m
Market cap: £103.1m
(at the time of writing, I hold a long position in this company)
Acquisition - This is another group which is executing well with a buy & build strategy. The share price at Norcros seems astonishingly depressed, despite Gervais Williams' Miton Group having hoovered up 17% of the company. The shares look remarkably good value, although bear in mind the large pension fund is an ongoing issue.
Today Norcros announces another sensible-looking acquisition, of a bathroom products company called Abode Home Products Ltd, its website is here. Although a small deal, costing just £3.9m initially, with a potential £0.9m earn-out, this looks a cracking deal.
Here is the P&L from Abode, from its most recently filed accounts - which are for y/e 30 Jun 2014. Note that the company seems to have been late filing its 2015 accounts, which should have been filed by yesterday, 9 months after the year end. Perhaps they are being processed by Companies House still? This is perplexing - a financially sound company should always file its accounts promptly, not leave it until the last minute. After all, if I were a prospective supplier to Abode, I wouldn't be very happy about only being able to look up financial information about the company which is now nearly 2 years' old.
Here is Abode's P&L;
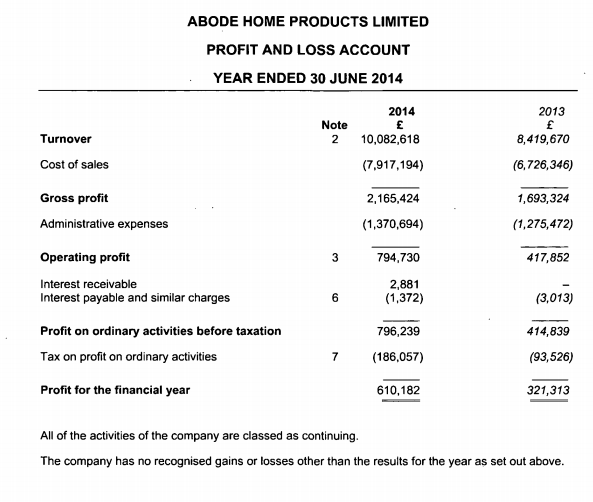
One point to note is that Abode's CEO pays himself in dividends, with only a de minimis salary. So this increases reported profitability. Therefore the above profits would need to be reduced by, perhaps £200k p.a., to include a normalised salary for the CEO. It's still a nice bit of additional profit to bolt onto Norcros's group figures.
Also, I like the fact that Norcros has a large, international sales & distribution network. So it can feed Abode's products into that network, and hence leverage greater sales from the acquired company. So this acquisition makes a lot of sense, and I hope in due course should provide a catalyst for Norcros shares to re-rate. I believe that patience will eventually pay off with this share.
Cantors helpfully point out in a note this morning that a new FD is starting next week at Norcros. He was previously FD at AGA - which of course also had a big pension fund, but despite this was acquired by a larger American group.
They estimate that the acquisition announced today will add c.5% to both revenues & profits. Not bad for an outlay of just £3.9m, using cheap debt.
Back to buy & build generally
The other thing with buy & build, is that it creates the illusion of growth, especially when financed by debt. That's fine when debt is cheap, and providing the multiple of debt to cashflow doesn't become too stretched. So investors are more likely to rate the group shares on a higher PER than the acquired companies are bought for. If all goes well, this can create a virtuous circle where each cheap acquisition bolts on more earnings, and thus creates instant shareholder value as the earnings are re-rated onto a higher multiple. The cashflows generated can then repay the debt, over a number of years.
It's worked amazingly well for Judges Scientific (LON:JDG) so let's hope Norcros can execute similarly well. So far, so good, as the acquisitions made by Norcros in the last couple of years seem to have done well. The beauty is that Mom & Pop type businesses can often be picked up cheaply, if the founders want to exit for retirement. Plus profits can be greatly increased if the products are sold aggressively through the acquiring group's much stronger sales network.
All interesting stuff! The absolutely vital factor for a buy & build strategy to work, is that management must be absolutely top notch. The worst think that can happen with buy & build is if you have a clueless or delusional CEO trying to execute that strategy - examples include that clown at Silverdell, and of course the maniac Rob Terry formerly at Innovation Group & then Quindell. So if you have even the slightest doubt about the competence, or integrity, of management - then keep a wide berth, as chances are that it will end in disaster sooner or later.
CML Microsystems (LON:CML)
Share price: 391p
No. shares: 16.2m
Market cap: £63.3m
Trading update - this was issued yesterday, and relates to H2, the 6 months ending 31 Mar 2015. Things sound on track:
The Group's operating results are on course to meet market expectations conveyed at the time of the half yearly results in November 2015, which were for a second half sequential revenue improvement and a full year advance in profitability.
New order bookings firmed as the period progressed and it is noteworthy that orders were received relating to the one or two customer product launches that had previously been delayed.
In terms of outlook, this introduces a small note of caution, but overall sounds fairly optimistic:
Customer demand from the end markets in which the Group operates continues to be difficult to predict however, the Board currently expects that the business strategy being followed will uphold expectations for a further trading improvement over the year ahead.
Valuation - here is the usual Stockopedia graphic:
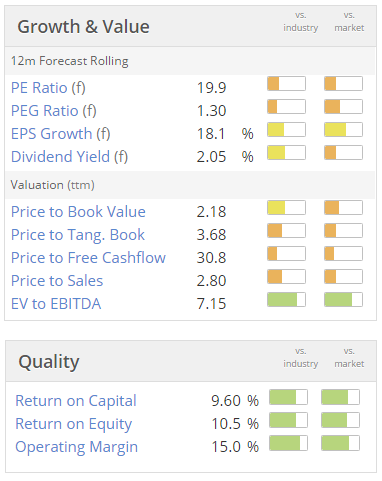
Looks a bit pricey to me, but remember to adjust the PER down to take into account the decent amount of cash on the balance sheet.
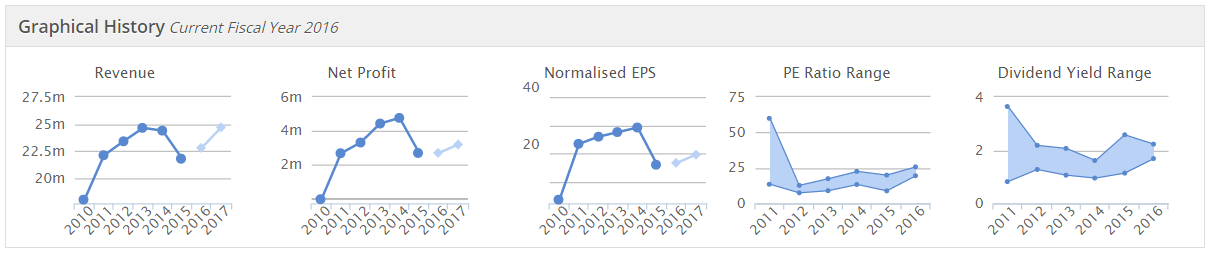
Another issue is that the company seems to have gone ex-growth. So although it's operating in a sector that is perceived as sexy, will that remain the case if it's not delivering growth?
Boohoo.Com (LON:BOO)
(at the time of writing, I hold a long position in this share)
Menswear growth - when I visited BooHoo's Manchester HQ last year, the business was clearly almost completely focussed on ladieswear. There is a menswear department too, but it's tiny compared with ladieswear. So there's a good growth opportunity if menswear can also be grown.
Therefore, I was pleased to pick up this morning that Scotty T from Geordie Shore, and winner of the most recent Celebrity Big Brother, has been appointed as a model & brand promoter for BooHoo Men. I think this is a really good choice for the target market. For those not aware of this gent's credentials, he's an affable chap, whose life largely revolves around, to use the geordie vernacular, getting smashed & banging girls. Why not?!
He'll be wearing BooHoo clothes on Geordie Shore apparently - well, wearing them briefly anyway, before embarking on his next conquest.
EDIT: Here is the new specific menswear website just launched - BooHooMan.
BooHoo has proved itself adept at marketing using social media, Vloggers, etc. The shares look expensive, and are expensive, but that's because it's a strong organic growth company. Underlying profitability is much higher than the reported figures, because it's spending so much on marketing to drive growth. Around 13% of turnover is spent on marketing - that creates a big moat which smaller competitors just can't match.
Menswear will never match ladieswear, because men just spend less on clothes than women - that's why the prime ground floor retail space in the High Street is almost all targeting women. What menswear there is, will be in much cheaper basement or first floor locations usually, or right at the back, where the rent per square foot is a lot lower. So the lower sales psf from menswear can only work in low rent locations. Apart from high end stuff of course. I'm just talking about mainstream clothing.
I'd say there's probably an opportunity for, over time, BOO to add maybe another 10-20% of incremental sales by ramping up sales of menswear. However, that will come at a cost, in marketing spend. All good for the share price though - as the market laps up growth stories, so another growth avenue will be looked on favourably by the City I think.
Also, I do hope BOO brings PrettyLittleThing.com in-house. It's got a £5m call option over the company, which really I think it will be obliged to exercise, given the strong growth that PLT has produced recently.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

25 comments
Regarding Judges Scientific....
It has been an exceptionally busy last few weeks for David Cicurel the energetic CEO of Judges Scientic who always enjoys coming back to Mello to update the tens of our regular attendees who have become shareholders in the company over the last seven years. This evening our Mello in Beckenham will be welcoming David and his FD Brad Ormsby back to the SeaSalt restaurant for their latest update especially as the final results were out just last month. The share price of JDG was just £1.78 when David made his first appearance and are now over £18 so you can see why we like to have him back... http://www.freesharedata.com/mello
The recent news has been very good with the results and two acquisitions linked below...
Feb 2016
Judges Scientific, the parent company of a group engaged in the design, manufacture and sale of scientific instruments, announces that it has today acquired 100% of the issued share capital of CoolLED Limited ("CoolLED"), an instrument maker based in Andover, Hampshire. CoolLED designs, manufactures and markets illumination systems for fluorescence microscopy (the "Acquisition"). The Board expects the Acquisition to be immediately earnings enhancing.
http://www.investegate.co.uk/judges-scientificplc--jdg-/rns/...
March 2016
Final results http://www.investegate.co.uk/judges-scientificplc--jdg-/rns/...
and a further acquisition
Judges Scientific, a group involved in the buy and build of scientific instrument businesses, is pleased to announce that the Company's wholly-owned subsidiary, Fire Testing Technology ("FTT"), has acquired the business of Fire Instrumentation & Research Equipment ("FIRE").
http://www.investegate.co.uk/judges-scientificplc--jdg-/rns/...
April 2016
Just in case we did not believe they come in threes like London buses along comes another company deal...
Judges Scientific, a group involved in the buy and build of scientific instrument businesses, announces that it has today acquired 100% of the issued share capital of Dia-Stron Limited ("Dia-Stron"), an instrument maker based in Andover, Hampshire. Dia-Stron designs and manufactures systems to test the mechanical properties of fibres (the "Acquisition"). The Board expects the Acquisition to be immediately earnings enhancing.
http://www.investegate.co.uk/judges-scientificplc--jdg-/rns/...
So lots to talk about in Davids presentation tomorrow evening or tonight when most of you read this. Our Mello evenings are always flagged up on the website http://www.freesharedata.com/mello and all investors are welcome. We meet for drinks from 6pm with the first presentation always starting just after 7pm and you can stay for dinner afterwards which is a great opportunity to do more networking and ask even more questions as the directors usually stay on for dinner too.
If you would like to join us then just email me by replying to this post or through the website so that the restaurant have an idea of the numbers involved.
As an added bonus this month we will have a special guest who will be doing a 30 minute Q&A with investors on the subject of Excessive Remuneration and discussing some of the recent headline cases that have been picked up by the media....BP, Persimmon etc and BP actually lost their remuneration vote at the Agm but will there be much done about it around the boardrooms of the UK ? http://www.sharesoc.org/blog.html
Our guest will reveal all as he is a top remuneration consultant but has now officially left the industry and believes there are some ridiculous pay schemes that suggest 'enough is enough' and he wants to show investors what can be done to stop all this excessive greed at the top of UK Plc !
It should be an interesting evening....why not join us ?
David
Slight timing error in my post above. I actually bought LAKE on 8th March (not 16th) @39.49p and sold on 31st@49.76p.
Does seem to be every chance that the next set of results will be disappointing with an optimistic statement. The winner of the battle will have other people to blame, so I would expect them to take every opportunity to make pessimistic interpretations of the current position so they will look better themselves.
I nearly bought, but didn't, so I don't have a 25% profit to bank. :(
- but I would if I could.
Ref Lakehouse I bought on 16th March after the Company confirmed it was on track to meet its revised projections. As Paul pointed out this seemed to make the shares an absolute bargain. The public spat between the Board and Slater/Rawlings then intensified. The Company's circular included the remark :-
"The Requisitionists' actions have caused unnecessary disruption to, and uncertainty within, the operations of the business at a time when the Board wants to focus on the trading performance of the Group" -
which made me wonder whether they really are on track to meet the new targets or not.
For all of my holdings I regularly question "If I didn't already own it, would I want to buy today?"
I took the view that the balance of risk had shifted in the last couple of weeks and the answer was no. I was able to sell at 25% nett profit on Friday 31st. I was happy with that but suspect I may have exited prematurely.
Lakehouse.....The latest thoughts on the ShareSoc blog
https://sharesoc.wordpress.com/2016/04/01/lakehouse-corporate-governance-is-not-just-about-box-ticking/
Hi Paul, couldn't agree more regarding Boohoo.Com (LON:BOO) and Pretty Little Thing. Looks an absolute steal at £5m for a business growing very quickly. Clearly the Kamani family are very good at what they do! Like father like sons!
Paul, your views on the Scisys result which came out yesterday would be appreciated
Hi Herbie.
I may have got my wires crossed, but I recall reading that Wilding picked up 11m shares for his leveraged re-cap/acquisitions spree with Victoria (LON:VCP). The £7m you refer to came when he sold 1 million shares, i.e. 1/11 of his LTIP derived shareholding. Also not a holder (or shorter) and happy to be corrected if I am wrong. Not sure whether his shareholders see him as King Midas or a corporate mugger. I guess at £15 share, there can't be too many complaints.
Gus.
Yes I think you are correct, seems he got 7m shares. I'm not a holder either way. The shares have done very well but I won't be investing now. Timing of next recession is crucial for Victoria (LON:VCP) shareholders.
I agree with you that the battle at Lakehouse is holding things back. I captured some of the price recovery but took my profit and am waiting on the sidelines to see how this plays out. Likewise I'm puzzled by the focus on the NED's and believe there's no reason why they all should be independent. I don't see how they can deny Rawlings a seat given the size of his holding. But wouldn't he better off raising funds to take it private? Presumably it's all deeply personal.
NMD worthy of your views methinks. A contractor whose recent history has been plagued with problem contracts overrunning etc. Most and possibly all of those are now resolved, and with strength of order book I reckon they could do £5+m pbt this year vs a market cap of just £14m (for a P/E of c. 3.5). All plausible with an order book of almost £200m. In 2006 (pre-recession and all these contract overruns) they did £5.4m pbt on turnover of £175m (paying an 8.5p divi). The shares traded over 500p in 2007 (vs 138p today).
Looks a better bet than LAKE at the price (to me!) give that there's very little debt.
Results today
http://www.investegate.co.uk/north-midland-cnstrn-...
Accidents, however, may happen!
When it comes to "buy & build" strategy, don't forget Victoria (LON:VCP) which has been on a tear since current chairman Geoff Wilding came on board in 2013.
He has done 4 or 5 major acquisitions since then with an average EBITDA mutiple of 4.5 (source: SCSW). The share price has rocketed from around 500p in Jan 2015 to a current 1500p.
But there is no free lunch. Net Debt has soared to £80m from Net Cash of £8m prior to the acquisitions. Although the company maintains they are still within the bank convenant limit of 3x EBITDA, by my calc they are over 5x Operating Profits.
FCF is also worrying low. This is a cyclical business and having a weak balance sheet is not a good idea.
Declaration: Not long or short. I am watching from the sidelines. Today the risk/ reward doesn't look that attractive.
Yes have been discussing this on another post. Geoff Wilding also got a £7m payment, I won't be investing in such a company. They are also looking at another acquisition. Looks very risky now.
With regards to Lakehouse and the Agm which I attended and asked many questions alongside at least 30 other shareholders. The facts and my thoughts are....
1. Steve Rawlings attended and voted all his shareholdings against various resolutions. The votes were very significant and there were some members of the board with only just over half of those eligible to vote actually in favour of their re election. The votes are here....
http://www.investegate.co.uk/lakehouse-plc--lake-/rns/results-of-annual-general-meeting-2016/201602051623232906O/
2. Institutions do not attend Agms and usually vote well in advance of AGMs. It is likely that Slaters were unaware of the feelings of Steve Rawlings at that stage.
3. I am passionate about shareholders taking responsibility for their share ownership rights and that includes larger shareholders attending Agms so that all parties will be aware of the views of the other owners. It is the Annual meeting but institutions rarely attend or send representatives. This could have been averted with institutions attending and supporting each other to gain sensible agreed changes after the meeting rather than in public airing like this.
4. I think there should be compromise with regards the NED appointments and that at least one should be retained and a totally independent NED appointed to represent the mass of private shareholders who currently feel disappointed that this is causing distraction and unnecessary cost.
5. Steve Rawlings did not previously want a place on the board and was happy to let the executives look after his very significant investment of previous time and wealth. That has changed and with over 25% within his and family holdings i see no reason why he should not be entitled to a non executive position. That is the case at hundreds of companies where shareholdings are over just 15%.
David
Hi Paul
Thanks for the write-up about Boohoo.Com (LON:BOO). I wondered where you got the information about PLT from. I've had a look at their accounts on Companies House (BETA) and see they are listed as 21 Three Clothing Company Ltd, but can't see their full accounts, just an abbreviated section of the balance sheet. I've come across a few articles, saying their growth in revenues has been strong, but just wondered whether they had published their accounts.
Regards,
Imran.
Imran - the info on PLT is in their admission document. http://www.boohooplc.com/~/media/Files/B/Boohoo/do...
Re Abode's Companies House filing: I track a couple of private firms accounts via Co House and it is not unusual to have to wait a a few days for the accounts to appear online after the filing deadline so I suspect your guess there is spot on.
Paul, I think the problem for Norcros (LON:NXR) is the South African element, it seems the economy there is getting worse, I admit thats one reason why I sold mine a couple of months ago and thats why the share price has fallen back, there could be rate of exchange issues also.
Hi Herbie,
We saw last year that the exchange rate really isn't a major issue for the S.African operations of Norcros (LON:NXR) - it just means that the profit translates at a reduced rate, but since both revenues & costs are all in local currency, then profit is unchanged in local currency.
Point taken though that a declining economy could stifle demand for products in S.Africa, although it was performing well last time I looked.
This is what Norcros said about its S.African operations, with interim results announced in Nov 2015;
Sounds pretty good, no? Although maybe things have deteriorated since, who knows? I'm not up to speed with the state of the S.African economy - one assumes it's struggling due to the resources sector malaise.
Regards, Paul.
Thanks Paul for that information, yes it looks good. I came across this article, it seems its not just commodities that is the problem: http://uk.businessinsider.com/south-africa-has-a-lot-of-problems-2016-2?r=US&IR=T
Paul,
Sounds pretty good, no? Although maybe things have deteriorated since, who knows?
We'll find out soon enough! Norcros financial year ended yesterday and there is normally a trading update in the next week or so.
All the best, Si
I think the problem for Norcros (LON:NXR) is the South African element, it seems the economy there is getting worse, I admit thats one reason why I sold mine a couple of months ago and thats why the share price has fallen back, there could be rate of exchange issues also.
Against that, we are looking at a PER < 8 even if they only match last years EPS (22p) which is entirely possible given that the Croydex acquisition could easily make up for any shortfall in SA? The SA business has been a problem for a while, so it's not really a new issue but it's one that has been cleverly diluted by the acquisition of Croydex, and today to a lesser extent, Abode. Let's face it, both look sound earnings enhancing acquisitions and yet they have not yet been reflected at all in the share price.
It's entirely possible that Norcros (LON:NXR) is a value trap, and to be fair it's never attracted a PER above 10 in recent years, but these things can change and while we wait it has a very safely covered 3.5% yield. So not the worst place to have some money parked.
With regard to exchange rates, it's bad enough trying to judge the business prospects of a company without second guessing currency markets on top, so it's not something I personally ever base investment decisions on.
All the best, Si
About "buy & build" , in my opinion Judges are the very rare exception in being able to execute the strategy well.
It rarely works to shareholders' benefit, only to the benefit of the directors who build a large empire and thus have to be "remunerated" properly in relation to size of company they are now running
The Rawlings/Slater statement on Lakehouse today says that in private discussions they would accept 2 of the 3 proposed new directors if they weren't imposed on them. No prizes for guessing who the 3rd is. It does seem very personal and hard to predict the ultimate outcome. The question for me is whose power they want to limit and how many execs they distrust to execute; I assume Stuart Black is one of their targets. I can understand why Rawlings wants a seat at the table, given the amount of money he has tied up in the business.
Excellent analysis as ever Paul. Not in Lakehouse (LON:LAKE) but hold all of Tracsis (LON:TRCS) , Judges Scientific (LON:JDG) and Norcros (LON:NXR) on the basis of their, so far, well executed buy and build at a sensible price strategy. As an alternative to the GARP, perhaps we could christen then GASPERs, i.e. Growth Achieved through Sensibly Purchased Enhancements to Revenue.
I'll get my coat .....
Gus.