Small Cap Value Report (1 Jul 2015) - SDY, HSS, TPT, QTX, VLK

Good morning!
Today's report will be equipment hire themed - as I report below on the profit warning today from Speedy Hire (LON:SDY) and I'll also circle back to the profit warning from HSS Hire (LON:HSS) a couple of days ago. Is something funny happening in equipment hire? Or are these two companies just executing badly? Let's have a look!
Speedy Hire (LON:SDY)
Share price: 48.7p (down 31.1% today)
No. shares: 521.9m
Market Cap: £254.2m
Profit warning - today's disappointing trading statement has come completely out of the blue. Checking the archive here, I last reported on 15 Apr 2015, when SDY reported positively, that it would be "slightly ahead of market expectations" for the year ended 31 Mar 2015, at the adjusted profit level. I concluded that at 73p the share was too expensive, being on a PER of 20.4, and with a lousy yield too.
The trouble is, if you pay up - a PER of 20 seems to be the norm at the moment for reasonably decent companies - then you've got no safety margin if something goes wrong. So as in this case, holders who cheerfully paid a PER of 20 are now nursing a 31% loss, that could take a long time to recover. Risk:reward just isn't good when you pay a full price for a share, if the company is only an ordinary company, as seems to be the case with SDY.
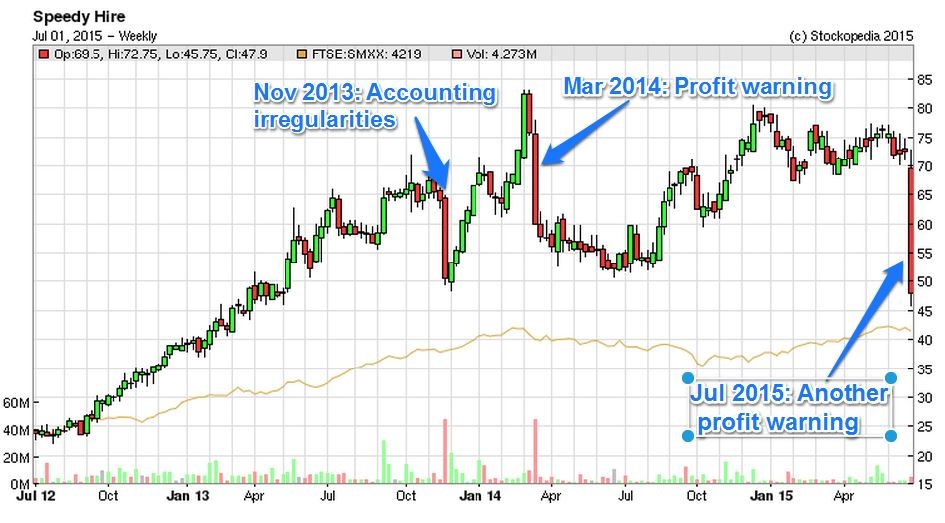
Looking further back in the archive, I didn't report on the profit warning in Mar 2014, but I did report on the accounting irregularities & resignation of the CEO in Nov 2013, here.
So all in all, shareholders must be feeling pretty cheesed off with what seems to be an incredibly accident-prone company. So it's difficult to see this share regaining its previously toppy rating any time soon.
What's gone wrong this time then?
The company flags a "slower than expected start to the current financial year" (i.e. Apr-Jun 2015, inclusive), giving the following reasons:
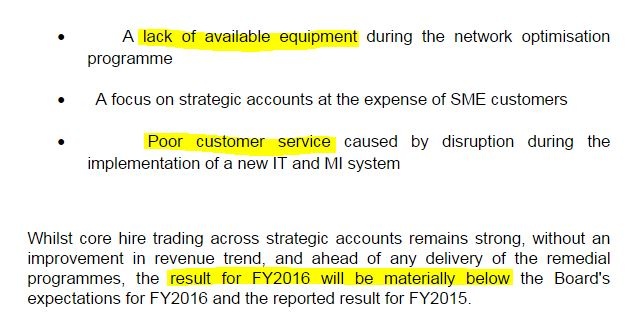
Furthermore, the disposal of their M.East business has now fallen through, with discussions terminated with the potential buyer. It's operating at breakeven now, so a setback rather than a disaster.
CEO resignation - the CEO has fallen on his sword, rightly so, as these look like basic mistakes in running the business. So the business has chewed up & spat out two CEOs now in under two years.
The Non-Exec Chairman, Jan Astrand, has temporarily moved up to Exec Chairman, and the FD, Russell Down, has become the new CEO (whilst also retaining the FD role temporarily, so he'll be a busy & stressed-out chap then).
Directorspeak - the Chairman tells it how it is today, which is good - shareholders will no doubt want action to fix things, not excuses.
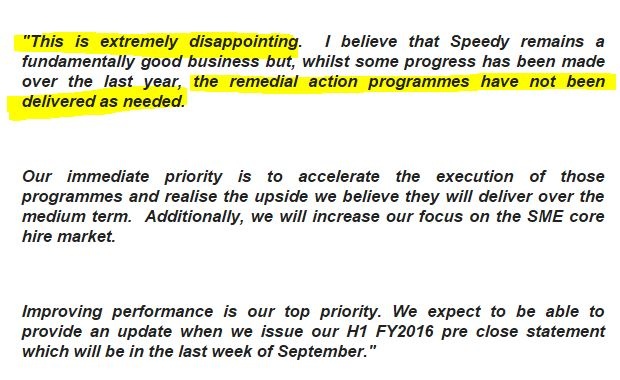
My opinion - these look like schoolboy errors in running what is fundamentally a fairly simple business, which hires out equipment. Management are paid to manage the business, so that errors like this don't happen.
Whilst the CEO has fallen on his sword, in my experience the CEO just sits on top, and there is an army of middle managers who actually run most businesses. So my concern with SDY is that, after three mishaps (see chart below) in under two years, maybe the business is just a poor quality business, with incompetent middle management? It looks like that to me, reading between the lines.
However, the problems all look like things that are fixable, so at some point this share could make a nice recovery play. My instincts tell me to steer clear for the time being, with more bad news possible. After all, if they are saying that the full year results will be "materially below" expectations and last year's performance, when they are only at the end of Q1, then that suggests to me that there are ongoing problems.
Equipment hire companies are very operationally geared - the depreciation charges go through the P&L each month regardless of whether any customers have hired the equipment at all. So if operational problems mean that you own the wrong kit, or it's in the wrong place at the wrong time, or you just have warehouses full of kit that customers don't want to hire, because your prices are too high, then there's a big problem.
Will the market be so forgiving after the third plunge in share price? I doubt it.
EDIT: I haven't reviewed their balance sheet recently, but it's important when a highly geared company warns on profits, to check the debt position, and the banking covenants. Even if those are not disclosed, it's easy enough to make an assumption, and calculate how typical bank covenants would look on the revised broker forecasts, like net debt:EBITDA, interest cover, etc.
HSS Hire (LON:HSS)
Share price: 128p (down 5% today)
No. shares: 154.8m
Market Cap: £198.1m
(at the time of writing I hold a long position in this share)
Profit warning - this is actually from two days ago, but I didn't get round to looking at it in detail on Monday 29 Jun, so as it ties in nicely with the warning from Speedy Hire today, let's have a look at it now.
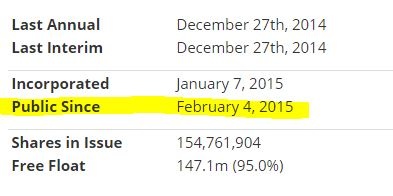
Firstly, I note that Stockopedia has added a useful couple of dates into the StockReport, showing when a share first listed on the stock market - that's really handy, as it saves me having to look it up from the RNS.
As you can see on the left, HSS was listed recently, on 4 Feb 2015, so it's only been a public company for five months, and has just warned on profits. I'm sorry, but that's pathetic. It is inexcusable for a company to list, and then warn on profits within just a few months, but it's an ever-lengthening list I'm afraid of new floats which have done just that.
It makes me ever more sceptical about new issues - and sadly I think the companies & advisers that float these things are possibly more interested in lining their own pockets than in giving investors a fair deal. It stands to reason really doesn't it? If the existing owner of a business (who knows it best) chooses the time, and the price for his exit (or to raise fresh funds), then to take the other side of that trade, you're probably going to be fleeced! That's why I rarely indulge in buying IPO stocks, with only the rare exception occasionally, if I find something really good and sensibly priced.
Current trading - reading it again, it seems to send very mixed messages. If Q2 was only "marginally below expectations", why have the shares been smashed down so far this week?
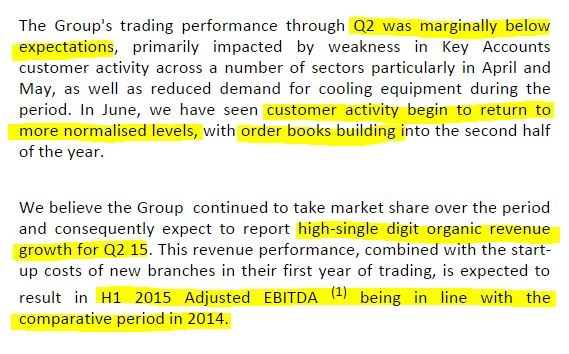
As FT Alphaville pointed out on Monday, the current trading & outlook comments in the last update on 27 May 2015 didn't give any indication that anything was wrong, so questions are being asked about whether the company has adequate internal controls & timely reporting?
Broker downgrades - although the trading update sounds very mild, it seems to have a leveraged impact on the bottom line. So a reminder again as to how operationally geared tool hire companies are.
One broker has reduced their 2015 EPS forecast by a considerable 18% to 10.1p, and 2016 has also been reduced by 16% to 13.7p. If it's only temporary factors in a couple of slightly slow months, I am puzzled as to why forecasts have been downgraded by such a lot for the current and future years.
Another broker seems to have reduced their forecasts by less, but I don't have full details of that.
Balance sheet - this is tricky, as the only accounts available are pre-IPO, so they show a balance sheet groaning with debt, as the company used to be structured on a corporation tax-avoiding private equity basis.
Taxation - note that HSS only paid £2.8m corporation tax in 2013, and £121k in 2014, due to the massive finance charges on the P&L. This structure disgusts me - it's ludicrously easy for private equity people to avoid corporation tax at companies they own. When is this loophole going to be closed?! Who would pay for public services, if all companies went down this tax avoiding route? It's shameful in my view. Anyway.
Net debt - I don't have any up-to-date figures on the indebtedness. At 27 Dec 2014, net debt was extremely high at £288.7m. As part of the IPO deal, the debt was restructured, and £103m (gross) of fresh equity was raised. So if that reduced to say £100m, then simplistically, net debt should have reduced to about £189m.
Net assets were negative -£11.5m at 27 Dec 2014, so add on say £100m net proceeds from the IPO equity raising, and pro forma net assets would be £88.5m. However, there's £170.4m in intangibles to write off, so that takes NTAV down to -£81.9m.
So it looks to me as if the balance sheet is probably quite weak, that the PE guys left HSS with too much debt perhaps?
IPO - I'm just having a quick thumb through the IPO prospectus, and note that the price of 210p was right at the bottom of the indicated 210-262p price range. Also I note that the selling shareholders only got away the absolute minimum of the existing shares they were offering - 5.1m to 44.6m was the range, and only 5.1m were placed.
So it looks like this IPO perhaps only happened by the skin of its teeth? There is now probably a big overhang (37.4% of the company) from the major shareholder, Exponent Private Equity, once their lock-in expires. Although whether they would sell now at 132p is unknown.
Good grief, I've just discovered from page 17 of the Prospectus, that the IPO costs were not £3m as I estimated, they were a mind-boggling £13.5m! That is outrageous!!
Anyway, it would take me all afternoon to work out all the figures on this, so I'll wait until the interim results come out instead!
Vauation - I'm not really sure how to value it, to be honest. All I would say is that the profit warning doesn't sound a disaster by any means, so having the opportunity to buy the shares about 37% below the IPO price, actually looks fairly interesting.
The current share price is about 10 times 2016 forecast earnings, which seems fairly reasonable, although I suspect the balance sheet might be weaker than I would like.
So I took a bit of a punt on it this week, and have bought some averaging 134p. It's not a conviction buy, and I've not fully researched the figures, but it's more of a punt on it being a fundamentally sound company, which has been around a long time, and that generates plenty of cashflow.
Have any readers looked at this company? If so, I would love to hear your views. Is it a bargain, or a dangerous falling knife? I'm not sure at the moment, but am leaning towards it possibly being a fall which has been overdone a bit? Time will tell!
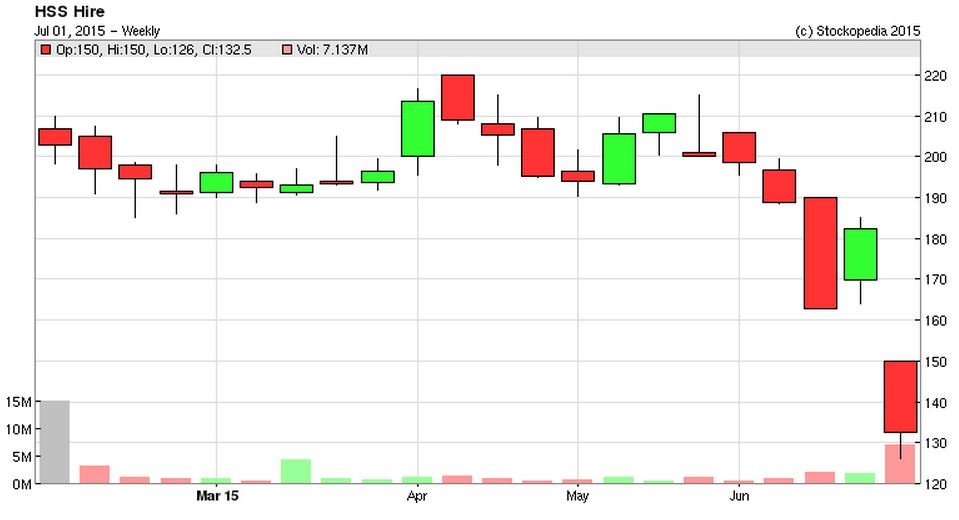
Look how wide the candlesticks are below, which reinforces just how little time this company has been listed. It's bound to take time for sentiment to recover. BooHoo is still languishing 6 months after its profit warning, soon after its float for example.
Topps Tiles (LON:TPT)
Share price: 145p
No. shares: 193.7m
Market Cap: £ 280.9m
Q3 trading update - the share price is level on the day, so it looks as if this update is what the market was expecting.
Q3 sales are up a very impressive 5.9% on a like-for-like basis. All the more impressive, given that it adds to a 6.3% LFL sales increase last year.
On profitability, they say: "management remain comfortable with current market expectations for the year as a whole".
Directorspeak - says they "remain well positioned to continue to grow our market share in the remainder of the year".
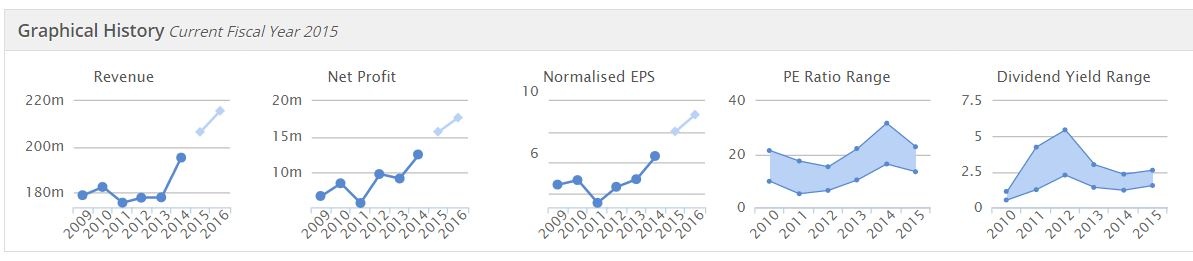
Valuation - this is the tricky bit! As you can see below, Topps is demonstrating a good progression of sales & profits, and it undoubtedly has macro factors providing a tailwind at the moment, and probably for at least a couple of years, I would guess:
So valuing the company really depends on these questions;
- Will the company meet or beat broker forecasts?
- What pricing multiple are you comfortable with?
- Where are we in the economic cycle?
Given that LFL sales are so strong, I would imagine there is a good chance the company could beat broker forecasts. So you could value it based on say 10p EPS forecast for next year (ending 30 Sep 2016).
What multiple? Who knows?! I would be comfortable with 15, but some people are happy to pay pretty wacky multiples right now, so might go up to 20, or even more?
Economic cycle? I think there is plenty more growth to come, as consumer confidence improves, and real incomes rise.
So overall, I'm coming out at a valuation of about 150p, or slightly ahead of the current 145p share price. If you're more bullish than me, and the market agrees with you, then there could possibly be further upside on the share price, but it's not something I would want to buy at the current level, since the price looks about right to me.
Quartix Holdings (LON:QTX)
Share price: 190p
No. shares: 46.9m
Market cap: £89.1m
Trading update - this is a recent float which seems to be behaving itself a lot better than many! Today's update looks reassuring:
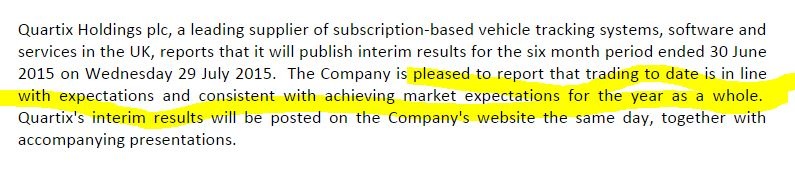
(apologies for the very wonky highlighting, I've just changed to a vertical mouse, as suggested by two readers, to help ease my RSI, but I haven't quite got the hang of it yet. Will come back & replace this picture when I've got the hang of it).
Valuation - considering the good growth this company has achieved, the valuation seems justified. Also note the excellent quality scores, and a dividend yield that's worth having:
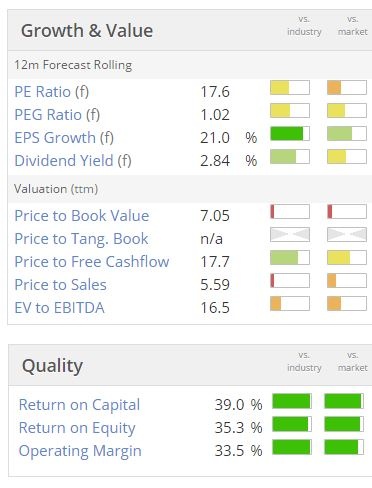
My opinion - I'm not familiar with this company, but it looks potentially interesting, and definitely worth a deeper look I think, as a GARP candidate.
Vislink (LON:VLK)
Directors' Awards - in my view the scheme that has been announced today is an absolute disgrace, and should be rejected by shareholders.
It seems that very generous remuneration packages are not enough to motivate the Executive Directors at Vislink. Chairman John Hawkins was paid £438k in 2014, and £459k in 2013, a helluva lot considering the level of profitability of the group, but apparently it seems this is not enough.
We find out today that, to incentivise him, and two other Directors, to create shareholder value, they want to be given a staggering 15.38% of the market cap of the company, beyond a "hurdle" figure of £85m (which is only 20% more than the current market cap, so over a three year period this only means a target of minimum 6.67% p.a. growth in mkt cap).
Just like huge bonuses incentivised bank employees to take the risks which caused the credit crunch, so I could imagine this crazy incentive scheme at Vislink will incentivise Hawkins to go on an acquisition frenzy, gear the company up to the hilt, ramp the shares to high heaven, so that he can get a massive payday.
Some time afterwards, the company will probably collapse, because so many bad decisions had been made to trigger the incentive scheme payments.
This is an absolutely hare-brained plan in my view, and seems a sure-fire way to destroy the company. As one friend commented this morning, this is a "parody of capitalism".
I really hope shareholders kick Hawkins into touch, or even kick him out altogether. In my view he's a financial engineer, not a talented manager, and this incentive scheme is a good example of reckless, untamed greed.
I'll leave it there for today, and get some practice in using my new vertical mouse! See you tomorrow!
Regards, Paul.
(of the companies mentioned today, Paul has a long position in HSS and no short positions. A fund management company with which Paul is associated may also hold positions in companies mentioned.
NB. These articles are Paul's opinions only. They are NOT recommendations, or financial advice. The emphasis here is on readers doing your own research).
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

34 comments
Thank you to so many of you who have responded by email and not a single one has been complimentary of this scheme and there has been a massive number of private and individual shareholders providing comment, thoughts and background information that I really think is good to share amongst all our group.
Alun at FreeShareData has kindly set up a campaign page to register your interest so that we know when we are ready to go to the Press and Media with a significant part of the shareholding adding the weight behind our cause. You can find the page here and if you click on the blue link titled 'Shareholders: enter your holdings and opinion' you can put all the comment you may wish to add...
http://www.freesharedata.com/vislink-poll
I am sure the Board and advisers will be going to this website too so do not hold back as this is your opportunity to tell them...they did not give us any opportunity in advance as announcing it as a done deal nor did they let us discuss it at the Agm so total disrespect for PIs IMO.
You can put just your Stockopedia or online nickname if you prefer or just your first name and initials but the important thing will be to have your shares ready to be counted and voted on in a couple of months or so after the Summer holidays when we have the maximum PIs available back from their holidays and aware of this greedy scheme.
This campaign will grow and grow and I am sure that you will all know more shareholders who want to back it.
Well done to all of you for showing backbone and the steel that is needed to stand up to such schemes....if only the City and larger institutions were not incentivised by fees and common structures that seem to make them support these things in the first place. We may be small individually but together we are huge....
Do go to the website now and enter your views. I have a feeling this will be a winning campaign and there will be egg on faces !
Vislink (LON:VLK) ; I have posted a letter to one of the non-executive directors and member of the remuneration committee this morning:
Dear Oliver,
I have enjoyed my profitable investment in Vislink since first acquiring shares in April 2013 but as a shareholder, I have to voice my concerns over the recent grant of Executive Directors’ Awards under the 2015 Value Creation Plan.
Whilst not being against rewards for exceptional performance, in this case I have some serious reservations:
- The reward is too easy to achieve; if the share price goes up by just 7% per annum then they are in the money
- It pays out too much; if the share price went up 20% per annum they would share roughly £5m between them
- Where is the downside? I could just about stomach this type of reward if the participants put in some capital at the start which could be lost if the share price was to fall over the period, which would at least align them more with their shareholders, and finally
- I think the benchmark/hurdle is flawed; the AIM All Share could go up 25% per annum for the next three years, the Vislink share price could under-perform, going up only 12% per annum for instance and yet the scheme would pay out handsomely. I would prefer a hurdle that is linked to real value creation; perhaps a combination of total shareholder return, (share price and dividends), improvement in ROCE and cash flow per share. I am keen that the temptation to make decisions that might boost the share price in the short term, perhaps to the longer term detriment of the company, are minimised.
I think this is the type of plan that gives the City a bad name, making the participants look excessively greedy. I would very much appreciate it if you would voice my concerns, which I know are shared by many others, to fellow directors and I urge the board to reconsider the terms of this incentive plan. The Exec Chairman should be offered a new and better structured incentive scheme that rewards exceptional performance from the business over the longer term.Yours sincerely
John Rosier
I considered selling my holding but not for very long! it is better to try and force some change through communication. Also, I suspect the shares are cheap and that the new award has been timed to make sure the participants get on board before the share price resumes its next leg upwards. Hopefully, interim results due in early September will show further progress from Pebble Beach and its link up with GoPro. “Disappointed with the Board” Holder!
I sold out of Vislink (LON:VLK) a few months back but one of the things that made me nervous was the pay of the Directors. Way to high in my view for a company that size
But on that basis you would never have held WPP which has been a fantastic investment. I think directors' pay is something to take into account but I wouldn't base my whole investment decision on it. As I say I think Vislink is probably going to do very well over the next few years; my beef is with the management taking out too much for not enough value creation!
In broad terms, I agree with you John, but a couple of things to note:
a) It is much harder for directors of a largecap, like WPP to screw over minority shareholders.
b) The way directors treat themselves gives a good indication of how their are likely to treat minority shareholders. This is a much bigger risk in smallcaps, where the opportunities for stuffing minorities are greater, e.g. by dilution, taking a substantial proportion of profits for themselves etc.
An interesting case in point was last week's AGM at Telit Communications (LON:TCM) , which I attended. As it happens, I think it's a super company with excellent prospects, but the AGM and remuneration report was one of the worst examples of CG I can recollect! The only director to show up for the AGM was the CEO. When asked, he felt that he couldn't justify the cost of the US based remcom chairman flying to the UK for the AGM, which obviously made it very awkward to raise questions about the CEO's pretty huge package. Irrespective, I did ask why he felt it necessary to pay himself $3.5m last year, when he already owns 20% of the company anyway! [makes the Vislink package pale into insignificance].
Nevertheless, I am not selling out of TCM: a) as mentioned, I think the prospects are excellent; b) apart from short-term pay, the CEO has put his money where his mouth is, by raising his stake in the business (borrowing money to do so), hence his interests are closely aligned with those of shareholders, and he has done a phenomenal job of building the business.
Coming back to Vislink, the track record there has been very patchy & I think Paul is right that the whole edifice could come tumbling down so, combined with poor CG, not one for me. Best of luck with it anyway!
Cheers,
Mark
Hi Mark, I guess time will tell but I think the market is underestimating and undervaluing the impact of the Pebble Beach acquisition on margins, profitability and cash flow. I think using phrases like "the whole edifice could come tumbling down" is a bit over the top!
Sorry did not make ShareSoc last night; did not get back from Bath until after 9:00 pm. Hope it was a success.
John
You are quite right I would miss out on some excellent investments and I would never use it as the sole reason to make an investment decision or not. I just thought it was excessive. Particularly so given the share price was not really moving forward (until the last 3 months or so). You could well be right that the share price will rise well in the short to medium term and I wish you and other holders well. However, you cannot ignore that the Executive seem to put themselves first.
I also think that Vislink capitalises a lot of cost.
Just for clarity I essentially agree with you all. These people are perverting a very good system, I love Capitalism - it works. But you have to remember it is based on competition. The way we measure your success in this competition is through the wealth you make, not necessarily the wealth you create. My point is really how you deal with it and them. Small Shareholders are not the answer. I don't agree with more laws to tell people to stop being greedy. I remember the beginning of compliance after the 1987 crash and the reems of regulation that have followed. "Bad uns" always find a way around these things and 2007/8 still occurred. All I am saying is until we all (and I mean we all) despise this sort of greed, it won't go away. People flock to the money, they don't ask where its come from or how it was made simply you have it so you must be cleverer than everybody else. Change that.......
I've sold my Vislink (LON:VLK). Cannot be doing with management who are just in it for themselves. Good riddance! There are plenty of better businesses out there IMO where the management and shareholders interests are truly aligned!
Just for the record Mr Hawkins remuneration at Vislink is already in the top 10% on AIM and for the size of the company it is in the top 2%. I do not think he is unfairly remunerated and has received very high salary over each of the last four years. This level of reward on top is sheer greed IMHO but others may differ in their opinion.
I think such awards should be voted on by the owners as we are handing out huge numbers of shares in the company and there is no long term guarantee just a market cap hurdle !
Announcing this just AFTER the Agm is disrespectful IMO and happens at nearly every company so a general stance on that is required also.
I totally agree with Paul regarding Vislink (LON:VLK) - it's a complete disgrace!
I think society should be responsible for limiting excess and not small share holders. Small share holders will argue they are getting a return for their risk if one of their investments multi bags. A Manager invests their time and some get good pay and some don't. In Mr Hawkins case if you don't ask you certainly don't get. I think we can all see his game which is one of the great steps forward in our society - increasing transparency and rules to force disclosure. So is it for small share holders to influence this? I don't think it is their function, we invest or not which depends on our judgement on many aspects of the company in some cases this one included. Anyway you will never get them all to agree and so it falls to Fund Managers to make the case. "A case of the pot calling the pan grubby bum" if you'll excuse my expression. Anyway the average duration of most fund managers is quite short.
So it falls to us to educate our children at school in our duties to others in society. At the moment I cannot see this at my boys school which I assume is the same for others. Until we do Gordon Gekko's "greed is good" line will remain salient. Our society rewards those with money regardless of how they got it. Shakespeare taught balance perhaps he should be compulsory reading in our board rooms. Sorry guys my rant for the day!
There needs to be a legal mechanism to enforce this - via the owners - the shareholders.
Any shareholders who agree with Paul and I regarding VLK should make contact with either of us and provide their email contact details as I suspect this one will need looking at very carefully as a test case for private shareholders and what exactly can be done to protect and utilise our very limited rights. If it is clear that a significant number agree and we have over 5% of the company then there will be lots of campaign options open to us.
Hi Paul,
I was appalled when reading the Vislink announcement yesterday. In my view the NED's should be taken to task over this and the Chairman of the remuneration committee, Robin Howe, should be asked to leave. The rest of the NEDs should be scrutinised to ensure they are fit for purpose. Obviously I also think the award scheme should be abandoned.
One implication of this award is that John Hawkins has undue influence on the board due to weak NEDs.
If anyone has good connections with the press I think this would be a very good way to put pressure on the company and a very good story.
Regards,
Peter
(I have a holding in Vislink)
PeterW,
ShareSoc has an excellent and extensive database of press contacts, and I know members of the press are keen on the topic of excessive/unwarranted executive remuneration. If any ShareSoc member would care to draft an accurate but hard-hitting press release on the Vislink case, I will do my best to get it issued to the press.
It may be best to liaise through Carmensfella who, of course, is a fellow member of ShareSoc's Board. I believe David has his own thoughts on how best to tackle the "Vislink problem". Contact us through Stockopedia's messaging facility (click on our Stocko usernames & select "msg")
Best,
Mark
Agreed 100% Paul. The previous share incentive scheme at Vislink was very generous, perhaps too much, but at least the criteria was based on EPS growth. As you say, Pebble Beach saved their skin and shareholders have had a decent run in the past two months as a result.
However, just basing it on market cap for a company that has announced that it intends to make more acquisitions (historically around 1 per year) is disgraceful and very anti-shareholder IMO.
As Warren Buffet points out, directors incentive schemes are really like options - all the benefits of the updside but none of the downside that shareholders have to worry about. This fits the bill as an extreme case in that the company doesn't even need to generate further shareholder value but only bolt-on acquisitions of sufficient size.
What do you think is the best way for this to be challenged? I suspect a few people emailing them will have no effect. I'm seriously considering selling the remainder of my holding. VLK was my biggest position a few months ago.
That is the crux of the issue really, how do Private investors actually get to challenge these incentive schemes? There seem to be more and more of these getting slipped out recently with very low hurdle rates that will give rewards and only require mediocre management to achieve , I would lump the recent Sprue Aegis LTIP into the same mould. The best inventive plan in my opinion is one where management have a decent stake in the business and thus get rewarded in exactly the same way as all other investors.
With regards to Vislink surely a reasonable growth in the company of say 12% a year which investors deserve to help their portfolios balance out some disasters would mean over three years the market cap could be £100m and so the directors would pocket nearly £3 million for very average returns to shareholders.....potentially they could pocket tens of millions as there is no cap at all. Why not ? Who within the larger shareholders were consulted on this and consented ?
The really annoying thing about most of these very large awards is the actual timing....it has been announced and set just after the Agm which is totally disrespectful to the private and individual shareholders who of course have just the annual meeting to challenge or consult directors on remuneration. Over 60% of shareholders in many small companies are the likes of you and me but do we ever get consulted on these awards ? Do directors put them before shareholders at the Agm for acceptance ? Do they allow us to consult with the Remcom ? Never in fact the cowardly $%£&*£s usually announce these things just days AFTER an Agm to make sure they keep us totally out of the loop for another year !!
If you check carefully in the Annual report after his initial appointment John Hawkins had a clause inserted in his contract that stipulated his executive duties would be for 166 days per year so technically he is not even full time ! I think the previous management at Vislink were very poor and took out huge salaries and bonuses. These guys may be better for shareholders but the excessive reward culture clearly remains !
Remuneration reports and those who fuel them such as advisers are paid for by the shareholders via the Board....sadly they take up more space in the AR than the actual business summary of the company itself ! Where is capitalism going ?
There has been a big change in income inequality over the last 25 years, driven by the high rewards given to corporate executives and there is little correlation between executive compensation and the creation of wealth for shareholders. The FTSE is barely up over that 20 year period, the workers have seen wages probably increase slightly ahead of inflation but I promise you that directors in listed companies have engineered massive compensation way beyond their performance and multiplied their salaries ten fold if not more in some cases !
David,
Well said, I couldn't agree more. It sickens me that so many company Directors ruthlessly strip out costs from their companies (usually sacking people, and holding down wages for those that remain, and using agency temps to replace better paid permanent staff), whilst at the same time absolutely robbing the company blind themselves with crazy salaries, bonuses, pension contributions (when the workers don't have any pensions!), and then on top of all that, they dream up greedy ways to further feather their own nests like the one announced today by Vislink (LON:VLK).
I don't rate the Exec Chairman of Vislink at all, and that's why I sold my shares. He's addicted to doing deals, and it was only the Pebble Beach acquisition which saved Vislink's bacon at the last set of results.
The balance sheet is filling up with goodwill of course, and often acquisitions go wrong after a while.
I think this type of greedy, self-serving management are a scourge on corporate Britain, and should generally be avoided, as they usually screw things up in the long run.
Whereas I know we both like conservatively run, family controlled businesses, which are run for the long term, like James Latham (LON:LTHM) and others.
I really hope shareholders reject this awful incentive plan at Vislink.
Directors should be paid a sensible salary (say £100-200k p.a. for a business the size of Vislink), and do the job to the best of their ability. There's nothing wrong with a few share options either, to give them say 1 or 2% of the company if they do a great job, but that's all that's needed and justifiable, in my view.
Regards, Paul.
Paul - sent you a PM
Rgds
Vegpatch
I agree with most of what you say re the Vislink incentive scheme.
I have no problem with "reward" plans in general but as a shareholder I would expect the directors to be working very hard on my behalf anyway. In this case the target seems far too easy to achieve and pays out too much, making them look very greedy indeed.
My main concern however, is with the benchmark; the equity market (AIM All Share, FTSE All Share; choose whichever you like) could go up 20% per annum for the next 3 years in which case they would, in Robert Peston speak, "pocket" a tidy sum if VLK just performs in line and they have not actually created any excess value over the market as whole. There should be a proper benchmark rather than just market cap! (eps, cash flow per share, ROCE)
In short I would prefer a proper "value creation" based benchmark and also for it to ratchet up. i.e. 20% gain gets a little, 30% more and 40% even more.
I think however, you are little harsh describing him just as a "financial engineer, not a talented manager"; I grant you he has made acquisitions along the way but I think they do fit into a clearly defined strategy which has in my opinion improved the overall quality and growth prospects of the company.
I'm keen on the stock, have done very well out of it and still think it looks good value. I think that the benefits of recent acquisitions, especially Pebble Beach Systems, are about to come through which might explain the timing of this new incentive scheme. Jump in the elevator before it starts moving!
So as a shareholder, rather than throw the baby out with the bath water I intend to voice my concerns, see if changes can be made and if necessary vote against it.
Hi Paul
I looked at HSS Hire (LON:HSS) at the time of the IPO and thought it massively over priced then. There is far too much debt, and there is too much competition from a host of local rental shops who have built up loyal customer bases. Expansion would logically come by acquisition, and that would require fund raising. The margin figures seem comparatively quite good, but given that they are pre-IPO statistics I am taking them with a fistful of salt. In the 130s it is, I think, priced about right. Any profit would depend upon growth or massively increased efficiency. As such it represents a gamble I am unwilling to take (but no doubt there will be money to be made trading this in the shorter term). Speedy Hire (LON:SDY) and Lavendon (LON:LVD) represent better buys in this sector for the investor.
I may have read the Vislink RNS wrong, but it appeared to me the execs will get 15pc of the mkt cap above the hurdle mkt cap of £85m, not 15pc of the whole firm. These schemes are never clear, possibly on purpose!
Hi TMF Mayn,
Yes, that's right, as I explained in the article above:
We find out today that, to incentivise him, and two other Directors, to create shareholder value, they want to be given a staggering 15.38% of the market cap of the company, beyond a "hurdle" figure of £85m (which is only 20% more than the current market cap, so over a three year period this only means a target of minimum 6.67% p.a. growth in mkt cap).
I'll put in some additional bolding in the article to emphasise the hurdle, as it looks like you missed that when you read my article the first time?
Cheers, Paul.
Sorry, last comment re the sheet should read many years, not just 4!
Re LVD a sheet I have followed for 4 years and have found to be very profitable in the long run had the following comments to make in their May issue.
A confident Q1 trading update from Lavendon. Despite relatively modest growth in revenues of just 1%, efficiencies mean that Lavendon expects much faster growth in profitability, margins and return on capital employed. Keynotes were the UK trending higher towards the end of the quarter whilst efficiencies have driven profitability; the Middle East has continued to storm ahead (+11%) with the weaker oil price environment not really affecting activity. Other European territories are unchanged on last year.
At current share prices, Lavendon’s days of independence really do look numbered. Additional equipment has recently been added (ahead of schedule, temporarily lifting net debt to £103m) but the wider investment community hasn’t picked up on the fact that the frantic investment programme will start to peter out towards 2017 as a huge chunk of the fleet will have then been refreshed, after which this company will throw off a tidal wave of cash.
Any would-be-predator would be wise to bid now whilst the shares remain so undervalued. Buy.
As some have said, maybe the others are losing share to some, perhaps LVD even, so I am reluctant to sell at this stage, but would be interested in your comments on LVD, Paul.
If my road is anything to go by, the building and plant hire sector should be booming. I've got two extensions, two loft conversions, and a replacements windows going in, all within a 3 minute walk.
I think the stamp duty changes have encouraged people to upgrade rather than move.
Paul, Thanks for the HSS review. I did think the fall was overdone but the amount of debt worried me so i did not invest. Now the election is over and the Tories are in then the building sector should now pick up?
thanks for these articles Paul. I have sold my holding in LVD.
On another subject I read your article about China and the chinese stocks on Aim. I hold GTS Chemical which looks very good value with P/E of 6 or so and a growth industry albeit specialised. We will see. Peter.
PeterRussell, I have no knowledge of GTS and it may be that it is a rare 'kosher' Chinese AIM company. But in my experience you have to assume that EVERY Chinese AIM company is a fraud. Even if it is audited by reputable British accountants, and pays a hard cash dividend, this is far from a guarantee of being legitimate, as Naibu Global International Co (LON:NBU) Naibu holders found to their cost! Also worth considering that even if you believe their accounts and it is on a P/E of 6, then given the high risks in this type of company, it might never make it much above a P/E of 6... Anyway up to you of course, no advice intended, and good luck with GTS.
I did read there was a slowdown in building due to the election, so that may explain why May was soft?
Hi Paul - do you think that there is any read across between these businesses and Lavendon?
Hi DLG12,
That's the question isn't it! I noticed that Lavendon (LON:LVD) shares had fallen in sympathy this morning.
One of the broker notes said that equipment hire had been soft generally in the UK in May, so there might be some read-across to Lavendon possibly? Although they operate in Europe too.
If two competitors warn, in rapid succession, then personally I would lighten the load if I held any other stocks in this sector. But who knows? It could be that other competitors are winning business at the expense of HSS and SDY, we don't really know. Tough call!
Regards, Paul.