Small Cap Value Report (1 June 2017) - FLTA, HYNS, WJG, ALFA

Good morning!
Feel free to send in requests and I will cover what I can.
Thanks,
Graham
Filta Group (LON:FLTA)
- Shares price: 100p (+8%)
- No. of shares: 27 million
- Market cap: £27 million
I'm flagging this up as it's new to me and is another fairly recent flotation (November 2016).
According to its website, the core product is FiltaFry, which enables 5,000 food establishments to recycle their cooking oil. Two other subsidiaries are involved in providing refrigeration door seals, and general maintenance of refrigerators and air conditioning units.
Sounds like a "boring" industry which Peter Lynch would approve of!
Unfortunately, the company generated a loss last year (£200k), on revenue of £10.1 million. Adding back finance costs, AIM admission costs, and "special bonuses" to shareholder-directors, gets you an "underlying" operating profit of £1.15 million.
Today's update is concise but encouraging:
"We have enjoyed a strong start to the year with revenues for the first 4 months, on a constant exchange rate basis, over 25% ahead of the same period last year, with all of our business lines, franchise development, fryer management services and Company-owned operations contributing to the growth.
The statement mentions new customers secured last last year, who are going to provide a full-year contribution in 2017, and describes how most company revenue is recurring in nature.
Overall, looks to be the type of boring stock which can often turn out to be a good investment.
I can see a broker forecast from April suggesting that 5.9 EPS could be achieved this year. Perhaps that forecast will be revised upwards, and this might start to look decent value?
A few other small points worth mentioning: it fulfilled its promise to pay a dividend in the first half of this year, and has pledged to pay interim and full-year dividends going forward.
It operates a franchise model - that's something that always gets me interested, because it means potentially high returns on capital (if you can get the franchisees or banks to put up the capital to fund local operations).
The balance sheet is no fortress but it looks ok, equity of £3.4 million or £0.9 million excluding non-current assets. £4.4 million of cash offset by £1 million in bank loans.
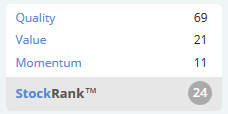
I'm tempted to dig a bit deeper into this. The StockRank isn't any good yet, perhaps due to the short history on the market, and lack of reported profits yet (Value) and the weak share price movement so far (Momentum):
Haynes Publishing (LON:HYNS)
- Shares price: 181.5p (+11%)
- No. of shares: 15.1 million
- Market cap: £27 million
This share has been covered frequently at Stockopedia, and not only in these reports but also with a great write-up last month at this link.
I covered it before with the share price at 117p and 138p, so arguably I should have been participating in this rally, but I didn't have enough confidence in long-term demand for the company's core products: manuals for automotive repair (DIY and professionals).
A wholesale restructuring and a refreshed management team have turned it around:
The Group has seen strong second half trading from its European operations and benefited from a lower cost base in North America and Australia following the restructuring announced in May 2016. Like-for-like profit before tax and exceptional items for the 12 month period, excluding exchange rate movements is expected to be up to 15% ahead of the prior year.
So 15% LfL growth rate on last year's £1.9 million adjusted PBT works out at £2.2 million in adjusted PBT, before the effect of exchange rates.
Including exchange rates and acquisitions, adjusted PBT is up a stonking 40% (since the foreign revenues translate to a lot more GBP now). So that's about £2.7 million in PBT.
Elsewhere, gains on some freehold property disposals are set to pay for some miscellaneous exceptional costs this.
Even after the rally, therefore, the rating seems pretty reasonable here at a £27 million market cap. It has done well to transition many of its services online, and demand for its products remains firm.
It does have an accounting pension deficit of £21 million (see that Interim Report), so that's likely to have an impact on cash flow available to shareholders unless interest rates can rise.
Pension deficits aren't considered very important in valuation, because companies can take their time paying them off (and pension fund trustees don't want to take so much cash out of an operating business that they kill the company). But I'd still be inclined to conservatively add a decent chunk of a pension deficit onto a market capitalisation, for a fuller sense of valuation.
But well done to those who have been holding Haynes through the recovery. I can see it rising a further from here and potentially having much more stable results in the years ahead, without all the large exceptional costs of recent times.
Watkin Jones (LON:WJG)
- Shares price: 183.6p (-2%)
- No. of shares: 255 million
- Market cap: £469 million
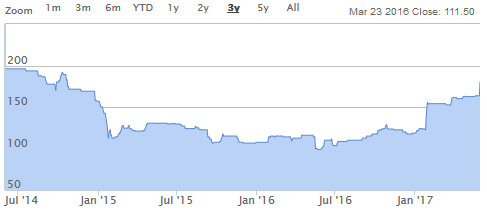
Not feeling too smart today, as this is another one where I missed the boat, arguing that the share price was fairly valued last December (at 117p!)
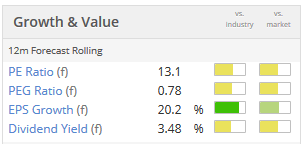
Specifically, what I said was that since this property developer only takes on about 10-12 projects per year, there is a lot of variance in the potential outcome, so that a low rating is needed to compensate investors for taking on that risk. A cheap-ish PE ratio of about 9x seemed fair enough to me.
The shares have re-rated since then, to 13x, and the Value Rankhas correspondingly fallen to a lowly 31/100 (Quality and Momentum scores are still high).
Today's interim results show revenue down but margins and PBT up. Revenues are in line with management expectations, and are forecast higher in second half:
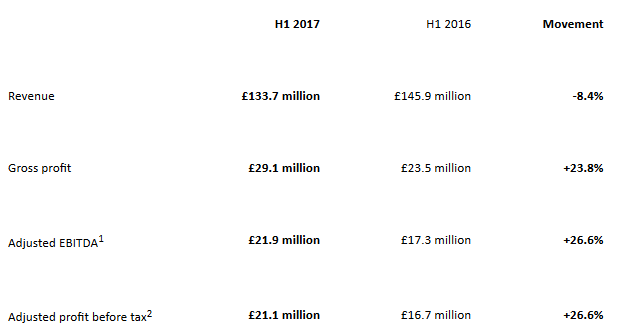
Gross margin is up nearly 6% (from 16% to 22%), reflecting "the location and quality of student accommodation schemes in development, as well as a full six months contribution from Fresh Student Living."
Checking my prior notes, I see that WJG delivered 3,800 beds ahead of the 2016/2017 academic year, whereas 3,300 are to be delivered for 2017/2018 and 3,400 for the year after that, and 3,500 the year after that.
So that's fairly stable planned output, at a lower level than 2016/2017.
Excluding the group's other activities, therefore, growth will depend on margins achieved. On the value of the locations of upcoming schemes, on their particular features, and their successful execution.
Shareholders reading this report may well disagree with me, but I do think that developers such as WJG should have modest equity ratings. There are many forces beyond their control, and it's difficult for me at least to understand what sort of long-term competitive advantage can be achieved.
The CEO's trust along with the CFO sold nearly 20% of the company in a placing in March this year (when the shares were 145p). Unlike my stance on Haynes, therefore, I now suspect that these shares are overvalued at 180p+.
Alfa Financial Software Holdings (LON:ALFA)
- Shares price: 418p (+2%)
- No. of shares: 300 million
- Market cap: £1,254 million
Flagging this stock as having hit the stock market last Friday. It was something I mentioned pre-IPO.
This is a software company serving the asset finance industry, with banks and major car companies among the customers.
The offer price according to the Prospectus was 325p, but with the shares at 418p now, the market cap is in excess of £1.2 billion.
This is not in small-cap territory at all but I would agree with ramridge in the comments that it appears to be severely overvalued versus revenues of £73 million and adjusted EBIT of £33 million.
The selling shareholders (Exec Chairman and CEO) took a £29 million dividend before the IPO and sold £250 million of stock in the IPO itself.
Two of the co-founders sold their shares quite recently: 36% was sold for £29.4 million in September 2015, and 20% was sold for £25 million in May 2016. So these deals valued the company at £82 million and £125 million, respectively - less than ten times the current market cap.
On that basis, and on the basis of the implied valuation multiples using last year's results, this is a share I'd be really interested in betting against.
Nothing else lighting my fire today, so I think I'll leave it there.
Thanks for reading!
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

47 comments
Based on a quick look at the parameters ALFA still looks pricey at 185p given the presumed analyst forecast revisions to come - you really need to believe the story here.
Phil
Who was it said history doesn’t repeat, but it sometimes rhymes? (Mark Twain, I think).
Same day (June 1st) but a year on, Alfa Financial Software Holdings (LON:ALFA) came out with a mid afternoon profit warning today taking the shares down over 40% to 185p. Seems like several major contracts are delayed (but obviously not the company management’s fault).
https://www.stockopedia.com/share-prices/alfa-financial-software-holdings-LON:ALFA/news/alfa-financial-soft-trading-statement-urn:newsml:reuters.com:20180601:nRSA0667Qa/
Reading the original commentary from Graham and the following thread, we can’t say we weren’t warned.
Gus.
Any chance of Paul or Graham giving some Broker forecast info on this as there is no data on Stockopedia - Looks like a great Short.
Sólo te estaba tomando el pelo, nada más!
But pretty good list there, for sure.
Bonne soirée.
thanks Ed.and Carey
For all GAW holders, there's a fab positive update announced just over an hour ago... oddly not at the usual 7.00.
Profit before tax expected to be "not less than 38m", which compares to 17m last year! Revenue up to 158m from 118 last year.
Hi Graham/Paul,
Is it possible to look at Telford Homes? The results came out on Wednesday and were looking pretty strong, dividend increasing by 10%ish. Stockopedia rating of 82 (as of 02/06/2017) but still 1 screen is recommending shorting?
Really enjoying the articles, very informative and good fun too.
Regards,
James
Hi James
I held Telford Homes (LON:TEF) but sold shortly after reading the final year earnings report. I wasn't impressed with the outlook and I think their strategy is a bit wobbly given recent government action. Some quotes from their report:
Confidence in this area of the housing market has been shattered recently with government tax hikes and Brexit uncertainty.
The outlook statement looks pretty poor too:
So they are looking to expand into a market with low investor confidence... I can appreciate the uncertainty will be temporary (2-3 years, until Brexit is sorted, maybe?) but given my investment time horizon, that's too long for me, so I've sold.
If confidence picks up in the buy-to-let market then I would be willing to re-invest because the valuation looks attractive at the moment.
As always, DYOR - this is not investment advice. Hope it helps!
Hi Graham/Paul, any chance of you having a quick skim of the trading update for OPG Power Ventures (Indian power generation company). Trading update was 2 days ago I believe. The share price has come down an awful lot over the past few months.
Many thanks. DH2.
Dieselhead, thanks for mentioning OPG... I held these a little while ago before selling at a moderate profit, the sentiment was since affected largely by a big spike in coal prices, according to their more recent reports these prices are now on the decline for the foreseeable future. I wonder if there is some negative sentiment to their coal-fired plants based on climate-change concerns... but this is balanced by their solar developments.
Other factors were a lowered revenue guidance of around £6m due to a result of the effects of taking out of the system high denomination currency, the death of the Tamil Nadu Chief Minister and a cyclone in December.
However, with the interim EFS was 4.8p +41% and what seem to be positive updates since to me the price now seems staggeringly low.
Hi Graham, could you or Paul cover Haike please. I know it's a Chinese aim share which sounds terrible. But it's today released excellent results and a very upbeat current trading statement. Market cap is , even after today's rise of 30% , about £13m but it's expected to make 4.5m this current year. I get that number form today's announcement saying they have made 1.5m in first 4 months of this year. I've had them along time and really feel this one is the exception! Oh and they have little debt and increasing cash generation. It's a value play.
On Watkin Jones - I agree with Wombat .
Although the nuber of student units is going to be slightly lower , The selling price forward is well up per unit and forward margin should be well over 20% if you do the maths .And there will be a modest and growing contribution from Fresh Living kicking in. And an interesting move into BTL with financial backing.
I am not sure about 14P EPS in the current year but over 12P looks well achievable .
I bought my initial holding after seeing Graham's original note when they were 117P and did some research and liked what I saw. (Thanks Graham). Having bought steadily on the way up I feel that I was due a sizeable top slice as I think WJG is high enough for now . Having said that , I think they have a good business model and forward prospects are excellent.
I believe (and hope) that you underestimate the strength of the business model of Watkin Jones. They are not taking development risk in the usual RE sense though if one of their backers went bust then they would be at risk. i.e. they are non-speculative specialist student accommodation developers who effectively propose/start developments and pre-sell them to financial (institutional) funds. They do have a growing build to rent business largely on the same model which is beginning to support most of the growth. Half of their 31 sites under development are forward sold with another 9 in legals. They should make around 14 pence this year I believe and that is only the year to September 2017. Unless things go badly wrong (Labour winning and university incomes being badly squeezed perhaps) there should be more to come for September 2018. And the balance sheet is strong. I feel this is a really high quality company in a niche business with competitive advantages. If they continue to deliver, as I think and hope they will, there is plenty of upside left. (holder)
I agree with this. It's the potential of using their development model in the wider rental market outside student accommodation that appeals to me. Having added to my initial holding I think I'll just sit still on it for a while.
Anyone know any reason for the drop in Taptica International (LON:TAP) today, down 8% today?
Hi Graham, Would be interested to know about Hydrodec (HYR).. Its a micro-cap and results were published few weeks ago...
@tripuram02 - here's the StockReport http://www.stockopedia.com/share-prices/hydrodec-LON:HYR/?auth=accb75c3379302c5442ac47fd8df69f6
Hydrodec - long history of disappointing. I did hold at one time many years ago and lost a bit as a result. Looking at the stock report it doesn't seem to have got any better.
There are better places for your money IMHO
Hi Graham
What about your comments on PPIX. Is it good value?
Thanks for flagging up £FLTA
Hi Graham. Thanks for the Haynes Publishing (LON:HYNS) coverage and the link to my write up. Very pleased with Trading Statement and expect further good progresss.
Would love to get a second opinion on Laura Ashley ( Laura Ashley Holdings (LON:ALY) )
It keeps getting cheaper and cheaper without much news flow.
Re ALY, considering the following statement back in February, it may be that the market is figuring that there may be further bad news:
Trading conditions have been demanding during the first six months of the year ending 30 June 2017. The Board have reviewed the first half results and forecasts for the remainder of the year to 30th June 2017 and, given the continued market challenges, feels that net pre-tax profit for the year will fall below market expectations.
So given already a profit warning and demanding trading conditions, things hardly look great. I'm no accountant, but the cashflow in the interims looks appalling and doesn't even cover the dividends.
Here is a third opinion:
ALY for me is a play on S.E. Asia and Singapore real estate. The Laura Ashley designs are popular with a rising middle class imitating developed world culture. Emerging markets are the place to be since Brexit and Donald Trump. Real Estate in Singapore may fluctuate short term but ultimately wil rise because the city is a business hub and the authorities make sure the streets are ultra-clean.
I have sold any holding related to London real estate because office occupancy is likely to decline when Brexit bites in a few years time. This may be compensated by foreign bargain hunters if the pound reaches parity with the dollar. The proximity of Singapore to China gives me more confidence.
Khoo Kay Peng, the dominant Malaysian shareholder is a plus for me 1) because he wants his dividend even if the company cannot afford it and 2) he wants a flagship building in Singapore.
By all accounts the U.K. Laura Ashley store offering is badly managed and over-priced. My jury is out on the hotel offering i.e. have not investigated it.
The share price decline, however, tells me a lot. No one has any confidence.
Khoo Kay Peng may have to sell assets to pay the settlement of 64m to his ex-wife.
The company is adrift.
Once instituional investors capitulate on high volume I shall buy some more.
Aflash, buy a Singapore property company direct if you want exposure to that market.
Or a trust of some kind with exposure to that market, there are quite a few of those.
Exactly what are Laura Ashley Holdings (LON:ALY) doing with that building? Using it all? Renting space out? To whom?
There certainly seems not to be any take-off of any scale in their own business in Asia.
Btw, re "proximity", Singapore to China is at least four hours by plane, it's not just round the corner.
Laura Ashley Holdings (LON:ALY) was analysed thoroughly on Stockopedia two years ago and its weaknesses fully exposed.
Nothing since then has indicated either improvement or any coherent and effective plan for change.
Tan Sri Khoo Kay Peng is a "plus" to Laura Ashley? I'm very surprised you say that.
My knowledge of Malaysia and of his track record would lead me to quite the opposite conclusion.
His personal situation complicates things even more, the possible consequences of his divorce,
perhaps also whether there could be some other complication in the future ownership of Laura Ashley Holdings (LON:ALY) from Tan Sri's eventual disposal of his assets (although that is pure speculation on my part, please note).
Yes, everything has a price. Yes, the brand name ought to be worth something.
Perhaps there may be value here, once Tan Sri and MUIB are fully out of the picture.
Edit: This property "investment" has probably lost value (as was entirely foreseeable, given the parameters of the Singapore property market, as was pointed out two years ago):
https://www.ura.gov.sg/uol/med...
OFFICE SPACE
Office market at a glance:
Prices and Rentals
Prices of office space decreased by 4.0% in 1st Quarter 2017, compared with the 0.6% decline in the previous quarter (see Annex A-1). Rentals of office space fell by 3.4% in 1st Quarter 2017, compared with the decline of 1.8% in the previous quarter (see Annexes A-3 & A-5).
Property Price Index of office space
https://www.ura.gov.sg/uol/med...
Aha! Some one is alert!
As I wrote my comment I convinced myself of the opposite!
Il valait mieux attendre les réactions cependant, surtout celle de la qualité de notre Jane Bolacha!
En effet demain je replace mes ordres,
Tomorrow I shall renew my orders for:
Keppel REIT Singapore market cap 2 356 278 $ (singapore $ or US$?)
and
Suntec REIT Singapore market cap 3 056 936 $
These I found a few months ago but was trying to buy them a little cheaper.
Both are over the counter in New York under the symbols KREVF and SURVF.
It is a bit of a Crowded Trade, however, the price is up with events.
So the cheap and unloved Laura Ashley ALY still has a place in my portfolio but only for a Short Covering bounce once it falls off a cliff.
Saludos cordiales
Hasta la proxima
Aflash,
Oui, voilà, bien triste, n'est-ce pas, passer les dimanche après-midis sur Stocko?
Bonne chance, suerte, boa sorte, good luck!
come on now, Jane, Stockopedia provides hope.
It is better than:
arguing with your family
mowing the lawn
sitting in a traffic jam
waiting for a plane/train/bus
going through airport security
being in a doctor's waiting room
getting drunk
drinking coffee in the afternoon
wasting time in front of a television
using a balayeuse
going through old papers trying to decide what to throw out
Amy other suggestions?
Just compiled and submitted my 2017 tax return online .... now that was a waste of a sunny afternoon!
Gus
Not if it included a reveiw of stock market profits and capital gains exemptions. Anyway the sun can cause skin cancer.
Hi Graham. It was yesterday's news but would be very interested in your take on IG Group (LON:IGG)
I am a holder
Hi Ben, I'm also a holder of IGG but it's not really in my remit here. I will see if I can cover it elsewhere.
Graham
Fair play, it would be stretching the definition of small cap somewhat. The fact you also hold is reassuring enough. It's only a relatively minor, opportunistic holding for me anyway.
I had a quick look at IGG... they look pretty subdued growth-wise, albeit with a reasonable dividend...?
I thought 7% revenue growth wasn't too bad given the relatively modest valuation but I appreciate the effect of new regulation has not come into play yet. To be honest I did only buy them after the big CFD crash as I felt the risk/reward was very favourable. I'm sitting on a 20% profit now so contemplating cashing in my chips as it's probably not a company that would have interested me much if it weren't for the unique circumstances at the time. Selling is not my strong point however, almost everything I have sold in the last year has continued to go up, Laura Ashley Holdings (LON:ALY) aside. I guess that's par for the course in a raging bull market.
Hi Graham
I would be interested in your thoughts on RM. It announced that the proposed purchase of the education and care business of the Connect Group was given clearance this morning and will complete at the end of the month. The investment metrics for RM, which continues in recovery/turnaround mode generally look good as it moves away from low margin activities.
The acquisition, which is sizeable is said to earnings accretive. However RM does have a significant pension deficit and faces some headwinds with tightening school budgets.
Regards
John
Hi Graham,
Was Wondering if you had any thoughts on the latest trading update posted by Haynes Publishing (LON:HYNS), I noticed you have reported on this share in the past. The share price has gone up over 11 percent on the update posted today. It seems that further progress is being made in the turnaround of the business.
Regards,
Tony777x
Hi Tony, covered it.
Cheers
Graham
I was interested to hear about admission costs.
I think I saw on the Revolution Bars (LON:RBG) opening accounts showed that their admission costs professional fees reached a staggering circa £4m (its in their notes for exceptional costs).
There are a lot of costs which won't be obvious to many, but the cost of being admitted is no small matter nowadays. Basically it seems you can't do it for much less than £1m, it seems. So rich pickings for the various parties involved.
Hi Graham,
I would be grateful to know your views on Watkin Jones (LON:WJG) who issued a half year report this morning.
http://www.investegate.co.uk/watkin-jones-plc/rns/half-year-report/201706010700067768G/
I'm a holder.
I'd second this.
I'm also interesting in Watchstone (LON:WTG) if you have time Graham. The SP today suggests the market is unimpressed, but the results look sound to me, and the balance sheet solid. I guess the cash flow might be the problem. This seems to be due to a Decrease in trade and other payables (note 9) but looking at the balance sheet it seems this is broadly similar to what happened last year. The narrative confirms. I can't see what else might dampen enthusiasm, so at the moment remain bullish. However I'd like to hear your view (and any comments from the usual expert contributors in the comments). Thanks.
(I've a modest holding. Might top up sometime).
Covered it, John
Regards
Graham
Thanks Graham for your thoughts on Watchstone (LON:WTG).
Morning Graham Re. Alfa Financial Software Holdings (LON:ALFA)
You flagged some weeks back this potential IPO. Well, it made its debut on Friday last. I had a look at the admission doc and the shares seem to me well over valued.
Wonder what you make of it.
Can only agree, covered it now Ram.
Graham
Hi Graham - re. Alfa Financial Software Holdings (LON:ALFA) many thanks for covering it and I am glad to see that you agree.
Looking over my notes, management took massive share-based payments in the last financial year totalling £16m which is about 50% of pre-tax profits.
Even after assuming this to be a one-off exceptional, then on current share price, PE = 56, Price/Sales = 18 ; EV/ EBITDA = 73.
And there are people buying these shares today...