Small Cap Value Report (10 Feb 2015) - ENTU, HRN, SIM

Good morning! I'm looking forward to Ed's next webinar here, at 12:30 today, explaining more about StockRanks - a proprietary Stockopedia system which I am growing in confidence about, as it has already established a very good track record. It tends to favour stocks which fit many of my criteria too (a lot of my bigger holdings seem to have high StockRanks), although personally I like to apply additional filtering to exclude companies with weak balance sheets. I'm very happy that StockRanks provide an excellent starting point for a shortlist anyway, so it is not only steering us away from shares that are likely to underperform, but also saves a lot of time. I'll be out of a job here if StockRanks gets too good!!
Entu (UK) (LON:ENTU)
Share price: 121.5p
No. shares: 65.6m
Market Cap: £79.7m
Final results - for the year ended 31 Oct 2014. These are maiden results as a listed group, since Entu floated on 30 Oct 2014. It is a group of home improvement companies - e.g. replacement windows, conservatories, boilers, solar panels, etc.
I flagged up this company here on 15 Dec 2014 when it issued a positive trading update, so results this morning were expected to be good, and they are. Very good actually.
Trading - turnover is up 24.6% to £119m, and pre-exceptional operating profit up a tremendous 69.5% to £10.3m. Note 4 to today's results (segmental analysis) shows some dramatic shifts in profitability by division. So the home improvements division (which is nearly 71% of turnover, at £84.3m) generated a relatively modest operating margin of 4.5%, with operating profit of £3.8m (up 6.3% against prior year).
The energy generation & saving division saw operating profit shoot up from £0.2m to £1.8m. A similar strong rise in profits occurred at the Insulation division, where profit shot up from £0.4m to £2.7m.
I have put a call in to the company, to get a bit more flavour on what has driven these strong increases in profit at two of the smaller divisions, so will report back later if there is anything interesting to convey.
Valuation - adjusted EPS came in at 12.3p (up 57.7%), which is ahead of broker consensus, which was for 11.97p. Therefore the shares are only rated on 10 times historic earnings now, which seems a very reasonable price for a business that is performing well.
Broker forecast is for 13.26p for the current year (ending 31 Oct 2015), although I wouldn't be surprised if the forecasts are increased as the year goes on. Personally I'm thinking in terms of 14-15 EPS for this year. If I'm right, and assuming a more fair PER of say 12, then that gets me to a personal price target of 168-180p. That's 38-48% upside on the current share price, so very much worth sitting tight on my existing shares.
Dividends - better still, Entu is committed to paying shareholders handsomely for waiting. One of the reasons I bought these shares shortly after the IPO, was that the admission document stated the company's intention is to pay an 8% dividend yield (based on the IPO price of 100p per share).
That commitment has been reiterated today, and the company has also paid a 1.5p starter dividend, which is on top of the intention to pay 8p divis for the y/e 31 Oct 2015;
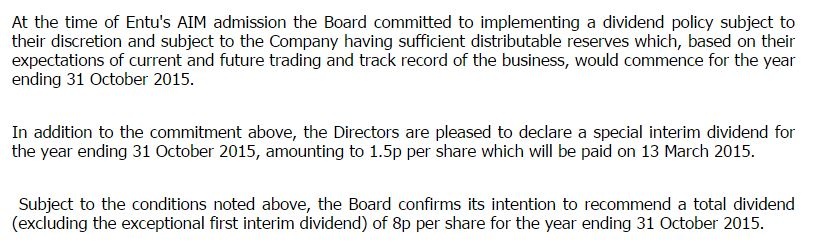
So whilst there is wiggle room in that statement, it's pretty clear that the company wants to, and intends to pay generous divis.
Balance sheet - the company generated strong cashflow in the year, and ended with net cash of £5.8m. Overall the balance sheet is surprisingly thin, with only £0.9m net assets, and minus £0.8m net tangible assets. Normally that would be a red flag for me, but in this case the company's business model cleverly outsources production. So the suppliers provide nearly all the capital needed. That leaves Entu sitting in the middle between customers & suppliers as a sales & project management operation.
Not only is this model capital light, but it is also flexible - so the company can downsize in a recession fairly easily & without onerous costs. I like this business model, as it seems to eliminate much of the risk for shareholders.
Outlook - this sounds positive to me, and I like the emphasis on more organic growth. A bank facility exists for bolt-on acquisitions too;
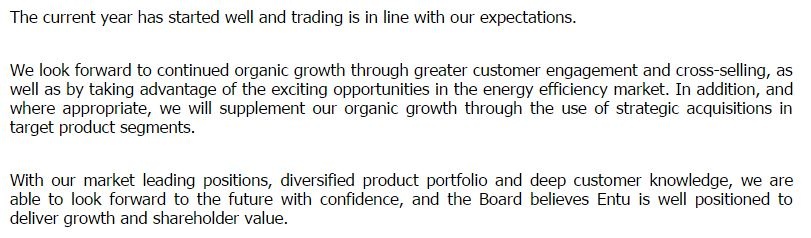
My opinion - as you've probably gathered by now, I like this share! It's just a classic value share in my view, with a low PER and an attractive dividend yield, and a capital-light business model, with net cash in the bank.
Sure it's cyclical, but I think with interest rates low, and consumers having more discretionary spending & confidence, this is the right time in the cycle to be looking at companies like this. There might also be something of a backlog of home improvement work possibly? i.e. if consumers have felt nervous over the last few years, now that they can finally see incomes rising ahead of inflation again, then they are more likely to decide to have new windows, or a conservatory, which they might have been putting off for the last few years perhaps?
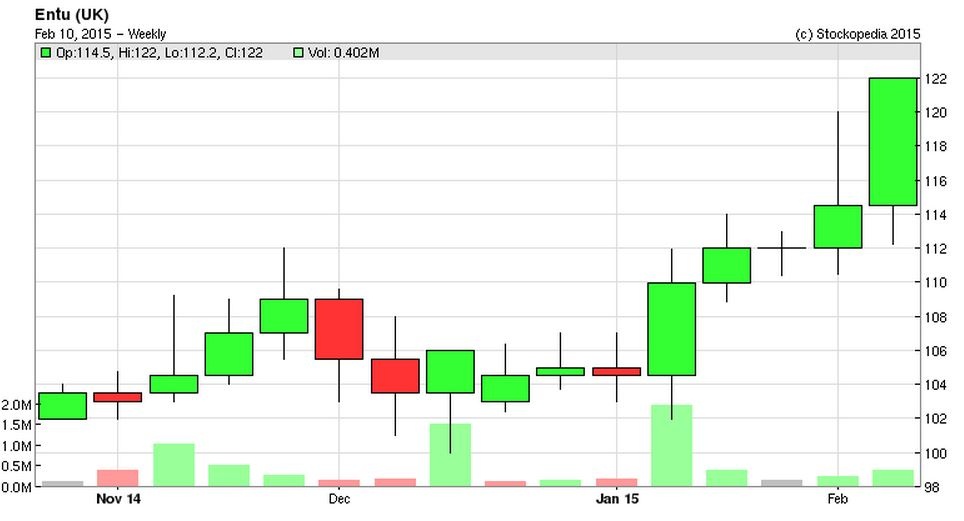
Not all IPOs are over-priced flops. It's good to see that Entu seems to have been priced sensibly, even cheaply, as it has risen since the IPO;
Agreement with Flow Group - we were discussing Flowgroup (LON:FLOW) yesterday funnily enough, and today Entu has announced that it will be an authorised installer of these new boilers. So in a way perhaps Entu is a picks & shovels type of investment, whereas Flow is the more speculative (higher risk, but higher potential reward) share. It seems a good fit with Entu's existing product offerings, which have a theme of environmental benefits.
Entu already has the sales teams out there, and the installation teams, so adding another product onto that infrastructure should be positive for both companies, I imagine. It might also provide useful intelligence about how well (or not) Flow products are selling. So if Entu announce that they are selling like hot cakes, then that could be my cue to buy back into Flow shares, with a bit more comfort that commercialisation is working. For the moment though, I'm watching and waiting re Flow.
UPDATE - I've had a useful telecon with the CFO of Entu, and comment as follows;
Bank facilities at the moment are modest, and not utilised. However, the bank is receptive to providing finance for possible acquisitions. The company would limit any future borrowing to under 2 times EBITDA, which sounds fine to me. Lots of potential acquisitions in this space. Being a Listed company has raised their profile.
Divisional profit - the warranties business looks highly profitable, but it shares the overheads (free) of other divisions. So would be much less profitable if costs were allocated.
Improved performance from smaller divisions is expected to continue.
Flexible cost basis means the group can adapt easily & quickly to market changes. They like having a portfolio approach, so if demand weakens in one area, they can make it up elsewhere.
Related party transactions - these were over-reported, to be completely open. Due to changes in shareholdings, there won't be related party transactions in future. A lot relates to Epwin, which has itself now Listed.
Flow group - Entu really likes their product, and think it has huge potential. So hoping for a big future from this new product line.
Hornby (LON:HRN)
Trading update - it sounds as if things are stabilising at the previously troubled toy models maker. The company today says that sales & profits for the year to date (y/e 31 Mar 2015) are in line with expectations.
Net debt has come down a bit, to £7.9m at end Dec 2014, although I assume that might be a seasonally positive cash position after Xmas sales are in the bag?
The company is relocating from its outdated Margate site, to a modern office in Sandwich. Note that the Margate site is freehold, so one would need to find out how much that is worth. Probably not much, given that it's in Margate, but who knows?!
Outlook - positive noises are made about reaction to new ranges, at toy fairs, etc.
My opinion - it seems to me that the shares are already pricing in a significant recovery in earnings, which hasn't happened yet. It's priced at 26 times this year's earnings, which seems way too high to me. That is basically asking you to pay up-front for a doubling of profit in future, when there's no guarantee such a doubling will happen.
The price looks much too warm to me. I suppose people are hoping it can get back to 10-12p EPS levels that it achieved prior to the supply chain problems. However, there are no dividends, and if you want a cheap toy company, then it seems to me Character (LON:CCT) is a vastly better value proposition right now. It's trading well, is cheap, and pays divis. Whereas Hornby is expensive, doesn't pay divis, and has too much debt. It's a very easy choice for me - I'm long Character Group.
Simigon (LON:SIM)
A positive trading update today has propelled these shares up 19% to 25p today.
It's based in Israel, and as regulars know, I rarely touch any overseas companies listed on AIM. The company is also very small. It has high cash balances for the size of company, and has started paying divis too - although I believe there can be a problem of withholding taxes when it comes to divis from Israeli companies, so that needs checking.
All in all, might be worth a look for the more daring of you!
All done for today!
Do check out the new "Ranks" tab at the top of the Stockopedia black menu. Ed explained the new features very well today, although it amused me how he chose Rank (LON:RNK) to explain the Ranks! So it got slightly confusing lol!
See you in the morning.
Regards, Paul.
(of the companies mentioned today, Paul has a long position in ENTU, and no short positions. A fund management firm with which Paul is associated may also hold positions in companies mentioned)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

18 comments
Just been through the Entu (UK) (LON:ENTU) numbers and concluded its a Growth share prices at a Value share multiple. My notes below:
Cyclical, New SP high, Low ttm PE, Inter-company Cross selling opportunities, Top line growth, Fantastic cash generation and returns because no manufacturing base and low centralized fixed costs. Operationally geared, Acquisitive, Boring with High Dividend, Under the Radar. Undervalued. Rgds Ian
Sounds interesting, and this is probably a silly question but why is stockopedia showing no p/e or yield for entu ?
Hi Kenobi,
Thomson Reuters doesn't seem to have picked up broker forecasts for Entu (UK) (LON:ENTU) .
I have raised a green support ticket, so hopefully should get fixed in the next few days.
Regards, Paul.
Ok, great, Thanks Paul,
keep up the good work !
K
Paul,
Looks like you will have done very nicely on Character in the last 3 months alone!
Looking back:
(i) Positive trading statement in early September
(ii) Several high value director sales in late September (admittedly leaving big holdings afterwards)
(iii) Very good results just a few weeks after that, with a large increase in share price..
I would have swiftly dismissed it on the director sales alone. Not good decision making there.
Jeff
Hi jonesjeff,
Indeed, I've had a very good run with Character (LON:CCT) . The unfortunate thing is that, because it's so illiquid, and has a wide bid:offer spread, I didn't buy enough of them personally, and sadly wasn't able to get any at all for the clients of the portfolio service that I assist with (as it was below the minimum liquidity threshold that we are able to deal at with the service provider). Pity.
Funny you should mention Director selling not being a good indicator in this case. I've found that Director buying/selling has been a fairly poor indicator in the last year or so. It's led me up the garden path a couple of times (e.g. big Director buying at PuriCore (LON:PURI) came to nothing).
So I'm tending to de-emphasise Director dealing these days, unless it's an absolutely massive buy or sell.
Regards, Paul.
Paul,
I can see where you are coming from.
inevitable but.....I worked for a plc which never listed but was a public company. They told investors they would list but then never bothered! (no exit). Then the owners ploughed company money into vanity projects: theatre productions, a terrible movie (self-penned). I had options and when I had an option to cash in I did immediately and even left the co. I figured the management were not sufficiently focused on running the core side of their business.
Also I remember Sibir energy - an oil co. funding CEO's property gambles? V. dubious imo.
As for ENTU - I think they look like value but worry about the moat/barriers to entry. Great ROCE, surprisingly fat margin. Quite surprised to see that actually. I'll have to take another look - wasn't expecting margin 31% and ROCE 61.1%
Fairly recent member of Stockopedia . Usually read Paul but this is the first I have been encouraged to buy. It looks very good opportunity, I only hope the company performs better than the Sale Rugby Club
Hi Paul,
Agreed that ENTU now looks great value, bought into them this morning and hoping for a rerating.
As a small cap writer, did you notice TERN.L reported this morning?
They are a tech company which owns a large part of cryptosoft, an encryption company that is into "the internet of things" loss making last full year(reported today) but looks like its going in the right direction re profit/earnings/cash flow etc.
Might be worth a scroot.
regards
mrwhits.
Hi mrwhits,
No, Tern (LON:TERN) is too small for me.
The company had quite a bad reputation too in the past. I did look at it a while ago, when it was a tiny cash shell. I see they are now using it as a tiny incubator company for investing in fashionable sectors that use buzzwords like "cloud" and "mobile".
Looks rather ramperoony to me!
Regards, Paul.
dasv - likewise. I take on board some people's arguments that it is different now that they are a listed company and they were perfectly entitled to provide a large loan to a rugby club that subsequently had to be written off. Of course they were.
However I have decided to err on the side of caution and have taken the 'leopards don't change their spots' approach wrt the management. I may well miss out on a fantastic opportunity but ENTU is one that I am happy to watch from the sidelines. Aimho. Good luck to all those that do invest. I hope it works out.
Would a Ping Pong club have been ok?
rugby club - yep that's why I didn't buy. I almost did. Just didn't rate a management that would ever do that.
Hi dasv,
I can't see what the problem is. Lots of private company owners (probaby most actually) draw no distinction between their personal finances, and a company they own. If you own 100% of a company, and you decide to splurge £ 10m on a rugby club, then it's entirely your own business.
I remember having to persuade a Director of a private company that his wife should stop popping into the nearest branch, to plunder the till for hundreds of pounds when she fancied a shopping spree! She stopped doing it, but actually even then, there was nothing illegal about it - I correctly accounted for the VAT on the sales, so after that it is perfectly permissable to put the net amount of cash withdrawn through a Directors loan account in the books, which they theoretically have to repay at some point. You can literally do whatever you want, if you own the company, and providing the transactions are correctly treated for tax and other reporting purposes.
In a way I find it rather encouraging that Entu (UK) (LON:ENTU) is so cash generative that it was able to easily fund a £ 10m donation to a rugby club when it was a private company!
Of course now it is Listed, then all such activities are strictly outlawed. Totally different ballgame being a Listed company. In fact, let's not even tempt management by calling it a "ball game"!!
Regards, Paul.
I could tell you lots of other stories about wealthy people putting money into rugby clubs, and regretting it, but to save time just google it! The usual approach is that, with a few million they will turn a rugby club into the next Manchester United. Once they've put in about £5-10m, they realise it's a total black hole!
P.
The usual approach is that, with a few million they will turn a rugby club into the next Manchester United. Once they've put in about £5-10m, they realise it's a total black hole!
Do they often realise the ball is the wrong shape first?
Hi Paul
Entu (UK) (LON:ENTU) I liked the numbers too and managed to pick up a few shares before the strong rise. In addition to your comprehensive analysis I'd like to add two further positives.
- Cash Flow from Operations = £10.4m; +93% (greater than PBT = £9m)
- Free Cash Flow = £8.4m; +115%
Hi Ramridge,
Thanks for that. From what I can make out, accounts for Entu (UK) (LON:ENTU) look clean - I can't see any funnies in there, or anything untoward.
I know some people were unhappy with the pre-IPO related party transactions - in particular a c.£10m loan to a Manchester Sale rugby club, which was then written off. I can understand this raising eyebrows, but people can do whatever they like with a private company, and if they want to give away bucketloads of cash to a rugby club, then they could do when it was private. Of course that type of thing is strictly prohibited now it's a public company, which I am sure they appreciate.
There are still some related party transactions, in terms of trading, but that is disclosed in the notes, and providing it's on arms length terms, is tolerable, if not ideal.
It's the divis I'm after though, an 8% yield from IPO was a powerful driver for a re-rating, and that's what seems to be underway now, with the shares up about 20% since the float. I think there could be more to come, if trading continues to be positive.
Regards, Paul.